
3 Australian Founder Led Stocks Trading Below Fair Value
Cyberattacks on crypto platforms like Binance, with multi billion dollar thefts now in the headlines, remind investors how fragile trust can be when managers are distant from the fallout. Founder led Australian companies often look different. The person who built the business still carries the reputational risk and usually a sizeable personal stake. This article highlights three founder driven stocks from our screener that illustrate how that alignment can work in your favour.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally tied to long term outcomes. However, if you want the strongest names, these 7 top founder-led companies are the top of the list.
Flight Centre Travel Group (ASX:FLT)
Overview: Flight Centre Travel Group is a founder influenced travel retailer and corporate intermediary that connects leisure and business customers with airlines, hotels, tours, cruises and foreign exchange services across global brands.
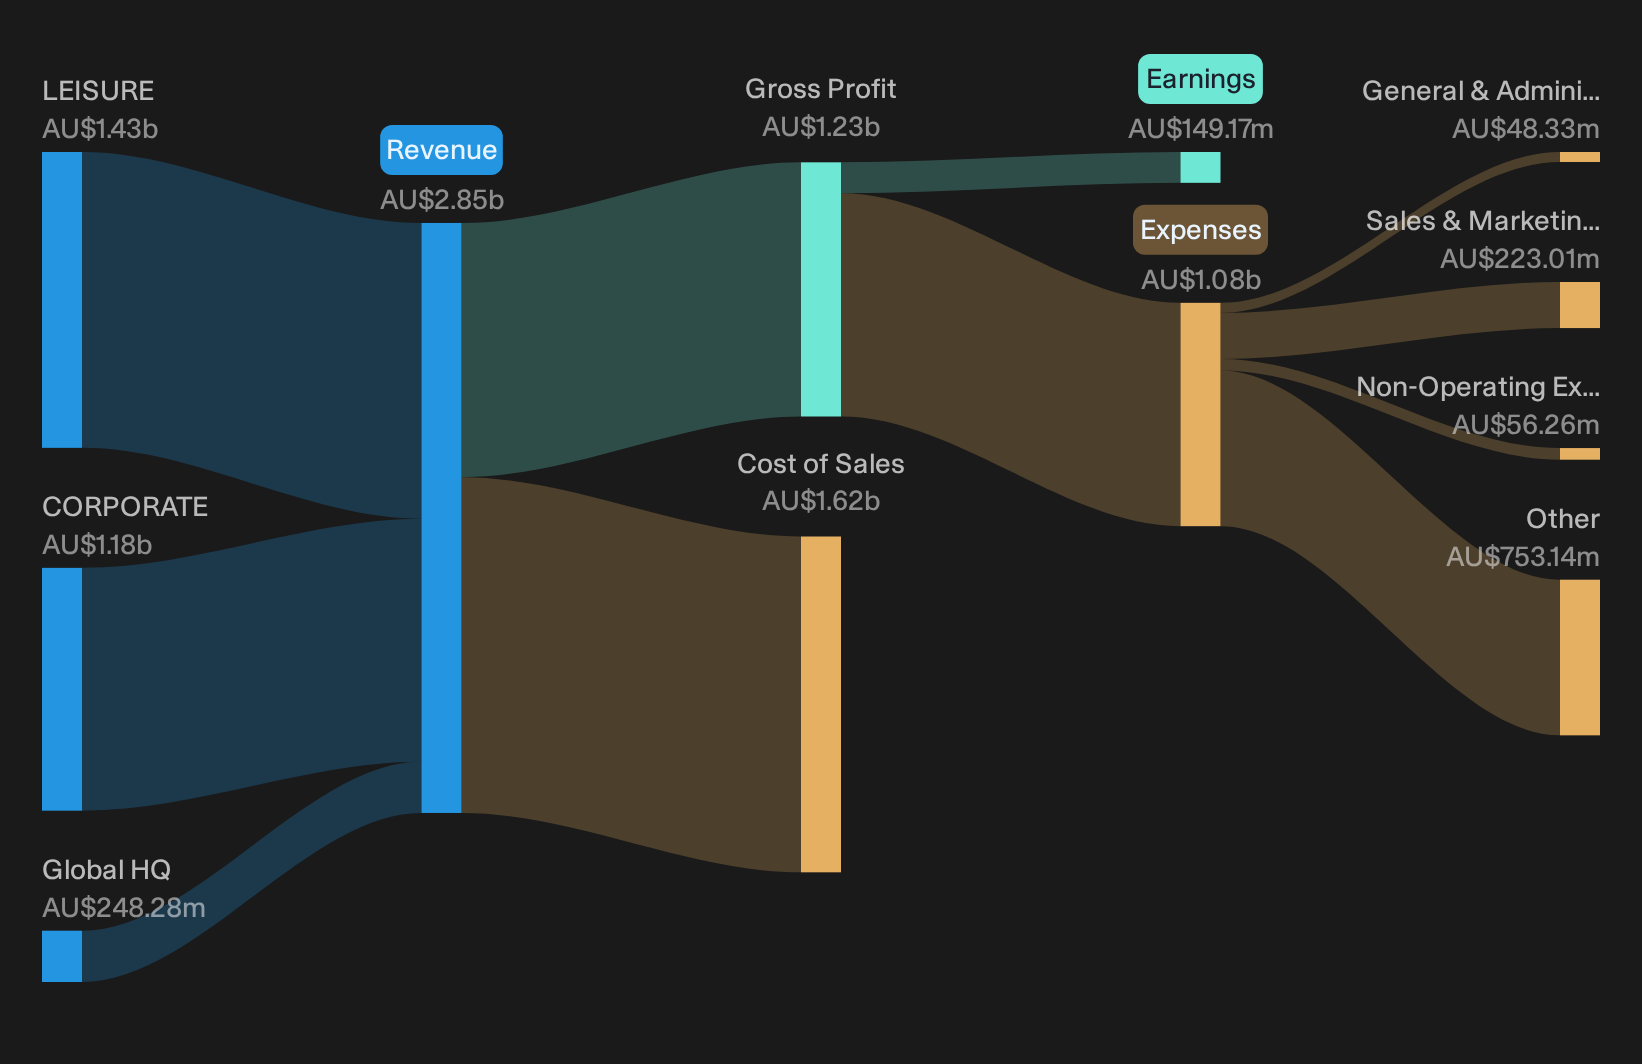
Operations: Flight Centre Travel Group generates about A$1.43b from leisure travel, A$1.18b from corporate travel and A$248 million from global headquarters support activities.
Market Cap: A$2.29b
Flight Centre Travel Group puts founder ownership and long run reputational skin in the game behind a broad travel platform. The group still needs to demonstrate how new investments in loyalty and higher margin niches convert into resilient earnings.
"Despite the rapid customer growth in World360 Rewards, the program has already consumed about A$34 million in below the line spend in FY26 and is expected to incur up to roughly half that amount in FY27 within operating costs, which can weigh on reported EBIT and delay any earnings contribution from higher frequency or partner funded revenue."
What happens to Flight Centre Travel Group’s margin story if one unseen pressure on future profitability shifts even slightly against current expectations?
If that margin pressure matters to you, read the full narrative for Flight Centre Travel Group to see how Flight Centre Travel Group’s reinvestment, loyalty push and founder ownership could still reshape the earnings mix.
Mesoblast (ASX:MSB)
Overview: Mesoblast develops founder led mesenchymal cell therapies like Ryoncil and related MPC candidates to treat severe inflammatory and cardiovascular diseases.
Operations: Mesoblast currently generates about US$120 million in revenue from developing and commercializing its allogeneic cellular medicines platform.
Market Cap: A$2.93b
Mesoblast gives this founder led screener a very different flavour, since the same leadership that built the mesenchymal platform is still steering how Ryoncil and the broader MPC pipeline are pushed toward commercial proof.
"The first and only FDA approved mesenchymal stromal cell product in the U.S., Ryoncil, together with over 1,100 patents and established commercial scale manufacturing, positions Mesoblast to benefit if cell therapies gain wider medical adoption."
What happens to Mesoblast’s path to scale if one assumption about how quickly doctors and payers embrace these therapies proves even slightly too optimistic?
If that pacing risk is front of mind, read the full narrative for Mesoblast to see how Mesoblast’s founder, patents and cash needs could intersect as adoption accelerates.

Harvey Norman Holdings (ASX:HVN)
Overview: Harvey Norman Holdings runs founder led Harvey Norman, Domayne and Joyce Mayne retail and franchise chains, alongside property, leasing and lending operations.
Operations: Harvey Norman Holdings generates A$952 million from New Zealand retail, A$777 million from Ireland, A$787 million from Singapore and Malaysia, and A$260 million from Slovenia and Croatia, with smaller contributions from the UK and other activities.
Market Cap: A$5.15b
Harvey Norman Holdings gives this founder led screener a different flavour. It combines Gerry Harvey’s long running influence over the core retail and franchise format with a sizeable property and leasing engine that can pull earnings in a different direction to store level sales.
"It is worth noting, however, that just over 20% of 2025 profit can be attributed to property revaluations, non-cash gains that can be volatile and are not recurring operational earnings."
This raises the question of what happens to Harvey Norman’s earnings profile if one relatively quiet swing factor starts to move against the founder guided retail story.
If that quiet swing factor worries you, read the full narrative for Harvey Norman Holdings to see how Harvey Norman Holdings balances property revaluations, core retail earnings and founder influence.
Seeking Alternatives Before Everyone Else?
Fresh opportunities do not stay quiet for long. Breakout potential, early momentum and quietly flying under the radar for now can get caught fast. Act now.
- Target dependable income today by scanning proven high yielders in the 4 dividend fortresses before payout momentum cools and yields start dropping.
- Spot early movers in automation by tracking the 96 robotics and automation stocks while these operators still trade like niche ideas rather than crowded trades.
- Position ahead of potential energy shifts by reviewing the 16 nuclear energy infrastructure stocks while sentiment is still catching up to infrastructure demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com