
Exelixis (EXEL) Stock Could Be Below Fair Value On Earnings
Exelixis has seen its earnings come into sharper focus after a powerful multi year share price run, which raises a straightforward question for you as an investor. Is the current valuation still aligned with what the business is actually earning today and is expected to earn in the near term.
- Over the past 5 years the stock has delivered a 249.7% return, which puts real pressure on the question of whether the present earnings justify this kind of compounding.
- Recent revenue progress from CABOMETYX and expectations for higher earnings per share can support a richer earnings profile, which matters directly for how much of today's price is being driven by profit growth versus optimism.
- There is a second opinion on Exelixis worth weighing. See what analysts think Exelixis's shares could be worth.
The issue now is whether Exelixis' current share price fairly reflects the strength and trajectory of its earnings profile.
If you want to test the same earnings question you are asking of Exelixis across a broader opportunity set, benchmark it against 30 high quality undervalued stocks.
Is Exelixis Still Cheap on Earnings?
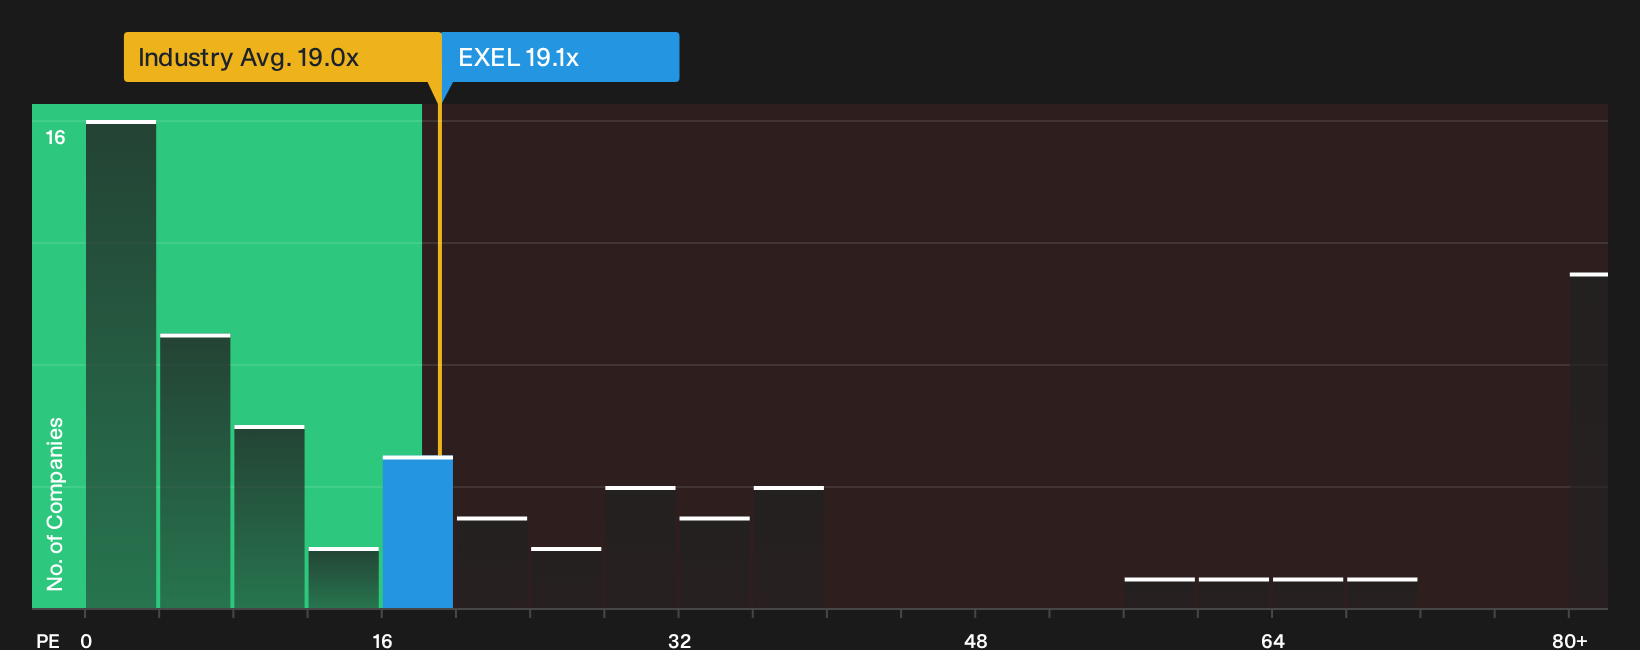
The P/E ratio suits Exelixis because investors are clearly focused on the earnings power behind CABOMETYX. On this metric the stock trades at about 19.1x earnings, which is very close to the broader biotech sector average of roughly 19.0x and well below the peer group closer to 57.3x. In this context, the multiple appears lower than many comparable stocks that share the same broad industry label.
Because the current P/E sits below what a tailored fair multiple would suggest for Exelixis, the shares appear undervalued on this earnings yardstick. The second quarter 2026 report and the expected 17.8% EPS uplift this year already have investors paying more attention to profit trends. Yet the present multiple still aligns more with a discounted view of that earnings profile than an aggressive one. The gap between where the stock trades and where the fair P/E sits is what the detailed valuation work is trying to help you quantify. Explore the numbers behind Exelixis's P/E valuation.
The Exelixis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Exelixis turn that P/E puzzle into explicit scenarios you can inspect rather than imply. Each one links its number to a clear view on where Exelixis' growth, profitability and risk profile might head next. This gives you something concrete to revisit as fresh quarterly results, pipeline news and market data arrive on the Community page.
Community views on Exelixis are split between those who see more upside in the pipeline and buybacks and those who focus on patent and execution risk.
Bull case: roughly fairly valued
"The continued execution of a large scale share repurchase program, with roughly US$2.9b already spent since 2023 and about US$598m still authorized..."
Discover why this Narrative puts Exelixis at roughly fairly valued.
Bear case: 21% overvalued
"Cabozantinib remains the dominant revenue driver for Exelixis, so any earlier than expected loss of exclusivity, faster than expected generic erosion..."
Explore why this Narrative puts Exelixis at 21% overvalued.
Exelixis price is only one side of the decision
Valuation tells you what the market is paying today, but analyst projections for where Exelixis might be a few years from now offer a separate reference point for your own expectations. Explore where analysts expect Exelixis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com