
Amaero (ASX:3DA) Shares Look Fully Priced Against Its Sales Story
Amaero has seen a mixed share price story, with shorter term gains sitting against longer term weakness, which naturally puts the focus on whether its current market value lines up with the revenue it generates. For anyone looking at Amaero stock today, the core issue is whether the recent price puts a reasonable tag on its sales base.
- Over the past 5 years the share price has fallen 49.3%, which raises the question of how much weight the market is putting on Amaero's current and potential sales.
- The business model relies heavily on turning its specialist manufacturing capabilities into reliable sales growth, so any change in how consistently it can win and retain contracts may affect how investors think about what each dollar of revenue is worth.
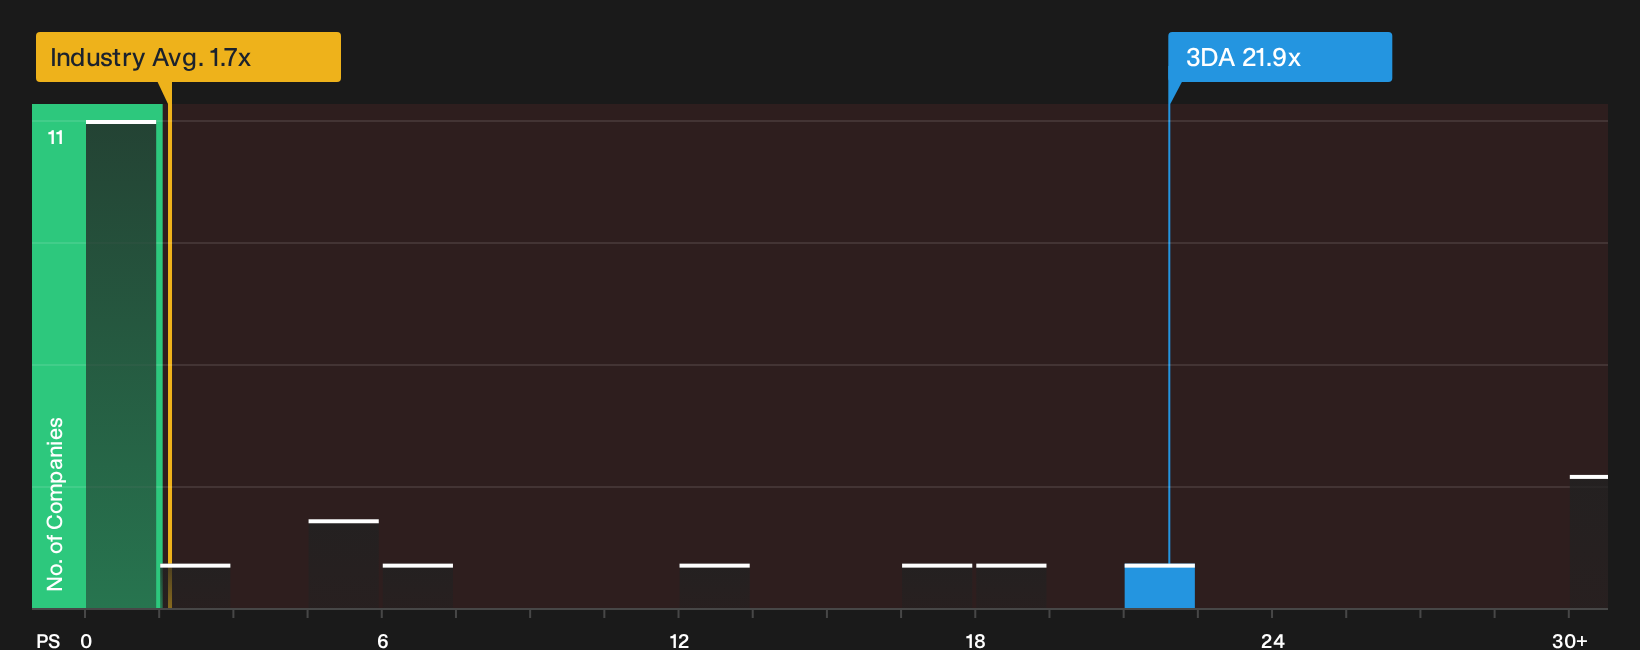
- Amaero's multiple only means something next to the competition. See how Amaero's 21.9x P/S compares with its peers.
The stock's next move may depend on whether Amaero's current share price is well supported by the level and quality of its sales.
To see whether Amaero's sales based valuation question appears elsewhere, you can compare it with other industrials using solid balance sheet and fundamentals stocks screener (12 results).
Is Amaero Getting Expensive on Sales?
P/S fits Amaero because the business is still focused on building its revenue base rather than producing consistent profits. On this measure, the stock trades on a P/S of 21.9x, compared with a Machinery industry average of 1.7x and a peer group average of 26.9x. That is a very rich tag for each dollar of sales, even if the figure sits below similar companies followed in this peer set.
The fair value framework, which adjusts for Amaero's growth profile, margins, size and risk, points to a lower multiple than the current 21.9x. The gap suggests the model is heavily penalising ongoing losses and cash outflows. On this yardstick, the high P/S looks expensive rather than like a small premium that solid execution could quickly justify. Investors weighing Amaero today would need strong conviction about the quality and durability of future contracts to feel comfortable paying this kind of revenue multiple. Explore the numbers behind Amaero's P/S valuation.
The Amaero Narrative: What Would Justify Today's Price?
Amaero's Simply Wall St Narratives pick up where this pricing puzzle leaves off, spelling out which combinations of future growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or richer than it appears today on the screen. Instead of relying on a single multiple or model output, each scenario lays out the assumptions behind its fair value so you can track those expectations against Amaero's reported numbers over time on the Community page.
One of the top community narratives on Amaero: 76% undervalued
"Moves by large multinational OEMs and medical device companies to reshore production and qualify U.S. sourced powders create a pipeline of multi year supply agreements…"
Discover why this Narrative puts Amaero at 76% undervalued.
Amaero's price is only one piece of the decision
Before you decide how Amaero fits into your watchlist, it is worth asking who is steering the business, how their incentives are structured, and whether those rewards truly line up with your own goals. See who runs Amaero and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com