
Learn Why The Bull Case For Li Ning Stock Could Change Following Merchandise Consignment Deals
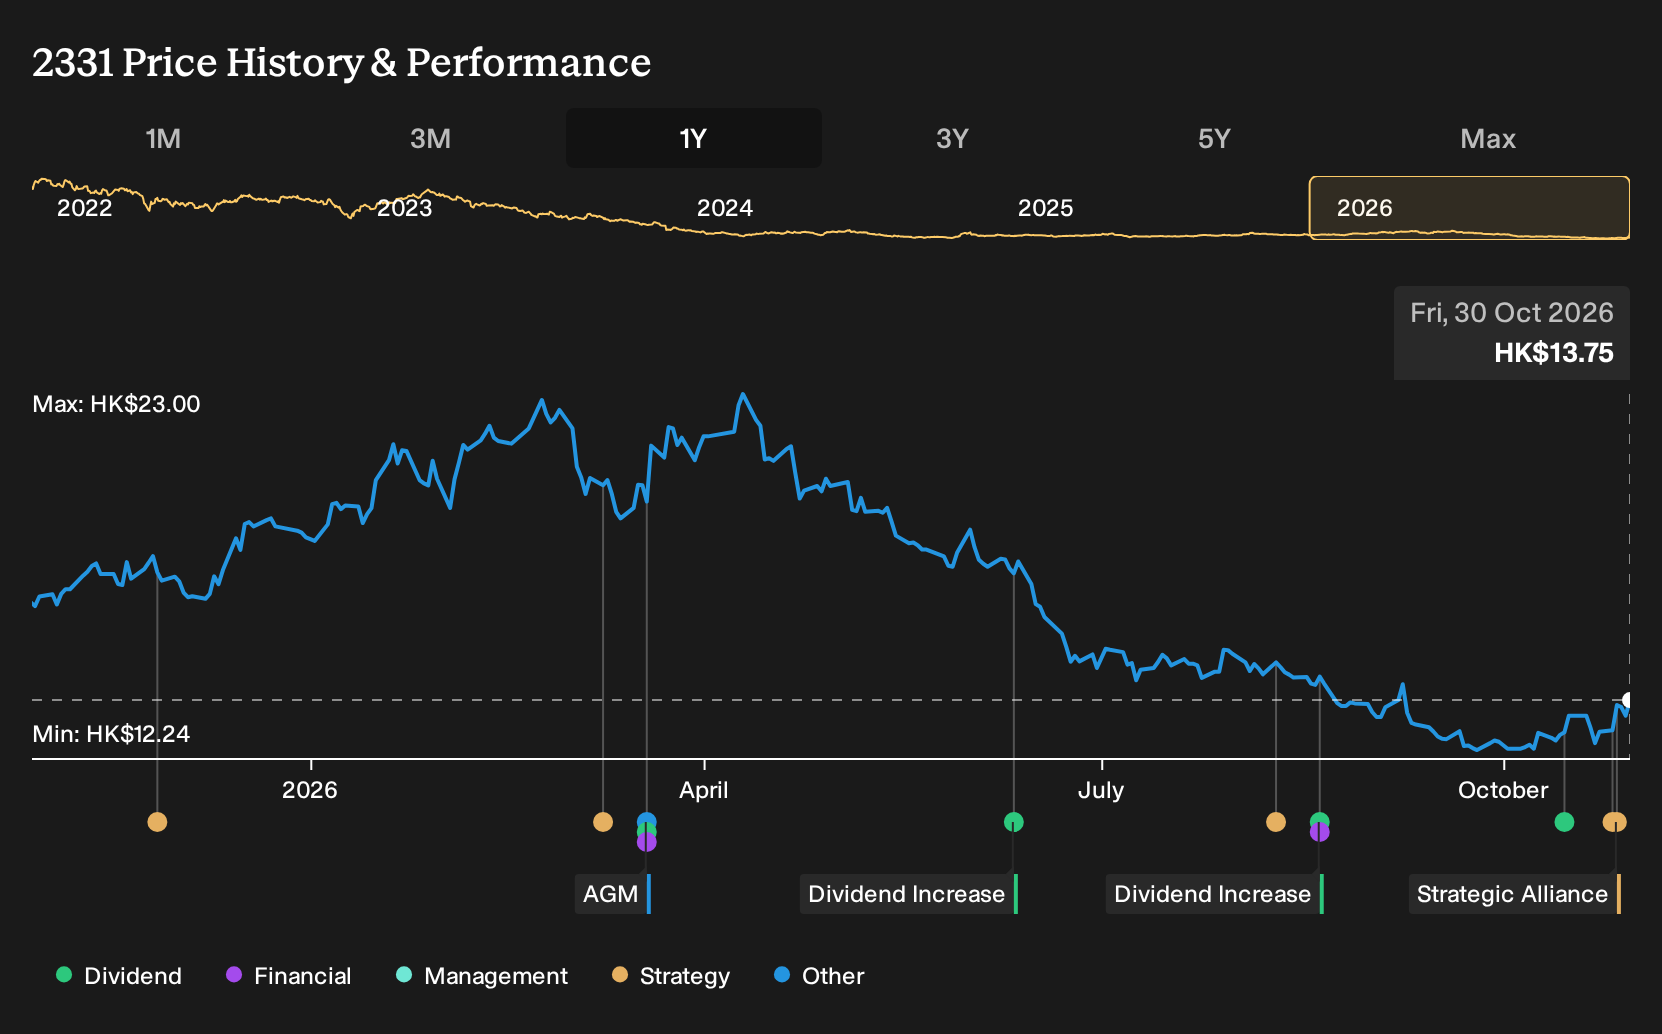
- In October 2026, Acceler8 Ventures reported that its Hui10 unit signed three consignment deals with Li Ning regional subsidiaries in Beijing, Shanghai and Shenyang, supplying authorised sportswear for Lucky World and TEAM CHINA across online and selected physical outlets.
- The consignment setup lets Lucky World carry Li Ning products without upfront wholesale payments while tying merchandise directly into Hui10's Love Beans and Lucky Beans e-voucher loyalty system, which reshapes how Li Ning connects product demand with closed-loop rewards spending.
- This analysis reviews how Li Ning's investment narrative may be influenced by this consignment led expansion of Lucky World's merchandise.
Scan how Li Ning is plugging into loyalty driven retail ecosystems, then size up other consumer companies tied to similar demand funnels with 605 high quality undiscovered gems
Li Ning Investment Narrative Recap
To own Li Ning, you need to believe the brand can convert its strong recognition and sports focus into healthier digital driven sell through, while managing promotional pressure in China. The biggest near term swing factor is how effectively e commerce and omnichannel efforts turn traffic into full price sales and better mix.
The key risk still sits in weak consumer demand and heavy discounting, which already pressured categories like apparel and basketball and nudged gross margin lower to 50%. The Hui10 consignment news looks helpful for reach and engagement, but by itself it does not materially change that near term risk reward balance.
One recent theme that lines up closely with the Hui10 deal is Li Ning's push into e commerce and omnichannel. Online revenue already accounts for 31% of the total. The Hui10 and Lucky World consignment structure plugs directly into that effort by adding more digital points of sale without Li Ning carrying extra inventory on its own balance sheet.
For catalysts, this type of partnership lives or dies on execution. If the merchandise mix, pricing discipline and voucher economics are tight, it can support higher quality demand and help offset pressure from weaker offline traffic and promotions. If it dilutes pricing or shifts volume away from better margin DTC channels, it could amplify existing risks.
Li Ning's consensus story points to revenue of CN¥35.1b and earnings of CN¥3.3b by 2029, based on analysts' assumption of 5.4% yearly top line expansion and an earnings increase of roughly 10% from CN¥3.0b today.
Uncover why Li Ning's fair value indicates a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative Li Ning story leans heavily on the potential catalyst from performance categories and technology platforms. The most optimistic analysts were already pencilling in revenue of about CN¥37.5b and earnings near CN¥5.0b by 2029. Those forecasts came before the Hui10 consignment news, so you may want to compare several viewpoints before deciding how this update could shift expectations.
Explore 2 other Li Ning fair value estimates, including one that suggests as much as 120% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Li Ning research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Li Ning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Li Ning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Li Ning?
If the Li Ning story has sharpened your thinking about brand power, digital funnels and risk, use that same lens across other opportunities. The Simply Wall St Screener helps you quickly sort through hundreds of listings so you can focus on a shortlist that fits your style, rather than chasing whatever is moving on any given day.
- If capital preservation comes first for you, start with a basket of sturdier businesses through 220 resilient stocks with low risk scores that already clear basic resilience checks.
- If balance sheet strength matters more than hype, filter for companies with cleaner debt profiles and fundamentals using the list of solid balance sheet and fundamentals (203 results).
- If you prefer situations that the market may not be paying full attention to yet, scan for under-the-radar opportunities with fundamentals via 605 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com