
Kilroy Realty (KRC) On Raised 2026 Guidance And What It Means For Valuation
Why Kilroy Realty Stock Is In Focus After Fresh Guidance
Kilroy Realty (KRC) moved into the spotlight after management raised full year 2026 earnings guidance and released third quarter and nine month results on October 22, giving investors new numbers to reassess the stock.
The guidance bump landed on a stock that has started to regain some traction, with a 1 day share price return of 2.42% and a 30 day share price return of 7.59%. However, the 90 day share price return is down 6.21% and the 1 year total shareholder return is down 6.31%, while the 3 year total shareholder return is up 43.85%. This shows that short term momentum is building on top of a mixed longer run record.
Compare Kilroy Realty’s guidance-driven move with a curated group of real estate and income-focused stocks by scanning our 7 dividend fortresses to see how other high-yield plays are reacting to earnings updates.
After the post guidance bounce in Kilroy Realty, the question is simple: Do you pay up for the momentum today, or wait for a cheaper entry that better reflects the new earnings path?
Most Popular Narrative: 9% Undervalued
Kilroy Realty’s most followed narrative pegs fair value at $40.14, above the recent $36.41 close. This puts fresh guidance in a different light for anyone weighing short term momentum against longer term cash flow potential.
The pool of more than 1,000,000 square feet of signed but not yet commenced leases carrying about US$78 million of annual base rent and a high share of triple net structures is poised to feed through into higher occupancy, revenue and potentially wider net margins as these leases commence.
See why 15 investors see Kilroy Realty as 9% undervalued.
Result: Fair Value of $40.14 (UNDERVALUED)
Still, the Kilroy Realty story hinges on lifting portfolio occupancy from about 77% and managing the sizable 2027 lease rolloffs at DIRECTV, AT&T, and Long Beach.
Find out about the key risks to this Kilroy Realty narrative.
Another View: Kilroy Realty On Earnings Multiples
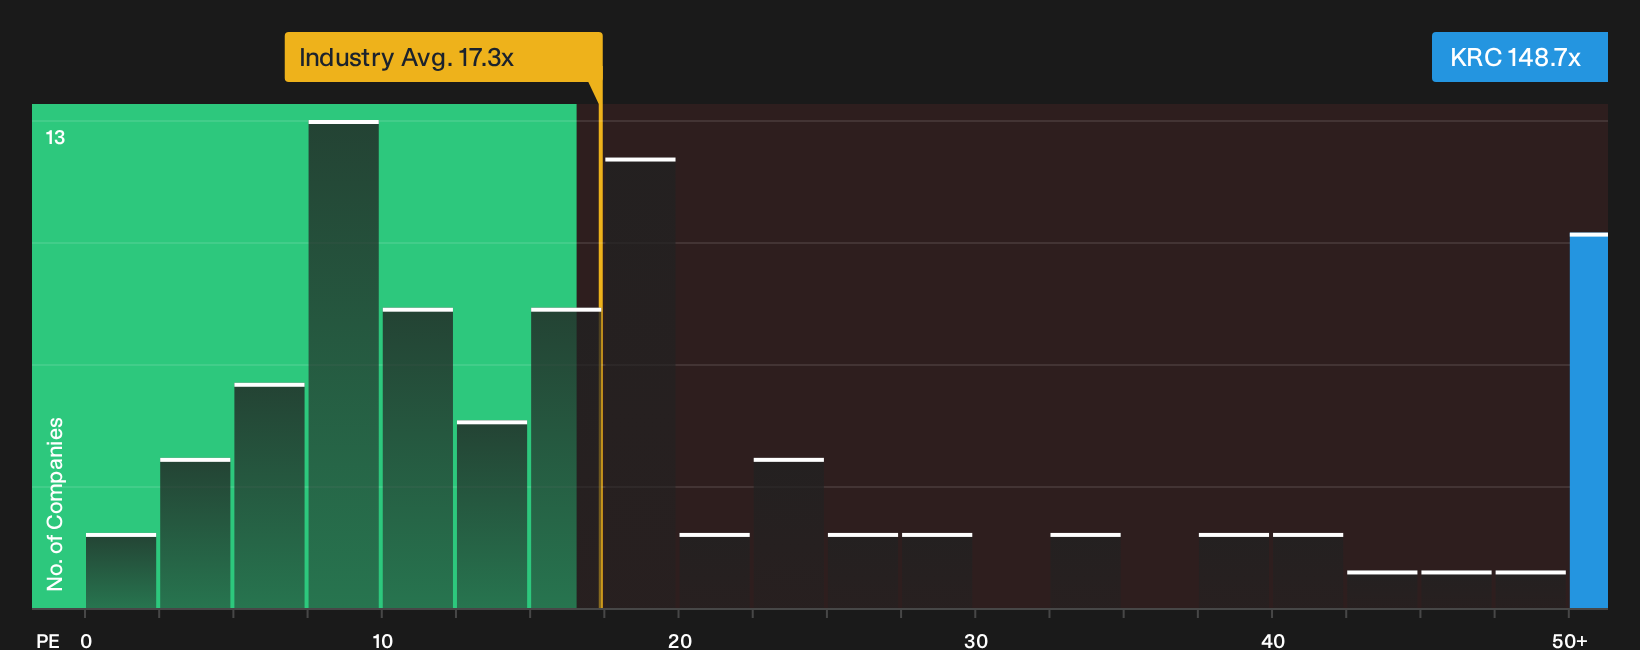
The earlier fair value of $40.14 paints Kilroy Realty as undervalued, yet the current P/E of 148.7x tells a very different story. That figure is far above the fair ratio of 48.2x, the peer average of 34.8x, and the Global Office REITs average of 17.3x.
Such a wide gap means investors are paying a rich price for each dollar of current earnings, which leaves less room if profit expectations fall or get delayed. The question is simple for anyone watching fresh guidance closely: Is this multiple a cushion or a risk if the recovery takes longer than hoped?
For a closer look at how this pricing stacks up against cash flow and earnings power, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Kilroy Realty can feel messy, so move quickly, review the full data set, and weigh both sides of the story with 3 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Kilroy Realty?
If Kilroy Realty has your attention, do not stop here. Broaden your watchlist with fresh ideas that match different goals, risk levels, and income needs.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) to filter for financially robust businesses built to handle bumps in the cycle.
- Hunt for quality at a discount with the 30 high quality undervalued stocks to surface stocks where fundamentals and current pricing appear meaningfully out of sync.
- Prioritize consistency and lower volatility potential through the 30 resilient stocks with low risk scores to focus on companies with stronger risk scores and more stable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com