
How Investors May Respond To Simpson Manufacturing (SSD) $1 Billion Buyback
- Simpson Manufacturing reported Q3 2026 sales of US$638.13 million and net income of US$109.12 million, reaffirmed full year operating margin guidance of 20.0% to 20.5%, and declared a US$0.30 quarterly dividend payable in January 2027.
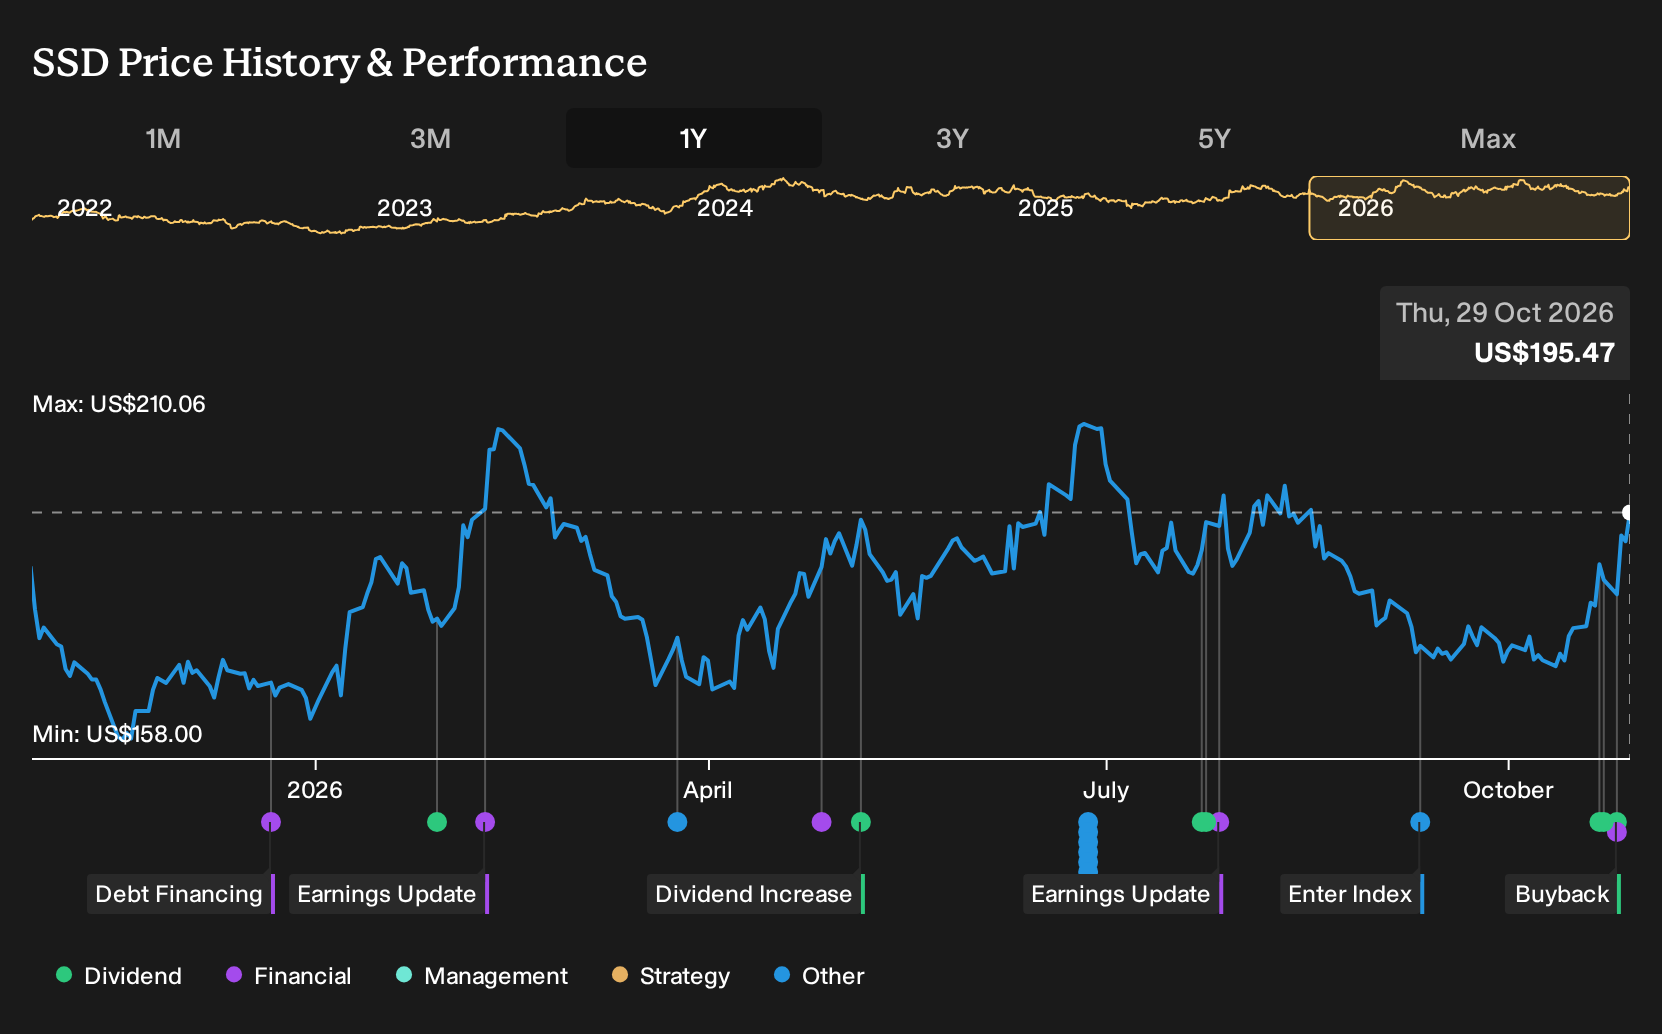
- The board paired these results with a new US$1 billion share repurchase authorization, following completion of a prior US$165.17 million buyback that retired 2.15% of outstanding shares. This underlines active capital return alongside cost and efficiency efforts.
- We will now look at how Simpson Manufacturing's new US$1 billion buyback authorization could influence the existing investment narrative around margins.
Scan how Simpson Manufacturing’s fresh buyback and margin guidance stack up against peers by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) in related construction and industrial suppliers.
Simpson Manufacturing Investment Narrative Recap
To stay invested in Simpson Manufacturing, you need to believe that resilient demand for engineered connectors and fasteners can offset softer construction volumes and mix headwinds. The latest quarter showed the business still generating earnings and margins consistent with that view, supported by cost control and pricing rather than volume strength.
The key short term swing factor remains how global building activity trends from here, especially in higher content regions. A deeper slowdown would threaten volume and price discipline. The reaffirmed 20.0% to 20.5% operating margin guidance, including the vacant land gain, points to limited change in that near term risk reward balance for now.
The new US$1.0b share repurchase authorization is the announcement that most directly frames this earnings update. It signals the board is comfortable committing a substantial pool of capital while Simpson Manufacturing is contending with softer volumes and inflationary input costs, relying on its current cash generation and balance sheet.
For you as a shareholder, that authorization matters mainly as a potential support for earnings per share, assuming execution is disciplined and end markets do not worsen materially. It also amplifies the existing capital return mix alongside the US$0.30 quarterly dividend, while leaving the core operational catalysts and construction cycle risks essentially unchanged.
Analysts see Simpson Manufacturing reaching US$2.7b in revenue and US$433.9 million in earnings by 2029, based on an assumed 3.3% yearly revenue growth rate and an earnings increase of about US$55 million from current earnings of US$378.9 million.
Uncover why Simpson Manufacturing's fair value indicates a 12% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community sit between US$73.50 and US$219, so some private investors see Simpson Manufacturing as deeply undervalued while others place it much higher. Set those views against the risk that prolonged construction softness or tougher price competition limits earnings progress. Use that contrast to test your own thesis and explore how different assumptions reshape the story.
Explore 4 other Simpson Manufacturing fair value estimates, including one that suggests as much as 62% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment performance rarely comes from following the herd, so consider forming your own view.
- A great starting point for your Simpson Manufacturing research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Simpson Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simpson Manufacturing's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Simpson Manufacturing?
If Simpson Manufacturing’s mix of cash returns and margin focus has your attention, it can help to line it up against other potential opportunities. Use the Simply Wall St Screener to scan for different types of businesses that match the style of portfolio you want to build.
- For investors hunting for overlooked value with solid fundamentals, review a curated set of 18 high quality undiscovered gems that may not yet be on everyone’s radar.
- If capital preservation and steadier profiles matter most to you, filter for 30 resilient stocks with low risk scores that score well on financial resilience and business quality.
- Income focused readers can narrow in on yield potential by checking a focused group of 7 dividend fortresses that pair higher payouts with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com