
Hexagon (OM:HEXA B) Rebounds On Earnings As The Valuation Case Gets Harder To Ignore
Why Hexagon’s latest earnings matter for shareholders
Hexagon (OM:HEXA B) has investors’ attention after its 23 October quarterly update, which showed higher sales and a swing back to profit compared with the loss reported a year earlier.
Hexagon’s quarterly rebound has come alongside a clear shift in sentiment, with the share price delivering a 7.9% 7 day gain and a 17.6% 90 day share price return, while the 1 year total shareholder return of 15.7% and roughly flat 5 year total shareholder return suggest that recent momentum is picking up from a much slower longer term journey.
Scan how Hexagon’s rebound compares with other high quality businesses by reviewing our hand picked list of 200 high quality undervalued stocks that are poised for stronger sentiment shifts.
Hexagon’s sharp rebound has already rewarded holders, yet the share price still sits close to its estimated intrinsic value. Is most of the upside already reflected, or does the recent move leave meaningful room ahead?
Most Popular Narrative: 6% Overvalued
Hexagon last closed at SEK110.10, slightly above the most followed fair value estimate of SEK104.03. This estimate is based on a 7.1% discount rate and detailed analyst scenario work around growth, margins and cash generation.
Rising investment in humanoid robotics, with costs guided to about €50m in 2026 and expected to increase further, may take longer than anticipated to translate into meaningful humanoid or autonomy revenue. If commercial traction or pricing power disappoints, the drag on earnings and group return on investment could undermine the current valuation and pressure the share price.
See why 20 investors see Hexagon as 6% overvalued.
Result: Fair Value of SEK104.03 (OVERVALUED)
Still, Hexagon’s case relies heavily on cost discipline and stable demand, so any squeeze on margins or prolonged weakness in key end markets could quickly challenge this narrative.
Find out about the key risks to this Hexagon narrative.
Another View: What Hexagon’s P/E Is Telling You
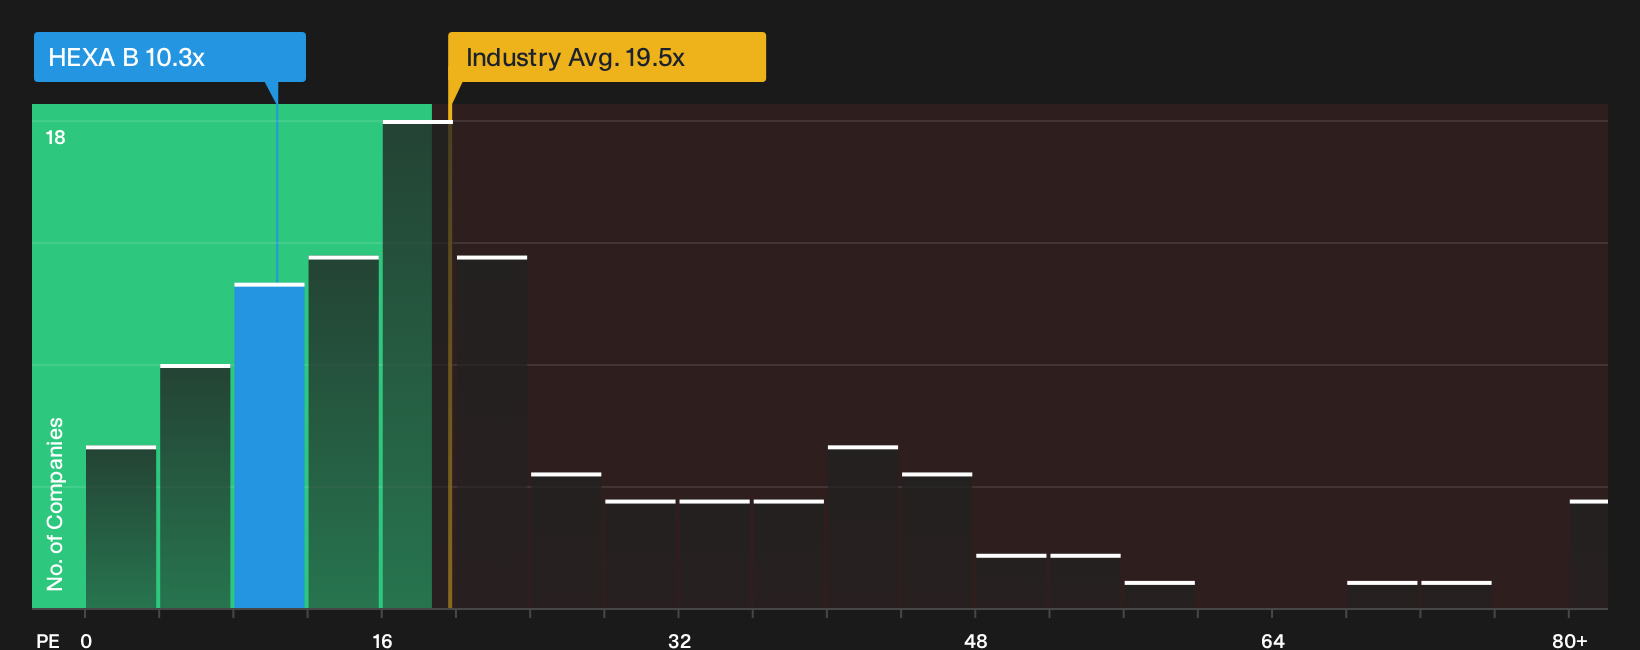
The first fair value narrative points to Hexagon as roughly fully priced, yet the P/E picture looks different. At 10.3x earnings, the stock trades far below the European Electronic industry at 19.5x and well under its peer group on 28x, while only slightly above a 9.6x fair ratio. Is that a cushion or just thinner upside than it appears?
See what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece may feel mixed, with both excitement and hesitation around Hexagon’s setup, so move fast, review the underlying numbers, and weigh the trade offs yourself using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hexagon?
If Hexagon has sharpened your focus, do not stop here. Broader opportunities sit just a few clicks away, and other investors are already looking.
- Target deeper value opportunities by scanning a curated 200 high quality undervalued stocks that combines quality financials with prices that may not fully reflect underlying fundamentals.
- Secure more predictable cash flows by reviewing a focused 223 dividend fortresses that filters for higher yielding businesses with resilience in their payout history.
- Dial down potential volatility by checking a 220 resilient stocks with low risk scores that highlights companies with more robust balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com