
Trupanion (TRUP) Heads Into Earnings With An Undervalued Case Still Up For Debate
Upcoming earnings set expectations for Trupanion
Trupanion (TRUP) heads into its September 2026 quarter report with forecasts calling for earnings of $0.16 per share and revenue growth of 9.6%, putting upcoming results firmly in focus for investors.
The recent swing in Trupanion’s share price has been sharp, with a 30 day share price return of 27.9% and a 90 day gain of 23.3%. Yet the total shareholder return is still down 25.4% over the past year and deeply negative over five years, which points to improving short term momentum against a still bruised longer term track record.
Scan beyond Trupanion and compare its setup with a curated list of insurance and financial stocks showing resilient balance sheets and cash flows using the list of solid balance sheet and fundamentals (23 results).
That rebound in Trupanion could signal investors are warming to the earnings outlook, or it could just be a short term swing in sentiment. How does the current valuation reflect that tension?
Most Popular Narrative: 12% Undervalued
Trupanion’s most followed narrative points to a fair value of $34.25 per share, compared with the recent $30.19 close, which puts current pricing slightly below that implied worth while still asking investors to accept a premium valuation profile.
Improved underwriting discipline, focus on higher lifetime value pets, and optimization of acquisition channels are driving higher-quality book growth and supporting strong free cash flow, setting up for scalable and more profitable expansion in coming years.
The company's increased investment in marketing and pet acquisition, funded by stronger free cash flow and a healthy balance sheet, is expected to accelerate subscriber growth in the back half of 2025 and beyond, supporting faster top-line revenue growth.
See why 6 investors see Trupanion as 12% undervalued.
Result: Fair Value of $34.25 (UNDERVALUED)
Still, Trupanion’s reliance on price increases over true subscriber gains, along with slower momentum in its other business segment, could quickly undercut this undervaluation story.
Find out about the key risks to this Trupanion narrative.
Another view on Trupanion’s valuation
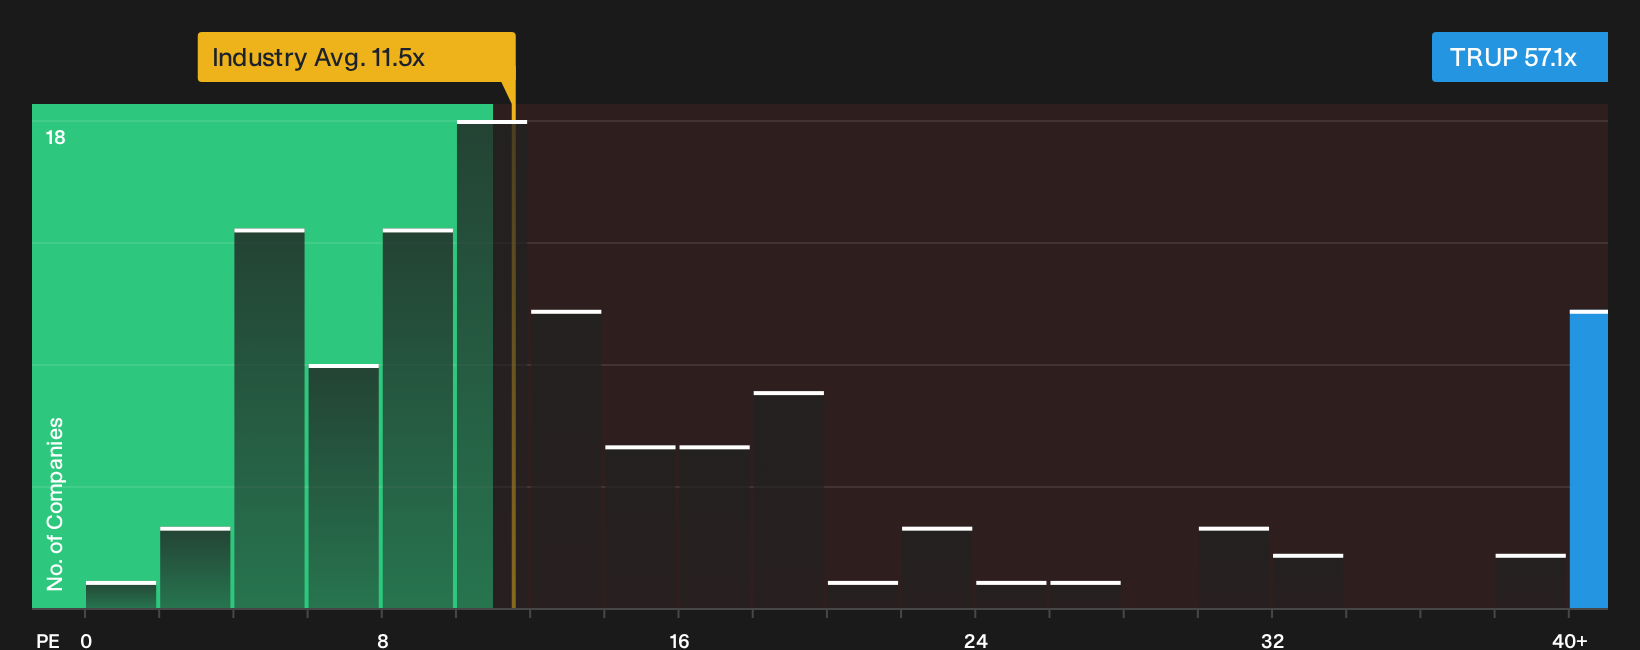
The first narrative paints Trupanion as 12% undervalued at $30.19 versus a $34.25 fair value. A simple earnings multiple tells a very different story. Trupanion trades on a P/E of 57.1x compared with 11.2x for the US Insurance industry, a peer average of 12.4x, and a fair ratio of 12.9x.
That gap implies investors are already paying a heavy premium for future execution, with limited room for disappointment before the share price has to work through that difference. The question is whether you see that premium as justified by Trupanion’s subscription model or as valuation risk that could unwind.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With that mix of optimism and concern around Trupanion, your next move is to pressure test the numbers yourself and decide where you land. To see why some investors still see upside potential, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Trupanion?
If Trupanion has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to uncover fresh ideas before the crowd catches on.
- Target potential mispricings by scanning a focused pool of companies that screen as 30 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by filtering for 30 resilient stocks with low risk scores that may better align with your risk tolerance.
- Spot future contenders early by zeroing in on 18 high quality undiscovered gems that combine quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com