
Should Earnings Beat Require Action From CME Group (CME) Investors?
- CME Group reported third quarter 2026 revenue of US$1,737.3 million and net income of US$1,036.9 million, alongside new crypto and European dairy contracts and record activity in Brazilian real futures.
- The combination of higher recent earnings per share and product expansion into both digital assets and European dairy indicates a business leaning on contract breadth to reinforce its core derivatives franchise.
- The impact of CME Group's stronger recent earnings performance on the investment narrative investors were using before remains to be seen.
Scan CME Group's latest earnings momentum and product rollout against a curated field of exchanges and financial infrastructure stocks using the 30 high quality undervalued stocks as your hunting ground.
CME Group Investment Narrative Recap
CME Group appeals to shareholders who buy into a simple idea. The exchange keeps broadening its contract set, holds tight execution on costs and lets volume flow through a largely fixed cost base. The latest quarter fits that view, with higher revenue, net income and EPS pointing to a business that is still converting activity into earnings.
In the shorter term, the key swing factor remains how much trading interest persists across rates, equity index, FX and crypto products, while competition pushes on benchmark contracts. The biggest watchpoint is still share loss in core asset classes, not this single earnings print, so the near term thesis is broadly unchanged.
The most relevant update for that story is the October launch activity around Bitcoin Cash and Uniswap futures and the first block trade by FalconX and GSR. Crypto is still a smaller slice of CME Group today, yet this shows management continuing to add instruments that can capture incremental hedging and trading demand.
Operationally, that matters because new digital asset contracts can feed both transaction fees and market data revenue if liquidity builds. It also tests CME Group’s ability to compete with offshore venues. Execution risk sits in liquidity seeding, regulatory shifts around crypto derivatives and whether these products reach scale without distracting from benchmark rate and equity contracts.
CME Group Analyst Assumptions In Focus
Analysts sketch a reasonably clear road map for CME Group, with their models leaning on mid single digit top line expansion and high profitability staying intact even as margins ease. The forecasts currently in use assume revenue growth of 6.1% a year over the next three years and a move in profit margins from 63.3% today to 58.7% in the same timeframe, which still leaves the exchange with a wide earnings cushion relative to many financial infrastructure peers.
On the earnings side, the consensus points to profits of US$4.9b by 2029 compared with US$4.4b today. That implies an uplift of about US$0.5b in aggregate earnings for shareholders if those projections prove accurate. Forecasts also bake in a small annual decline of 0.74% in the share count over the next three years, which would slightly amplify earnings per share if buybacks track that path.
The valuation bridge then links those profit expectations to a richer multiple. To line up with the current analyst price target framework, investors would need to be comfortable with CME Group trading at a P/E of 28.5x on the 2029 earnings estimate. That compares with about 25.0x today and is set against an industry P/E reference of 38.1x for US capital markets companies. This anchors the view that the stock is neither deeply discounted nor aggressively priced on these assumptions.
CME Group's narrative projects US$8.3b revenue and US$4.9b earnings by 2029. This requires 6.1% yearly revenue growth and about US$0.5b earnings increase from US$4.4b today.
Uncover why CME Group's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
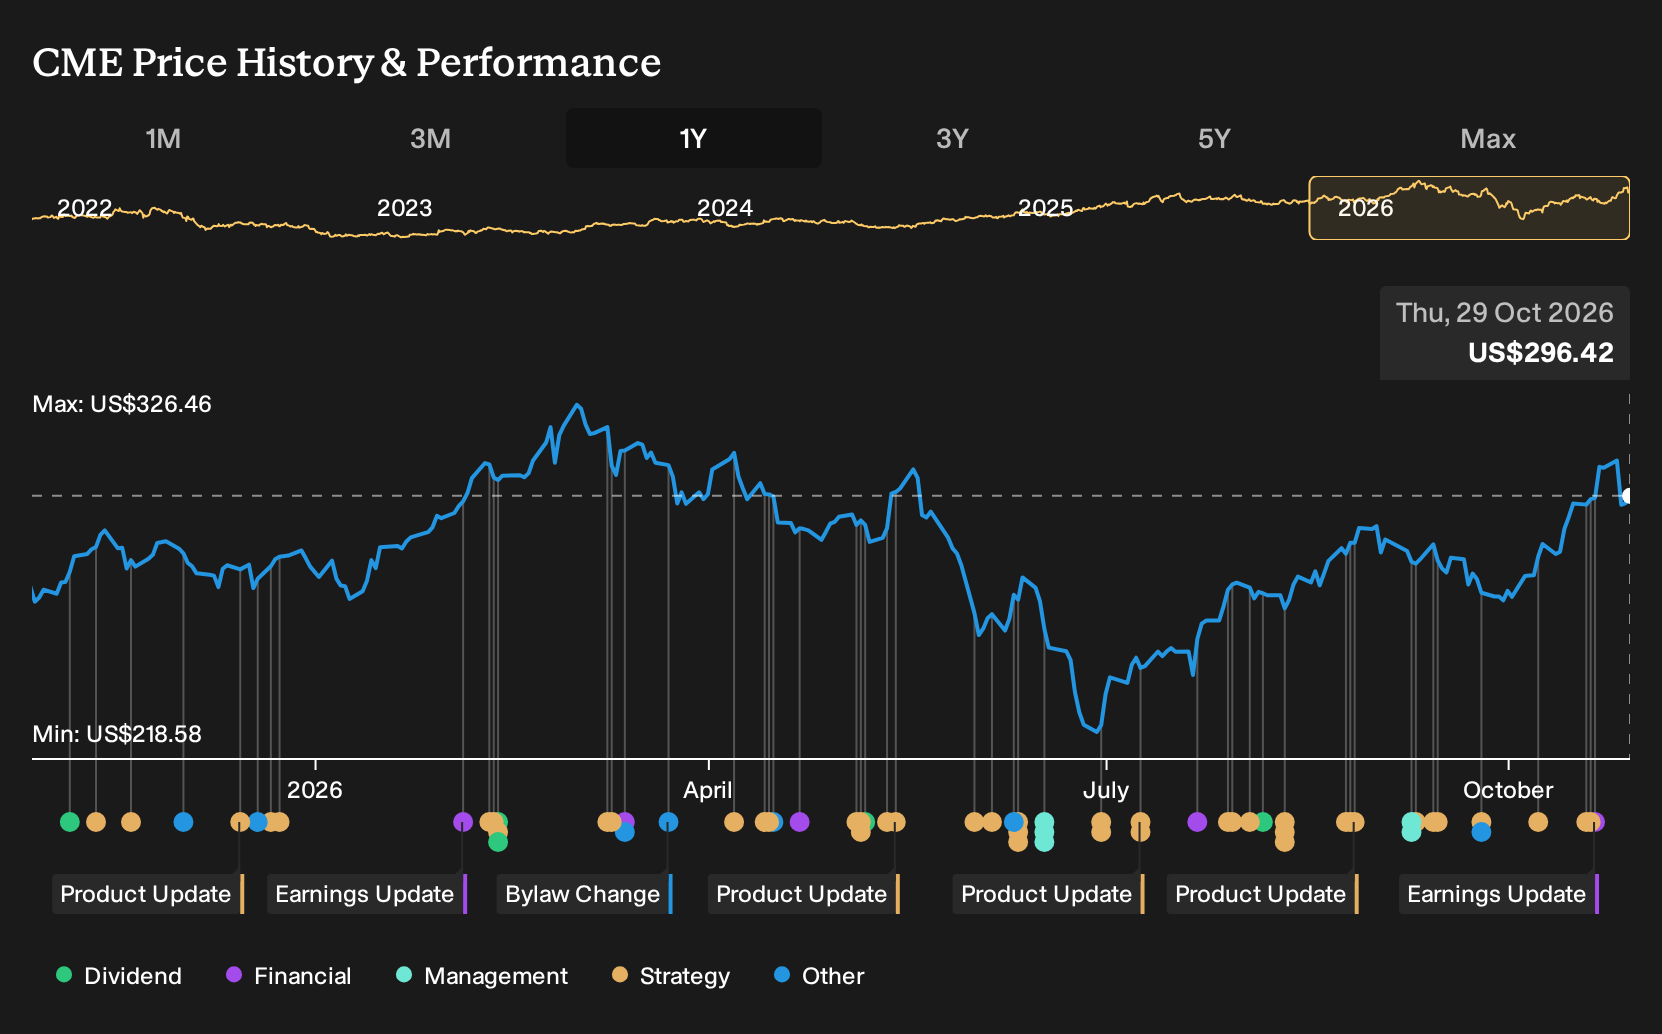
Exploring Other Perspectives
Fair value estimates from the Simply Wall St Community cluster between about US$252.81 and US$317.06 across 3 separate views, which already shows how widely opinions on CME Group can spread. Set that against fresh crypto and European dairy contracts, along with a still watchful eye on competition, and you have several moving parts that could pull future assessments in very different directions. Use these contrasting readings as a prompt to explore more than one angle before anchoring on your own stance.
Explore 2 other CME Group fair value estimates, including one that indicates as much as 15% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CME Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CME Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CME Group's overall financial health at a glance.
Looking for more CME Group style ideas?
If the CME Group story has sharpened your sense of what you want in a business, the next step is lining up a wider watchlist that fits those preferences rather than stopping at a single ticker.
- For investors hunting for potential mispricings with quality behind them, scan a curated pool of companies through the 30 high quality undervalued stocks.
- If resilience and cleaner balance sheets matter most to you, filter for businesses that combine lower leverage with sturdier fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Income focused readers can put cash flow to work by searching for payout heavy opportunities via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com