
Dear Palantir Stock Fans, Mark Your Calendars for November 2
Palantir Technologies' (PLTR) business has evolved well beyond its government roots. Once largely associated with public sector contracts, the developer of artificial intelligence (AI)-powered data analytics software has steadily built a presence in commercial markets, where its technology is finding an increasingly receptive audience.
A major force behind this shift is its Artificial Intelligence Platform (AIP), which helps businesses deploy AI agents and put the technology to work across everyday operations.
That growing commercial footprint has not gone unnoticed on Wall Street. JPMorgan analyst Brian Essex recently described Palantir as having “uniquely profitable hyper-growth fundamentals, with potential for substantial disruptive upside within its primary market segments.”
He also highlighted the accelerating pace of corporate adoption, as businesses look beyond AI experimentation and demand measurable financial returns from their investments.
The next opportunity to see whether that momentum holds comes on Monday, Nov. 2, when Palantir reports its Q3 FY2026 results after the market closes. After a standout Q2 and a substantial upgrade to its full-year outlook, investors will be watching to see whether the latest numbers can give the stock another reason to climb.
About Palantir Stock
Palantir Technologies develops software platforms for intelligence agencies, defense organizations, and commercial enterprises. With a market cap of approximately $472.9 billion, the company offers four principal products, Gotham, Foundry, Apollo, and Artificial Intelligence Platform (AIP), covering everything from data integration and analysis to operational decisions, software deployment, and AI-powered solutions.
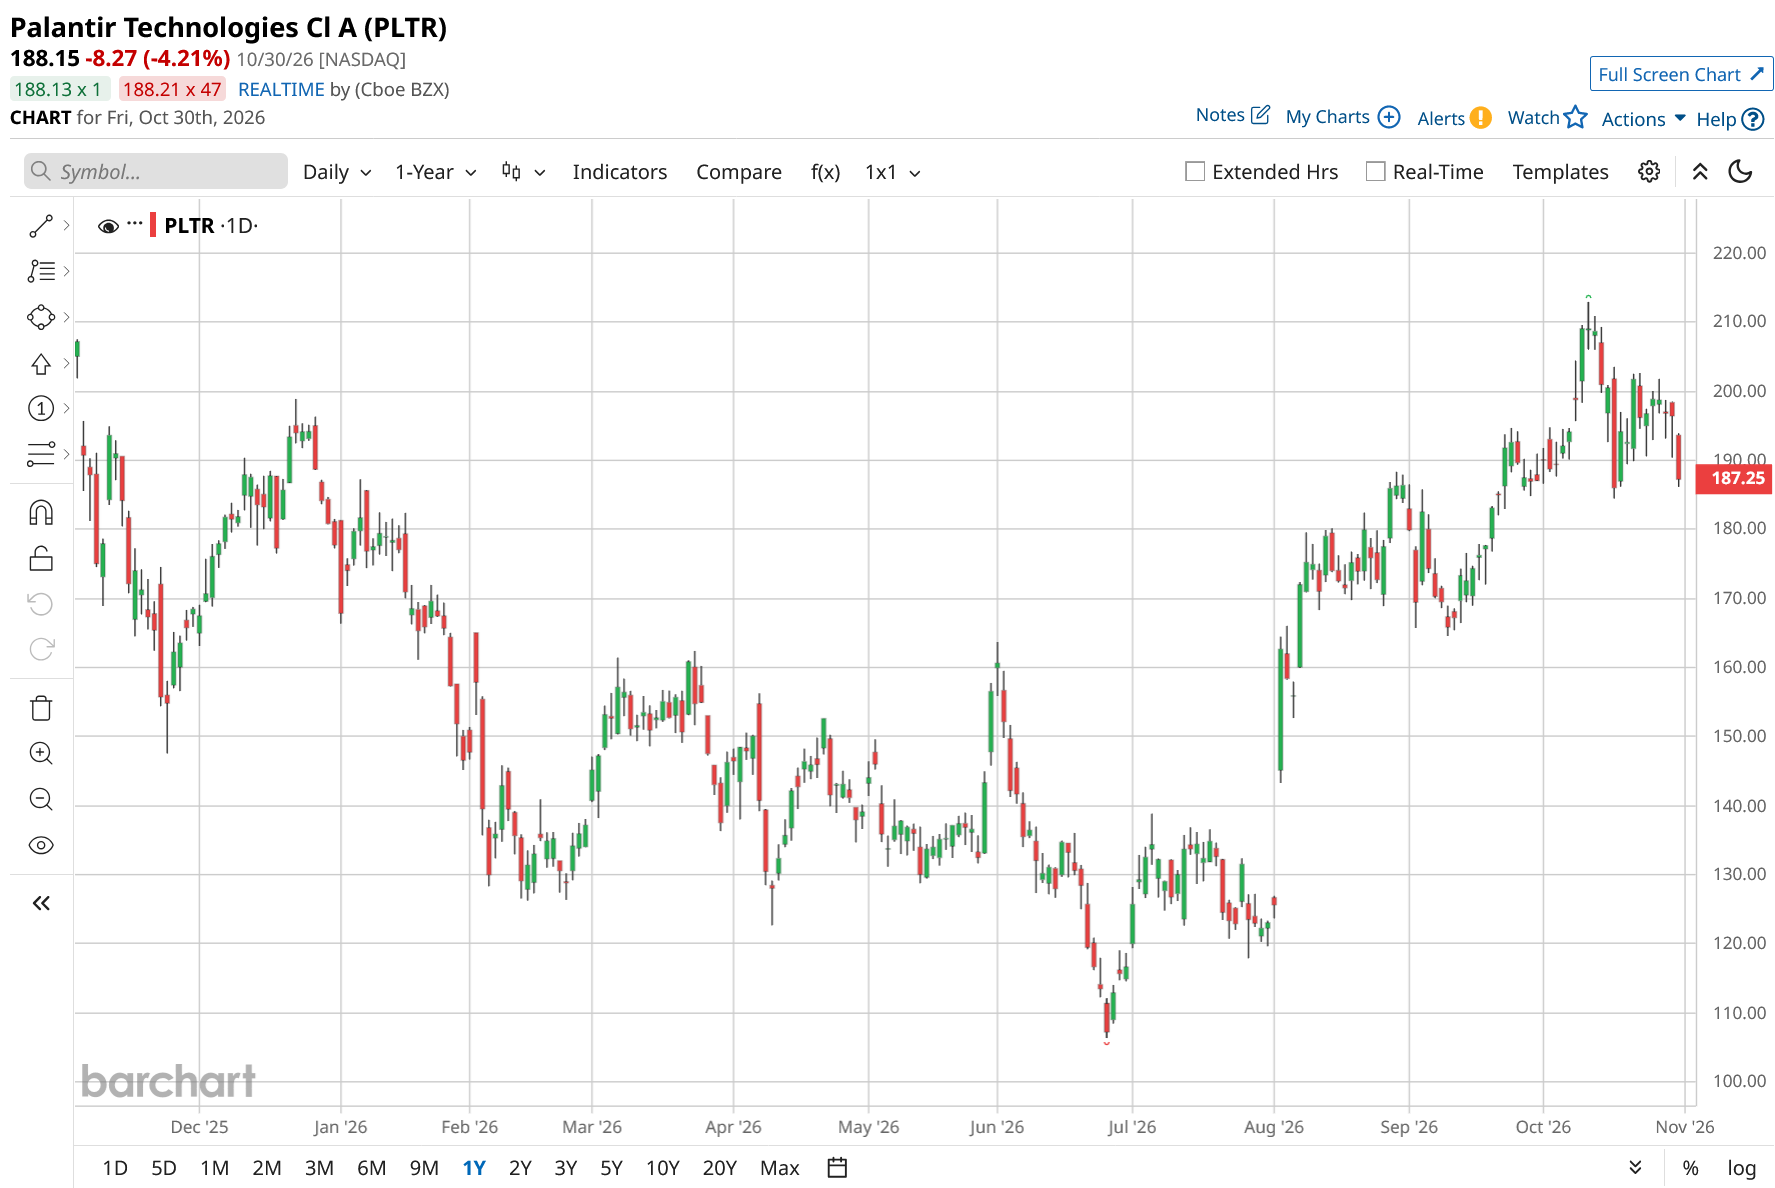
Its stock performance has been rather interesting. Shares of the Aventura, Florida-based technology pioneer have slipped 3% over the past 52 weeks. However, the broader picture looks brighter, with PLTR stock gaining 6% year-to-date (YTD) and surging 54% over the latest three-month period.
The rally has not come cheap. Palantir currently trades at 121.91 times forward adjusted earnings and 57.56 times sales, with both valuation multiples comfortably above industry averages.
Palantir Surpasses Q2 Earnings
On Aug. 3, Palantir released its Q2 FY2026 results, reporting strong growth as rising commercial demand for AI lifted revenue and profitability. The performance also prompted management to raise its full-year outlook. Shares gained 2.1% on the announcement day before climbing another 29.5% in the following trading session.
Revenue surged 92.8% year-over-year (YoY) to $1.94 billion, marking the company's strongest reported growth rate to date. The result also topped analysts' expectations of $1.81 billion, reflecting stronger-than-anticipated demand for Palantir's software.
The U.S. business drove much of this expansion, with revenue rising 115% YoY to $1.57 billion. Within the segment, U.S. commercial revenue jumped 149% to $764 million, highlighting growing adoption of Palantir's Artificial Intelligence Platform (AIP) among businesses bringing AI into their everyday operations.
Government operations remained another source of strength, with U.S. government revenue increasing 90% from the year-ago period. Commercial demand was equally encouraging, as U.S. commercial total contract value bookings reached $2.13 billion, marking a 153% YoY increase.
Profitability improved alongside revenue growth. Net income attributable to common stockholders climbed 225% from the year-ago period to $1.1 billion. Adjusted EPS came in at $0.41, exceeding Wall Street's estimate of $0.35, while adjusted free cash flow increased 115% YoY to $1.22 billion, representing a 63% margin. The adjusted EPS growth percentage was not specified.
Following the strong quarter, management has raised its FY2026 revenue guidance to $8.150 billion–$8.158 billion, implying YoY growth of 82%. U.S. commercial revenue guidance was also increased to more than $3.424 billion, representing expected growth of at least 134%.
The revised outlook also includes adjusted income from operations of $4.889 billion–$4.897 billion and adjusted free cash flow of $4.5 billion–$4.7 billion for FY2026. Meanwhile, for Q3, management expects revenue between $2.160 billion and $2.164 billion, alongside adjusted income from operations of $1.292 billion–$1.296 billion.
Analysts expect earnings growth to remain strong. Q3 FY2026 EPS is projected to increase 83.3% YoY to $0.33. Meanwhile, for FY2026, analysts forecast a 104.7% YoY increase in EPS to $1.29, followed by another 45% rise to $1.87 in FY2027.
What Do Analysts Expect for PLTR Stock?
Among the more bullish voices on Wall Street is JPMorgan's Brian Essex, who has assigned Palantir an “Overweight” rating and established a price target of $262. His stance reflects confidence in the company's ability to capitalize on rising AI adoption and expand its presence across its primary markets.
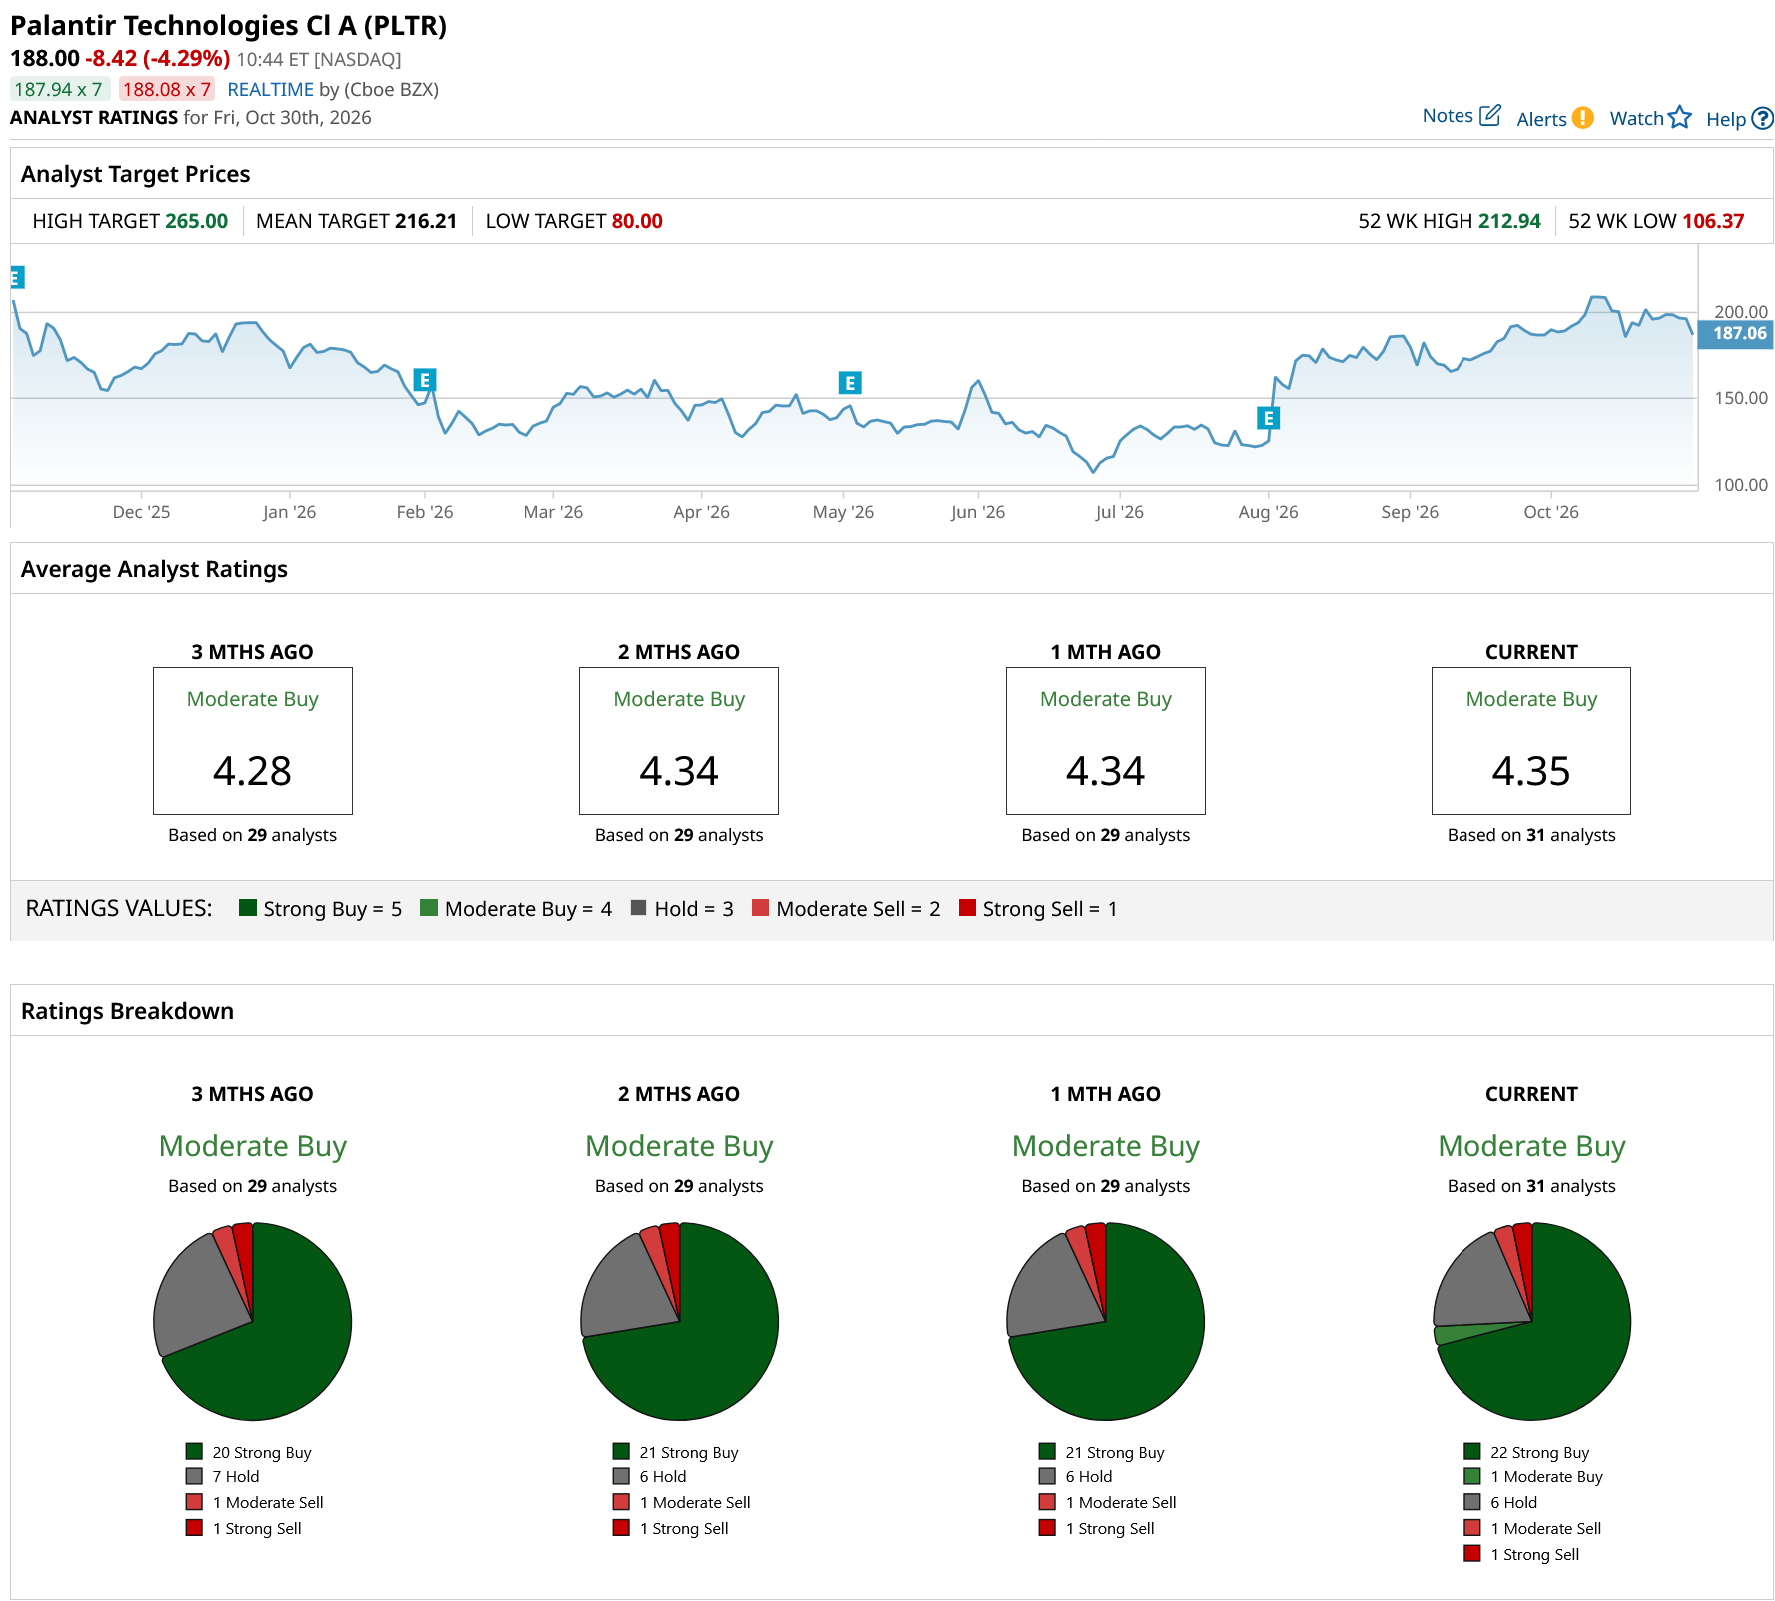
The broader analyst community is also leaning toward the optimistic side, assigning Palantir an overall rating of “Moderate Buy.” Among 31 analysts covering the stock, 22 recommend “Strong Buy,” one assigns “Moderate Buy,” six recommend “Hold,” one has a “Moderate Sell” rating, and one recommends “Strong Sell.”
To that end, the average price target of $216.21 implies a potential upside of 15%. Meanwhile, the Street-high target of $265 points to a gain of 41% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.