
Camtek Stock In Focus Before Earnings Report
- Camtek is approaching its November 4 earnings report, with analysts expecting higher quarterly earnings and revenue compared with the prior year as investors watch how inspection and metrology tools tied to advanced packaging and HBM translate into shipment volume and profitability.
- The key operational question is whether Camtek can convert a record advanced packaging and HBM oriented backlog into consistent high value deliveries that support its margin ambitions while demand from chipmakers and OSATs remains focused on AI and high performance computing workloads.
- We will look at how Camtek's investment narrative is affected by expectations that its advanced packaging backlog starts converting into shipments.
Scan where Camtek fits in the AI hardware build out and compare it with a curated set of 54 AI infrastructure stocks that may also be gearing up for the next wave of demand.
Camtek Investment Narrative Recap
To own Camtek, you need to believe that inspection and metrology tied to advanced packaging and HBM can stay busy enough for that large backlog to turn into steady shipments and healthier margins. The coming earnings update is mainly about proof of execution. If backlog conversion looks orderly, the current operational plan stays largely intact.
The biggest near term catalyst is simple. Investors want to see high value Hawk and Eagle G5 tools shipping on time and at the margin mix management has outlined. The key risk is concentrated exposure to AI and HBM spending. A softer ordering environment from those customers could quickly pressure growth ambitions.
The most relevant recent development is the approaching September quarter report on 4 November, where analysts expect higher earnings and revenue year on year and see a positive setup for a possible beat. That matters because Camtek has been scaling capacity toward well above US$700 million in annual shipments while targeting materially higher profitability.
If the results confirm that advanced packaging and HBM oriented orders, more than US$600 million year to date, are moving cleanly through the factory, it helps support the story around mix shift into Hawk and Eagle G5 and the margin goals above 52% gross and 30% operating. Any stumble in backlog conversion or profitability would quickly refocus attention on the stretched P/S multiple and execution risk.
Camtek Earnings Setup Against Long Term Assumptions
In the short term, the story around Camtek hinges on backlog conversion in advanced packaging and HBM tools. In the background, analyst models are sketching a much bigger company by the end of the decade, and that gap between today's earnings and the 2029 targets frames a lot of the current debate around the stock.
Analysts in the Simply Wall St report are building in 26.1% yearly revenue growth over the next three years, starting from the current cycle, and are pairing that with a sharp step up in profitability assumptions. Profit margins are modeled to move from 7.4% today to 69.3% in three years. This would represent a very large improvement in earnings power if it plays out as expected and would imply a business that turns a much greater share of each inspection and metrology sale into bottom line profit.
On the earnings line, consensus estimates point to US$37.7 million today and US$706.2 million by about 2029, with the more optimistic forecasts going up to US$828.5 million. That implies earnings would need to grow by close to 19x from the current level over the period for the central scenario. This is a steep climb that puts a lot of weight on Camtek turning its AI, HBM and advanced packaging exposure into sustained profit rather than just a short lived upcycle.
Camtek's narrative projects US$1.0b revenue and US$706.2 million earnings by 2029. This assumes 26.1% yearly revenue growth and earnings rising by roughly US$668.5 million from US$37.7 million today.
To tie these assumptions back into the share price, analysts outline that the stock currently trades on a P/E of 160.4x earnings today and would need to compress to 18.6x on the 2029 earnings estimate to justify their price target. That future multiple sits well below the quoted 44.4x P/E for the broader US semiconductor industry in the same report. In practical terms, the scenario relies more on strong earnings expansion than on any rerating uplift.
The same framework assumes shares outstanding increase by about 1.97% a year over the next three years, so part of the projected jump in total earnings also has to offset modest dilution. That is worth keeping in mind when you translate the US$706.2 million profit goal and US$5.89 EPS estimate into your own view on per share value creation.
On the revenue side by 2029, the model that arrives at a US$176.2 analyst consensus target price is built around Camtek reaching US$1.0b in sales, with US$706.2 million of earnings and a P/E of 18.6x, all discounted using a 14.7% to 14.72% rate. The spread between the most optimistic and most cautious targets, from US$200.0 at the top end to US$152.0 at the low end, reflects how sensitive those outcomes are to small changes in margin assumptions, order momentum from AI and HBM customers, and the pace of Hawk and Eagle G5 mix shift.
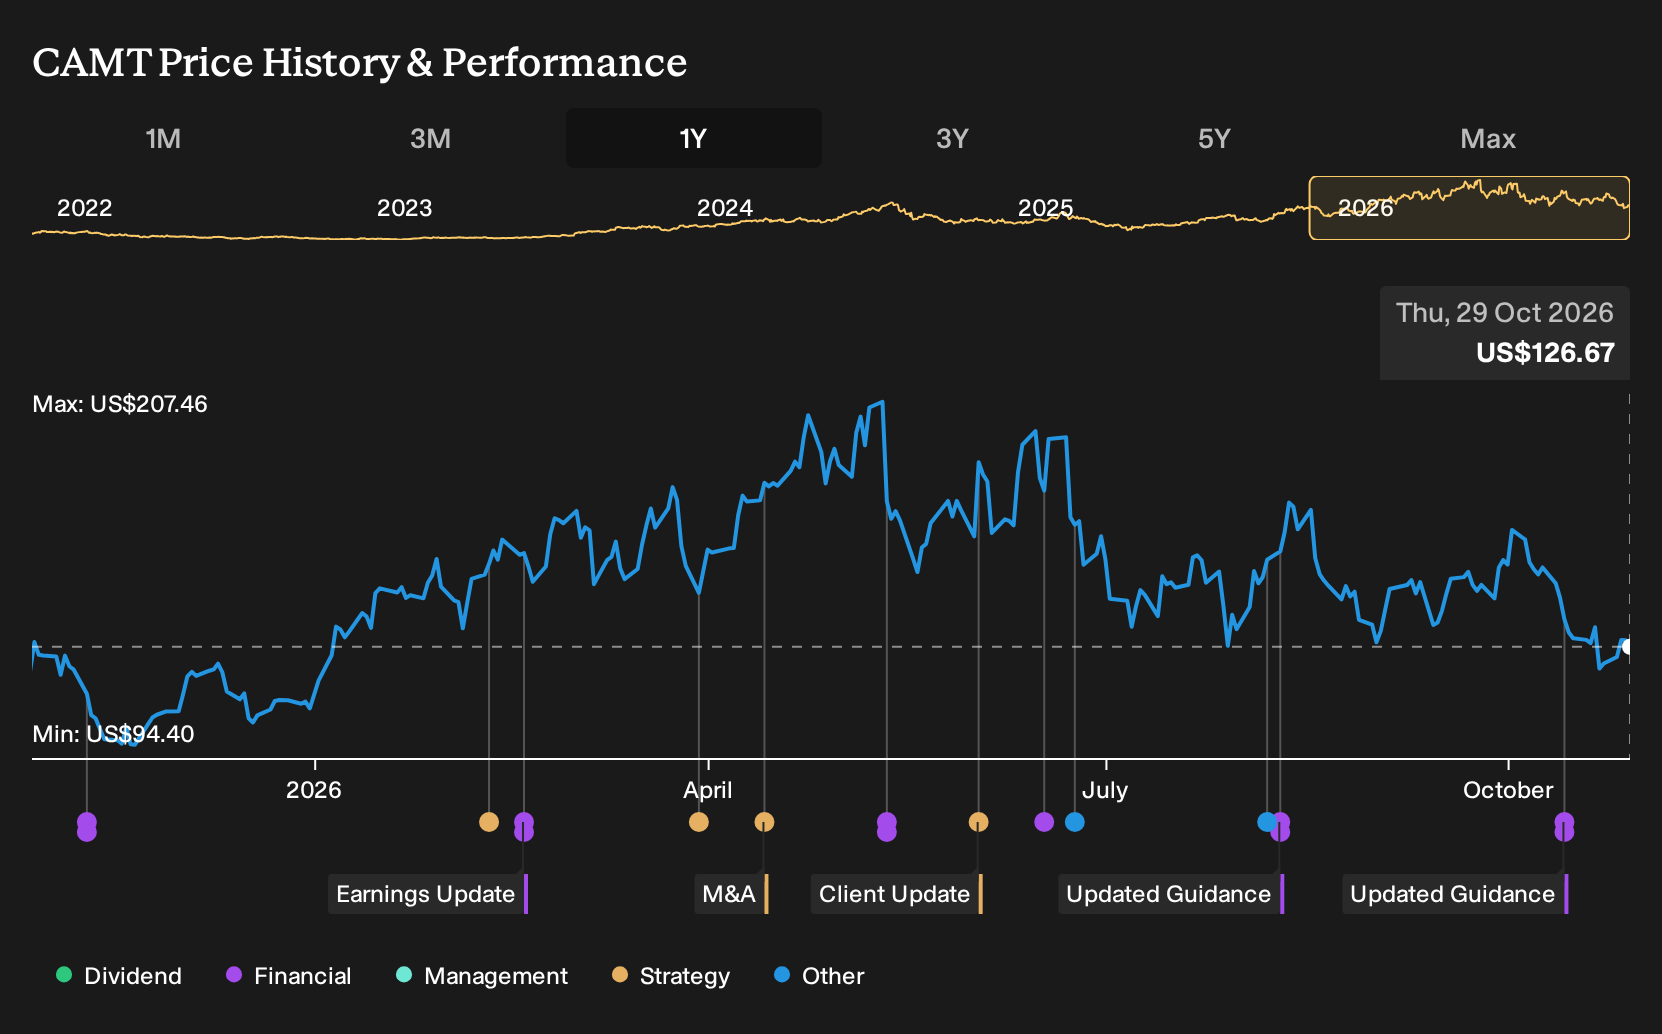
Anchoring all of this to today, the report highlights a current share price of US$129.47 against the US$176.2 consensus target, a gap of 26.5%. For anyone tracking Camtek into the November earnings print, the key question is how much of the long range 2029 earnings story feels supported by actual Hawk and Eagle G5 shipment trends, order visibility with HBM and OSAT customers, and early progress toward the 52.5% to 53% gross margin and 30% to 32% operating margin objectives as capacity lifts above US$700 million of annual output.
Uncover why Camtek's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Camtek leans hard on valuation risk. That more cautious group saw fair value closer to US$152.0, with revenue nearer US$882.9 million and earnings of about US$616.6 million by 2029. You can treat the upcoming November 4 earnings report as a live test of which storyline needs to move.
Explore 4 other Camtek fair value estimates, including one that suggests as much as 53% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Camtek research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Camtek. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Camtek's overall financial health at a glance.
Looking for more investment ideas beyond Camtek?
If the Camtek story has sharpened your thinking and you want to widen your opportunity set, the Simply Wall St Screener can help you quickly filter for other listed businesses that match the traits you care about most, from quality balance sheets to income potential.
- If capital preservation sits high on your list, start with a group of companies that our models flag as more resilient by risk score through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a sensible price, scan a curated pool of strong cash generators trading below our assessed value using the 30 high quality undervalued stocks.
- If reliability of earnings and payouts matters to you, review companies that pair higher income yields with sturdier financial profiles via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com