
How Investors Are Reacting To Eagle Materials Stock As Earnings Expectations Fall
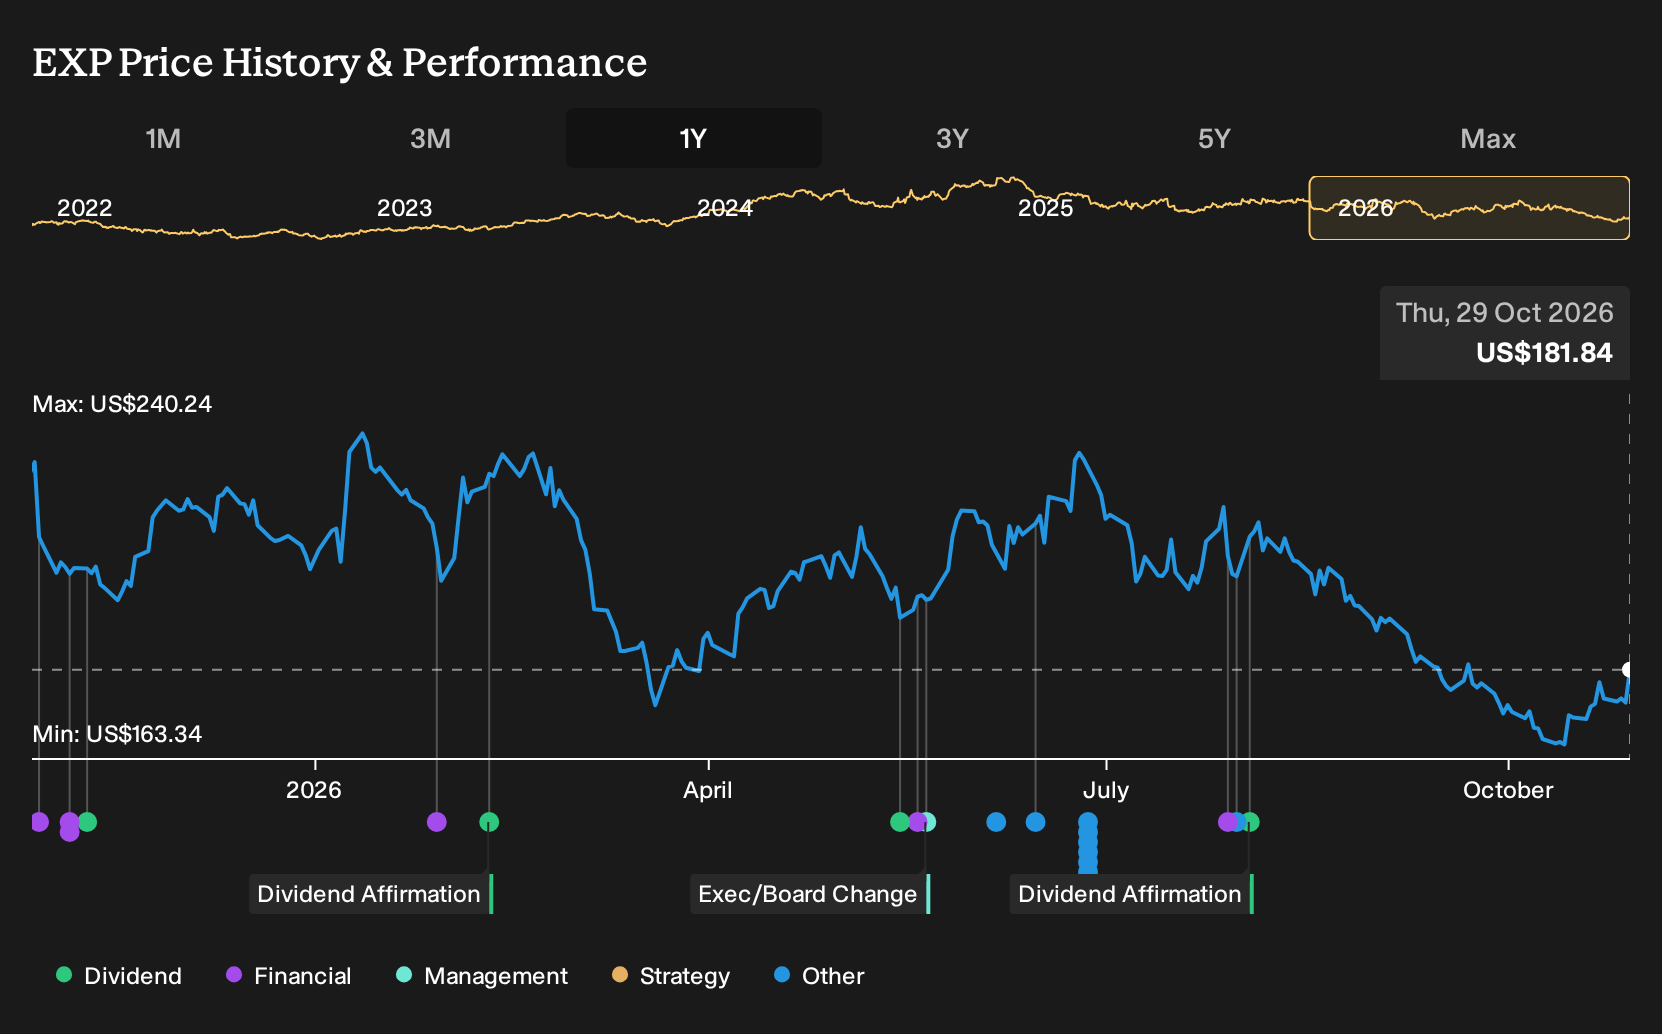
- Eagle Materials recently faced expectations of lower earnings and reduced revenue for the quarter ended September 2026, with analysts highlighting a negative Earnings ESP of 8.91% ahead of the November 4 report.
- The key issue is concern that weaker quarterly profit and sales could pressure Eagle Materials at a time when it is funding large plant modernization projects intended to reduce costs over time.
- We will now look at how Eagle Materials' investment narrative could be affected by the anticipated earnings decline flagged ahead of results.
Scan beyond Eagle Materials for building and construction peers where sentiment and earnings expectations look very different by reviewing our hand picked 30 resilient stocks with low risk scores as a comparison set.
Eagle Materials Investment Narrative Recap
To own Eagle Materials, you need to believe that heavy construction demand and multi year infrastructure projects can keep cement and aggregates volumes healthy while the Light Materials softness eventually stabilizes. The near term concern is that the expected earnings and revenue decline for the September 2026 quarter lands just as spending on major plant upgrades is peaking.
The key short term swing factor is execution at the Mountain Cement and Duke Wallboard projects, alongside how freight and other input costs trend. Earnings pressure this quarter does not automatically change that path, but it can tighten headroom. The biggest risk is that higher costs and weak wallboard volumes persist while modernization fails to deliver the targeted savings.
The most relevant development tied to this setup is Eagle Materials pushing ahead with the Mountain Cement and Duke Wallboard modernization programs, which together are guiding to US$490m to US$525m of capital expenditure in fiscal 2027. These upgrades are intended to raise capacity and improve efficiency, so the timing against softer earnings matters.
For you as a shareholder, the question is how comfortable you are with lower near term profitability while these plants move from roughly 60% and 30% completion toward commissioning. Analyst expectations around cost reductions and returns sit in the background, but the real test will come from actual unit costs, cement pricing, and wallboard volumes once the projects are fully online.
Eagle Materials Consensus Assumptions In Focus
Analysts are effectively asking investors to think about Eagle Materials as a slow and steady compounding story rather than a rapid growth play. The current models incorporate annual revenue expansion of 2.3% over the next three years, with profitability edging down from a 17.3% margin today toward 16.8% as the modernization cycle and softer Light Materials trends are reflected in the numbers.
On earnings, the consensus view points to profit of US$417.9 million by 2029 compared with US$402.6 million today. That is an increase of about US$15 million over the period, which is modest relative to the scale of the current capex program. In other words, the Street is not assuming a step change in profitability yet, even as the Mountain Cement and Duke Wallboard projects move toward completion.
The forecasts also assume Eagle Materials continues to retire stock at a healthy pace, with shares outstanding projected to fall 4.33% each year for the next three years. A shrinking share count can lift earnings per share even if total profit only edges higher, which is why the EPS estimate for 2029 sits at US$15.47. For investors, the key judgment is whether that pace of buybacks and the modestly lower margin profile appear realistic given the capital spending needs and the current operating backdrop.
Eagle Materials' narrative reflects US$2.5 billion in revenue and US$417.9 million in earnings by 2029, based on 2.3% yearly revenue growth and an earnings increase of about US$15 million from US$402.6 million today.
Uncover how Eagle Materials' fair value indicates a 8% potential upside to its current price.
Exploring Other Perspectives
Retail investors in the Simply Wall St Community put Eagle Materials’ fair value anywhere between US$100.36 and about US$336 across four separate assessments, so opinions already span a wide price spectrum. With earnings expected to decline year on year and a November 4 report approaching, you should weigh these crowd forecasts against the risks around Light Materials, modernization payoffs, and cement pricing. Investor opinions can differ sharply, so explore several viewpoints before deciding how Eagle Materials fits your portfolio.
Explore 3 other Eagle Materials fair value estimates, including one that suggests as much as 45% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eagle Materials research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eagle Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eagle Materials' overall financial health at a glance.
Looking for more investment ideas beyond Eagle Materials?
If you want to stress test your Eagle Materials thesis or simply widen your opportunity set, the Simply Wall St Screener can help you quickly narrow the market to companies that fit your risk tolerance and return goals.
- If you are hunting for quality at a reasonable price, use our screener focused on potential mispricing and scan through 30 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, filter for stronger finances and seek out companies with healthier leverage and liquidity profiles through the list of solid balance sheet and fundamentals (23 results).
- If you are comfortable going off the beaten path, cast a wider net across lesser known opportunities with the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com