
How Quarterly Revenue Growth At OPmobility Shares Has Changed Its Investment Story
- OPmobility reported consolidated revenue of €2,437 million for the third quarter of 2026 and €7,639 million for the first nine months, compared with €2,362 million and €7,695 million respectively a year earlier.
- The mixed picture of higher quarterly turnover alongside slightly lower year to date sales highlights how short term order timing and model cycles can skew headline revenue without necessarily changing the longer term demand story.
- We now examine how OPmobility's investment narrative is shaped by this third quarter revenue figure and the nine month trend.
Compare OPmobility's mixed top line trend with other auto suppliers by scanning our hand picked list of list of solid balance sheet and fundamentals (203 results) to find potential alternatives and complements for your watchlist.
OPmobility Investment Narrative Recap
To own OPmobility, you need to believe the group can keep winning content on future vehicle programs while holding its cost discipline as the mix shifts toward electrified platforms. The latest sales release points to fairly steady demand in the quarter and a flat nine month picture, so the short term revenue signal looks modest rather than transformational.
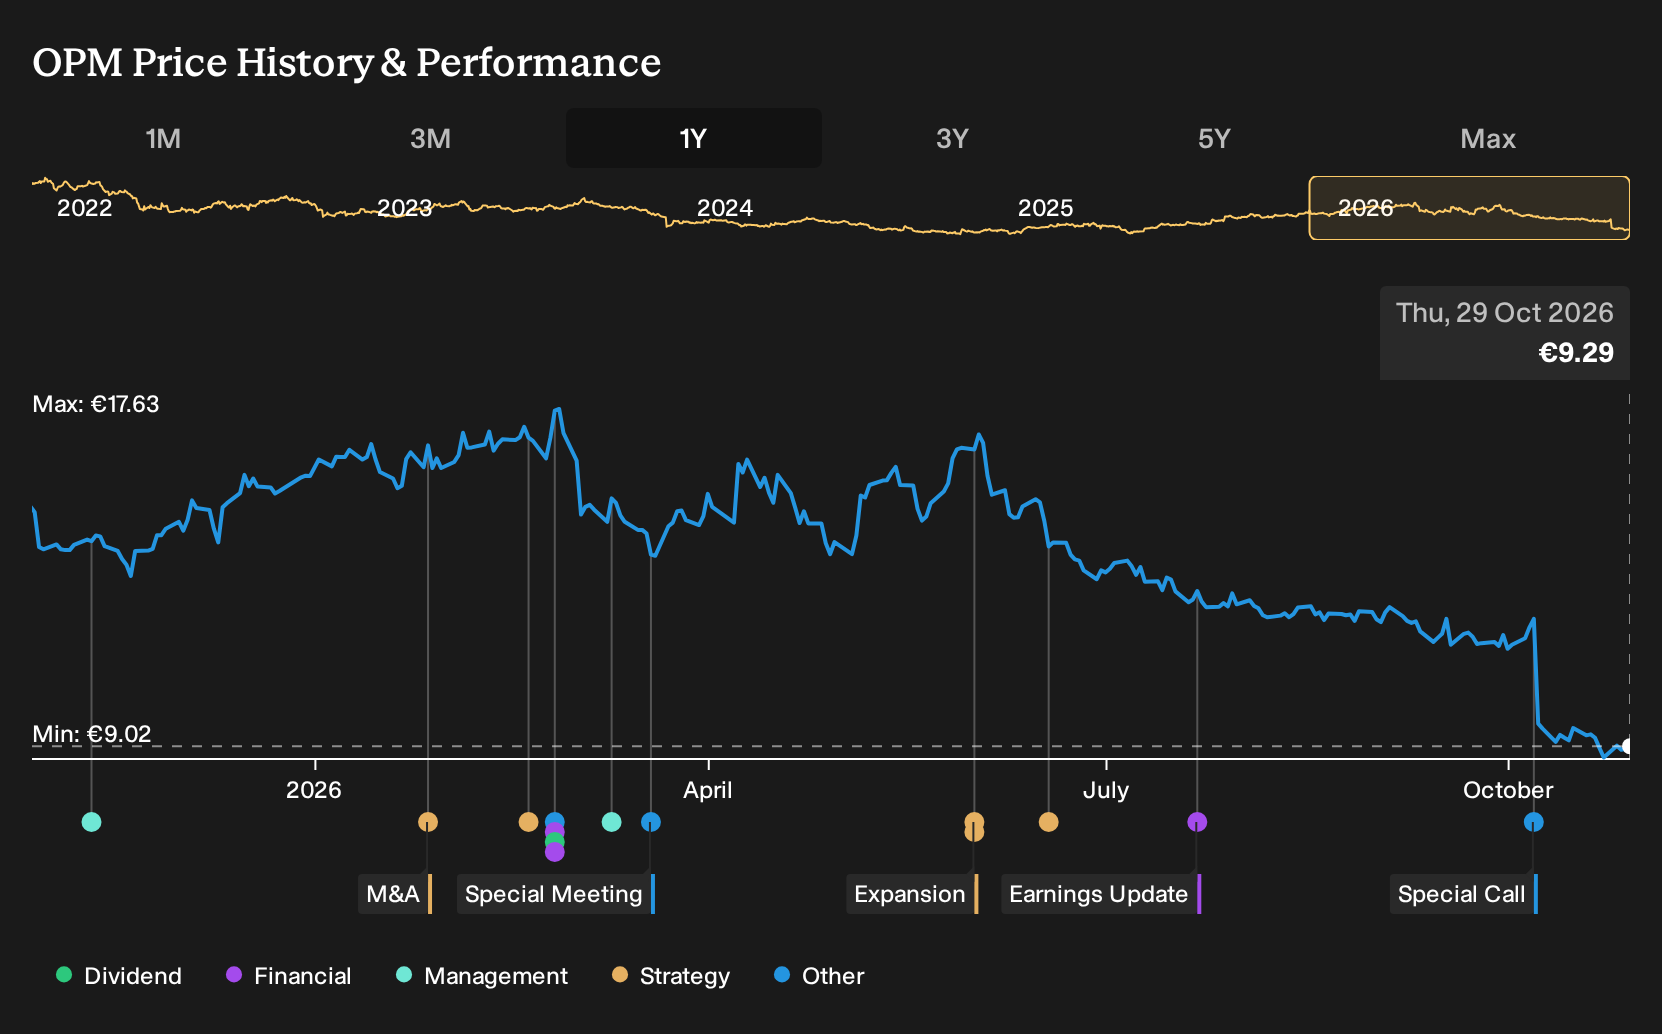
The near term catalyst still hinges on execution in Exterior & Lighting and Powertrain as OEMs adjust production schedules and trim complexity. The biggest current risk remains leverage combined with a volatile share price and an uneven dividend record, especially if auto build rates soften or order books prove less resilient than hoped.
With no fresh announcements beyond the third quarter and nine month trading statement, that disclosure becomes the main reference point for your near term checklist. The slight third quarter top line improvement against a marginal year to date dip frames a business holding its ground while end markets move unevenly by region and segment.
For catalysts, the key question is whether this revenue path can support margin progress, cash generation and gradual balance sheet improvement without relying on aggressive volume assumptions. In contrast, the trading update also reminds you that OPmobility operates in a capital intensive cycle where high debt, potential production declines and changing EV content per vehicle remain central execution risks.
OPmobility's current earnings sit at €197.0 million, with analysts projecting revenues of €10.7 billion and earnings of €252.4 million by 2029. That path implies 2.1% yearly revenue growth and an earnings increase of about €55 million from today's level.
Uncover why OPmobility's fair value indicates a 46% potential upside to its current price before the discount starts to close.
Exploring Other Perspectives
One alternate view on OPmobility focuses less on revenue momentum and more on margin pressure. The most cautious analysts were looking for only 1.3% yearly top line growth and earnings of about €199.8 million by 2029 before this trading update. That is far below the €252.4 million consensus path. Use this new sales data as a trigger to compare those contrasting stories and decide which set of assumptions feels closer to your own expectations.
Explore another OPmobility fair value estimate, including one that suggests it could be worth just €13.58.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OPmobility research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OPmobility. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OPmobility's overall financial health at a glance.
Looking For More Investment Ideas Beyond OPmobility?
Once you have a view on OPmobility, it can help to cross check that thinking against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience and balance sheet strength, scan our curated list of solid balance sheet and fundamentals (203 results) and see which businesses match your comfort level on debt and cash flow.
- If you are hunting for potential mispricing opportunities, review the 200 high quality undervalued stocks and compare how their fundamentals stack up against what you see at OPmobility.
- Income focused investors who prioritise cash returns can survey a focused 222 dividend fortresses to spot companies where yield and payout history may better fit their portfolio goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com