
Sumitomo Bakelite (TSE:4203) Could Be 34% Below Fair Value On Dividend Review
Sumitomo Bakelite (TSE:4203) has called an Oct. 30, 2026 board meeting to review consolidated financial forecasts and reassess both interim and full year dividend plans, a key signal for earnings expectations and shareholder payouts.
Recent trading has been choppy. The share price is down 3.8% on the day and roughly 3.6% over the past month. However, it has gained 24.5% over 90 days, and the 1-year total shareholder return of 60.8% points to momentum that has been strong over a longer stretch as investors reassess Sumitomo Bakelite ahead of the dividend and forecast review.
Spot similar setups by scanning our hand picked 14 high quality undervalued stocks, which, like Sumitomo Bakelite around this dividend review, pair solid business foundations with potentially mispriced expectations.After a 60.8% 1 year return and a recent pullback into this dividend and forecast review, the key question with Sumitomo Bakelite is straightforward: step in now, or wait for a potentially cleaner entry that the valuation work might highlight later.
Preferred P/E of 22.6x for Sumitomo Bakelite: Is It Justified?
On the valuation side, Sumitomo Bakelite changes hands at a P/E of 22.6x while our estimate of a fair P/E sits lower at 18.2x. This points to investors paying a premium for each unit of earnings at the current ¥8,109 share price.
The P/E ratio compares the current share price to earnings per share. For a business like Sumitomo Bakelite, which operates across semiconductor materials, high performance plastics, and quality of life products, that metric shows how much the market is willing to pay today for its profit stream.
When the actual P/E of 22.6x sits meaningfully above both the Chemicals industry average of 12.4x and the peer group at 17.2x, it indicates that expectations embedded in the stock are richer than what a more neutral multiple might suggest. Compared with the estimated fair P/E of 18.2x, the gap appears even clearer and highlights a valuation level the market could move towards if sentiment cools or earnings do not keep pace.
Compared to many Chemicals peers pricing their earnings at closer to low to mid teens multiples, Sumitomo Bakelite carries a significantly higher tag, and that contrast is notable when the fair P/E estimate also sits well below the current 22.6x level.
Explore the SWS fair ratio for Sumitomo Bakelite.
Result: Price-to-earnings of 22.6x (OVERVALUED)
Still, the Sumitomo Bakelite story can be knocked off course if earnings per share disappoint compared with the rich 22.6x P/E, or if dividend guidance tightens unexpectedly.
Find out about the key risks to this Sumitomo Bakelite narrative.
Another View: What The SWS DCF Model Says About Sumitomo Bakelite
The P/E looks rich for Sumitomo Bakelite, yet the SWS DCF model paints a different picture. At ¥8,109, the shares sit below an estimated future cash flow value of ¥12,211.86, which points to the stock trading at a discount on this framework.
For investors weighing earnings multiples against cash flow based estimates, the gap between the 22.6x P/E and a DCF that signals undervaluation raises a simple question: Which lens do you trust more when board decisions on dividends and forecasts land?
Look into how the SWS DCF model arrives at its fair value.
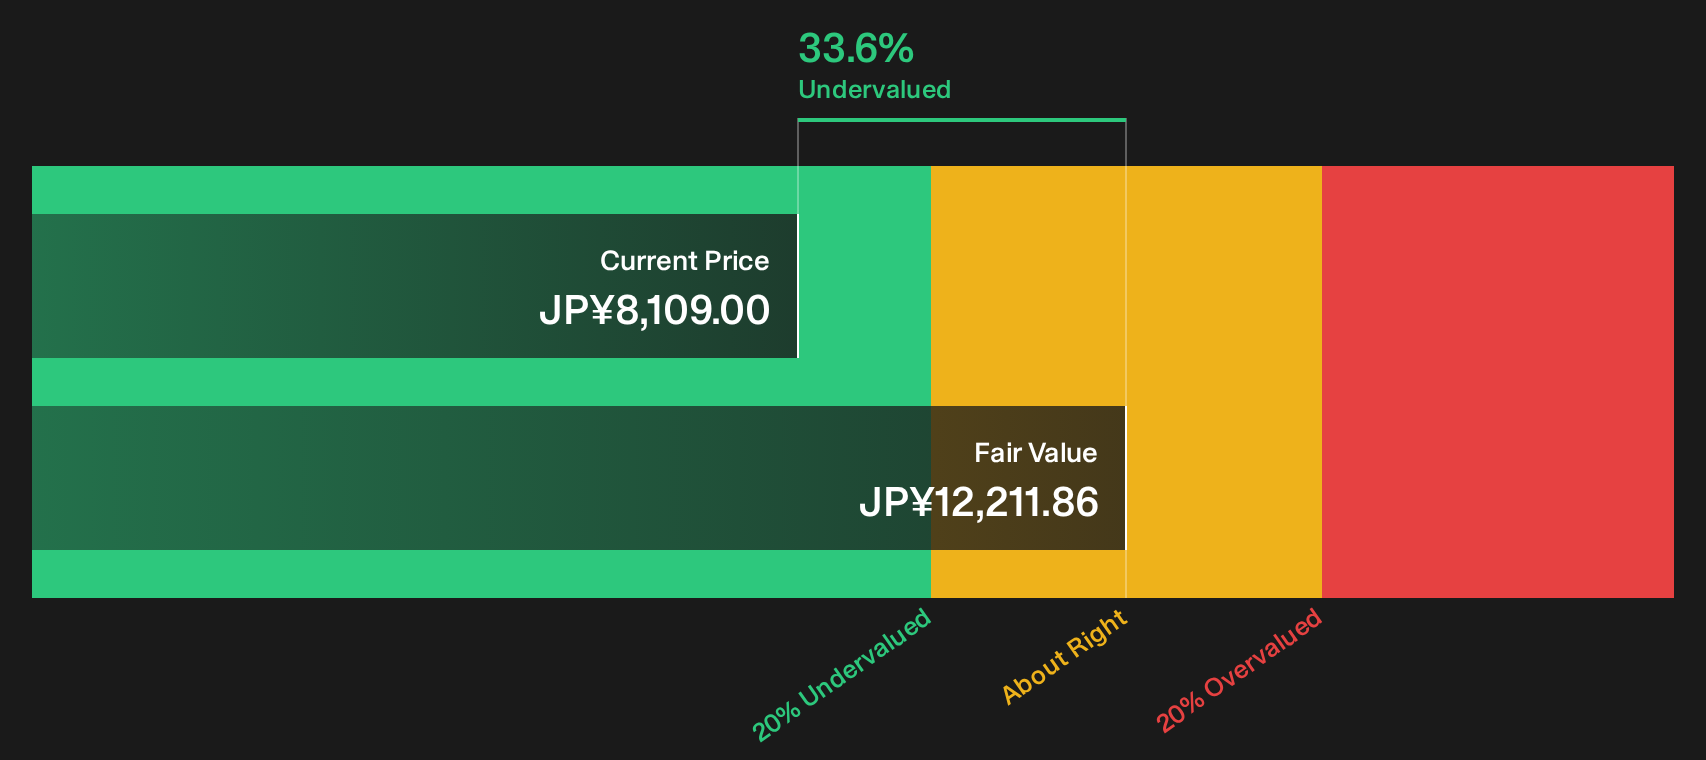
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sumitomo Bakelite for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or real opportunity for Sumitomo Bakelite as the board heads into this forecast and dividend review window. Act quickly by checking both sides of the story and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Sumitomo Bakelite?
If you like how Sumitomo Bakelite lines up on valuation and cash flow, do not stop here. Broaden your watchlist now before the next move passes you.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (22 results) that filters for durable finances and stronger fundamentals when conditions get tougher.
- Hunt for potential mispricing with a 71 high quality undiscovered gems that focuses on quality fundamentals before wider attention arrives.
- Prioritise capital preservation through a 24 resilient stocks with low risk scores that concentrates on lower risk scores and steadier business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com