
Duolingo (DUOL) Following Lawsuits And Guidance Cuts Looks Close To Fair Value
Class action lawsuits against Duolingo (DUOL) and its executives, tied to alleged misleading statements on user growth and AI driven content, have pushed this language learning stock into sharper focus for investors.
Recent trading shows that Duolingo shares have been under pressure, with the stock delivering a year to date share price return of down 22.72% and a 1 year total shareholder return of down 49.60%. Lawsuits, guidance cuts and a CFO exit are reshaping how investors think about its risk profile.
Broaden your watchlist beyond Duolingo by scanning a curated 30 resilient stocks with low risk scores that some investors may prefer when legal and execution risks feel front and center.
Duolingo’s slide raises a simple tension. Are investors now pricing in deeper concerns about user quality and monetization, or has sentiment swung past what the current business performance suggests on valuation?
Most Popular Narrative: 2% Overvalued
On Simply Wall St's most followed narrative, Duolingo's fair value sits at $134.29 compared with a last close of $136.39, so the thesis leans on how users, AI features and new subjects might justify that small premium.
Continued investment in and expansion of adjacent educational categories such as Math, Music and Chess, with chess already reaching about 7 million daily active users and growing faster than languages, extends Duolingo’s reach into new learner segments and can add incremental revenue streams over time.
Experiments with new monetization formats, including an ad supported Super Lite tier at roughly half the price of Super and efforts to improve ad sales quality, aim to convert users who are less likely to pay for the full subscription and to raise ad ARPU, which can support bookings, revenue growth and earnings over time even as some paywall friction is reduced.
See why 173 investors see Duolingo as 2% overvalued.
Result: Fair Value of $134.29 (OVERVALUED)
Still, if daily user momentum in key markets stalls or China related regulatory hurdles bite harder than expected, the current Duolingo narrative could unravel quickly.
Find out about the key risks to this Duolingo narrative.
Another View: DCF Points To A Very Different Fair Value
While the most followed Duolingo narrative pegs fair value near $134 at a small premium to the last close, the Simply Wall St DCF model paints a very different picture. On that framework, Duolingo at $136.39 is trading at a 54.3% discount to an estimated future cash flow value of $298.70, which frames the current weakness as a potential mispricing rather than confirmation of a broken story. The gap between these two lenses raises a simple question for you as an investor: which set of assumptions feels more realistic for Duolingo’s cash generation over time?
Our Look into how the SWS DCF model arrives at its fair value.
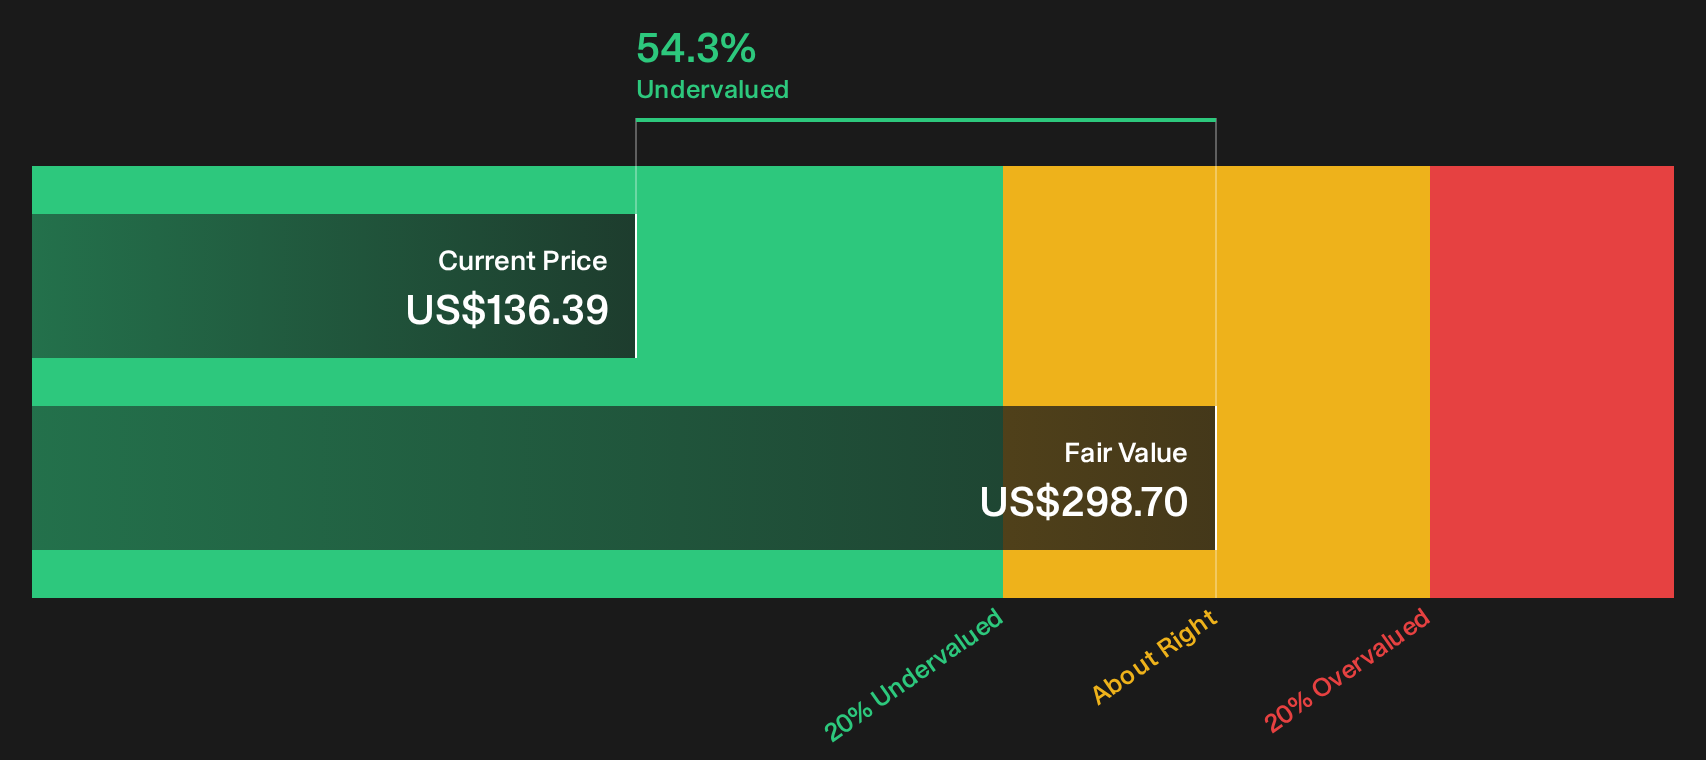
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duolingo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Duolingo has clearly turned more cautious, so act while the information is fresh and stress test the story against your own expectations by weighing the 2 key rewards and 2 important warning signs.
Looking for more Duolingo sized opportunities?
If the Duolingo story has you reassessing risk and reward, use this moment to refresh your watchlist with fresher, differentiated ideas that match your own criteria.
- Target resilience first and stress test your current holdings against a list of solid balance sheet and fundamentals (23 results), which focuses on balance strength and fundamental stability.
- Hunt for value and compare Duolingo with a 18 high quality undiscovered gems that highlights quality businesses many investors may still be overlooking.
- Shift your focus to cash returns and benchmark your ideas against a 7 dividend fortresses that screens for higher yielding payout streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com