
MetroCity Bankshares (MCBS) Just Gave Investors Something To Parse
Why MetroCity Bankshares' latest results matter for investors
MetroCity Bankshares (MCBS) just put fresh numbers on the table for the third quarter and the first nine months of 2026, giving you new data on the bank's profitability and lending engine.
For the September quarter, MetroCity Bankshares reported net interest income of US$43.56 million compared with US$31.79 million a year earlier, while net income came in at US$24.3 million versus US$17.27 million. Over the first nine months of 2026, net interest income was US$132.09 million compared with US$94.52 million for the same period in 2025, and net income reached US$68.74 million compared with US$50.39 million.
Recent trading suggests that investors are responding to the MetroCity Bankshares story with growing confidence. The share price is up 4.74% over the past month and has a 37.15% year-to-date share price return. In addition, the 1-year total shareholder return of 44.66% and 3-year total shareholder return of 88.33% point to momentum that predates the latest earnings and the October dividend increase.
Scan how MetroCity Bankshares fits alongside other potential breakout opportunities in our hand picked list of 30 high quality undervalued stocks.
MetroCity Bankshares now trades at a meaningful discount to both intrinsic value estimates and analyst targets after a strong run. Is that the market flashing a warning, or is it handing you a valuation gap to inspect more closely?
Price-to-earnings of 11.9x: Is MetroCity Bankshares' premium justified?
MetroCity Bankshares changes hands at a P/E of 11.9x, which is slightly richer than both the US Banks industry average of 11.4x and the peer group on 11.7x. The question for you is whether that modest premium lines up with the fundamentals on show.
The P/E ratio compares what you pay for each dollar of earnings, so for a lender like MetroCity Bankshares it effectively reflects how much confidence the market has in the durability of its profit stream and loan book. A higher multiple can signal that investors are comfortable paying more for each dollar of net income if they see those profits as relatively dependable.
Here, the stock trades not only above the broader industry P/E, but also above an estimated fair P/E of 10.3x. That suggests the current price builds in stronger expectations than both the sector and the level that regression analysis points to as more reasonable. This gives you a clear reference point if you are weighing whether the current earnings profile justifies paying a premium.
Explore the SWS fair ratio for MetroCity Bankshares.
Result: Price-to-earnings of 11.9x (OVERVALUED)
Still, tighter credit conditions or a reversal in recent share price gains could quickly change how the market treats the current valuation premium of MetroCity Bankshares.
Find out about the key risks to this MetroCity Bankshares narrative.
Another view on MetroCity Bankshares' value
The P/E workup presents MetroCity Bankshares as slightly expensive, while the SWS DCF model indicates a different perspective. On that framework, the stock at $36.03 sits about 35.6% below an estimated future cash flow value of $55.91, which suggests a very different risk reward profile. This raises the question of which signal to prioritize when the market presents such a divided picture.
Look into how the SWS DCF model arrives at its fair value.
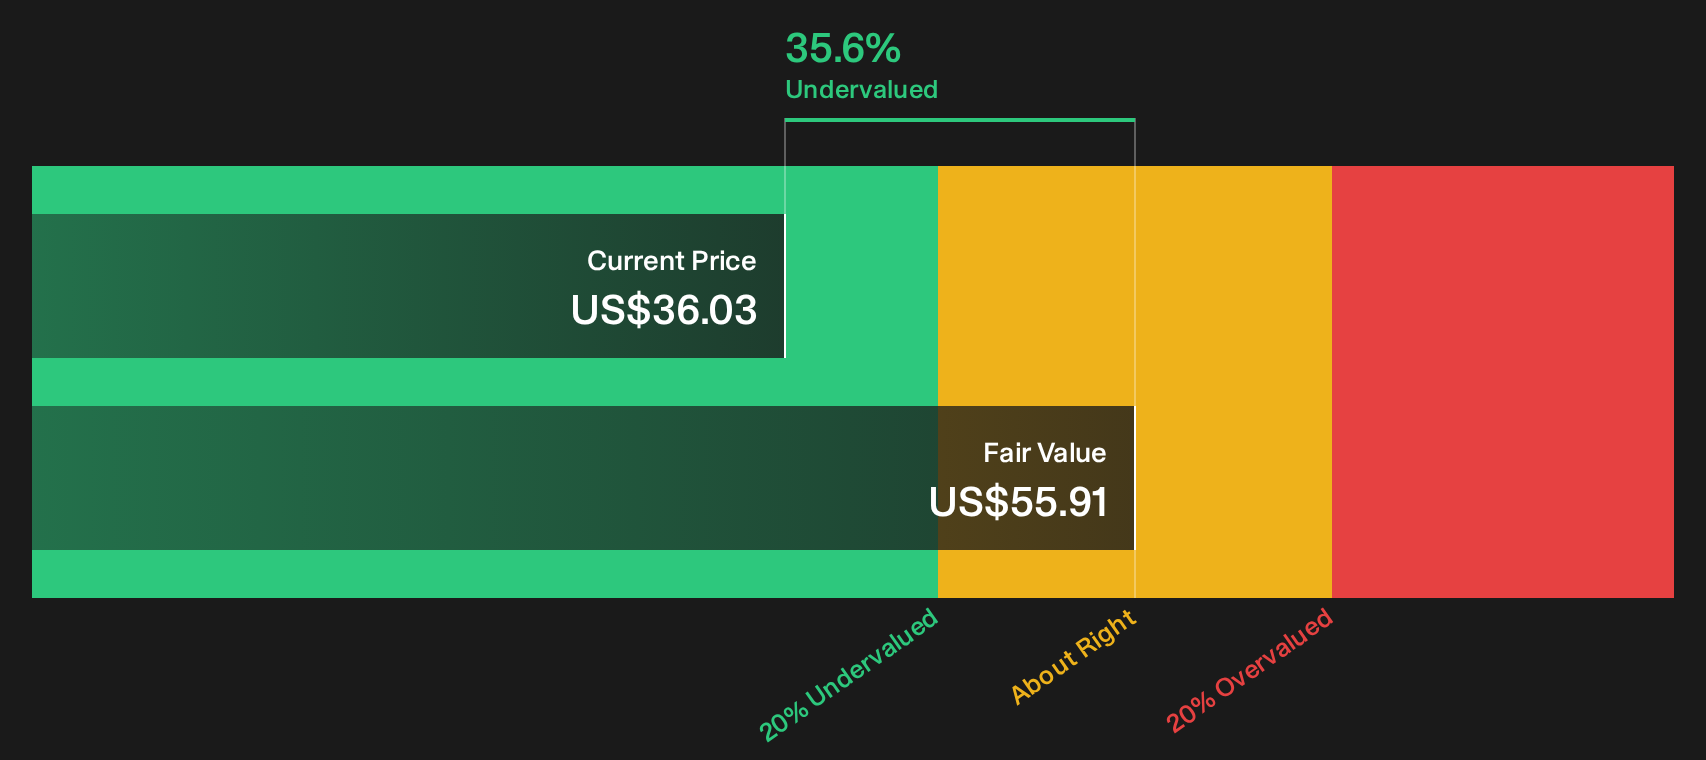
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MetroCity Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on MetroCity Bankshares can feel exciting or unsettling, so use that energy to test the numbers yourself and pressure check the story. To see why some investors are optimistic about specific strengths, review the 3 key rewards
Hunting for more ideas beyond MetroCity Bankshares?
If MetroCity Bankshares has you thinking more broadly about opportunities, do not stop with just one ticker. Use that curiosity to scan a wider field of ideas.
- Spot potential mispricings early and review a curated 30 high quality undervalued stocks that align with stronger fundamentals and more conservative expectations.
- Strengthen your income stream by checking a focused set of 7 dividend fortresses built around higher yields and resilient payout histories.
- Prioritise resilience first and sift through a targeted 30 resilient stocks with low risk scores where balance sheets and risk scores take centre stage before price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com