
Why Navitas Semiconductor Stock Is In Focus After UHV Power Module Launch
- Navitas Semiconductor recently introduced the G4H08MT23GB4 ultra high voltage 2,300 V SiC full bridge module family, targeting solid state transformers, grid scale storage, solar inverters, EV megawatt charging, and AI data center power infrastructure with a focus on efficiency, power density, and reliability.
- The new modules add aluminum nitride AMB substrates, epoxy resin potting, high current press fit pins, optional pre applied TIM, and AEC Plus reliability testing, which together speak directly to demanding workloads in AI racks and utility scale energy systems.
- This launch may influence how investors evaluate Navitas Semiconductor's role in ultra high voltage SiC solutions for AI infrastructure.
Scan beyond Navitas Semiconductor and line up other power plays in AI infrastructure by reviewing the curated 54 AI infrastructure stocks that is now shaping data center and grid buildouts.
Navitas Semiconductor Investment Narrative Recap
To own Navitas Semiconductor, you need to believe its GaN and SiC portfolio converts a large design win backlog into meaningful revenue while the firm is still loss making and cutting costs. The ultra high voltage launch fits that belief but does not replace the near term test. The upcoming November 3 earnings report remains the key short term catalyst as the market watches revenue mix, margin progress, and AI data center traction.
The biggest operational risk is that softness in EV, solar, and industrial markets persists, keeping utilization and gross margins under pressure while cost cuts weigh on R&D. Investors also have to accept dilution over the past year and a volatile share price. If revenue in pressured segments stays weak, the path toward better cash burn and margin improvement gets harder, regardless of product launches.
The UHV SiC module family launch is the announcement to focus on here because it lands directly in grid tied infrastructure for AI data centers. It extends Navitas Semiconductor's 2,300 V and 3,300 V SiC line using the SiCPAK form factor and the GeneSiC Trench Assisted Planar architecture, and adds construction upgrades such as aluminum nitride AMB substrates, epoxy potting, high current pins, and optional pre applied TIM.
For you as a shareholder, the relevance is simple. The firm already has a large design win backlog and a pipeline in data centers and EVs, and this product targets many of those same end markets, including AI racks, grid storage, solar, and megawatt charging. Execution risk sits in turning samples and qualifications, including AEC Plus testing, into stable, higher margin volume shipments before ongoing market softness, workforce reductions, and acquisition integrations slow the operational ramp.
Navitas Semiconductor's current analyst playbook points to revenues of $143.2 million and earnings of $24.0 million by 2029, based on an assumed 52.3% yearly revenue growth rate and a shift in earnings from a loss of $133.9 million today to a profit of $24.0 million. This represents an earnings change of about $157.9 million over that period.
Uncover why Navitas Semiconductor's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
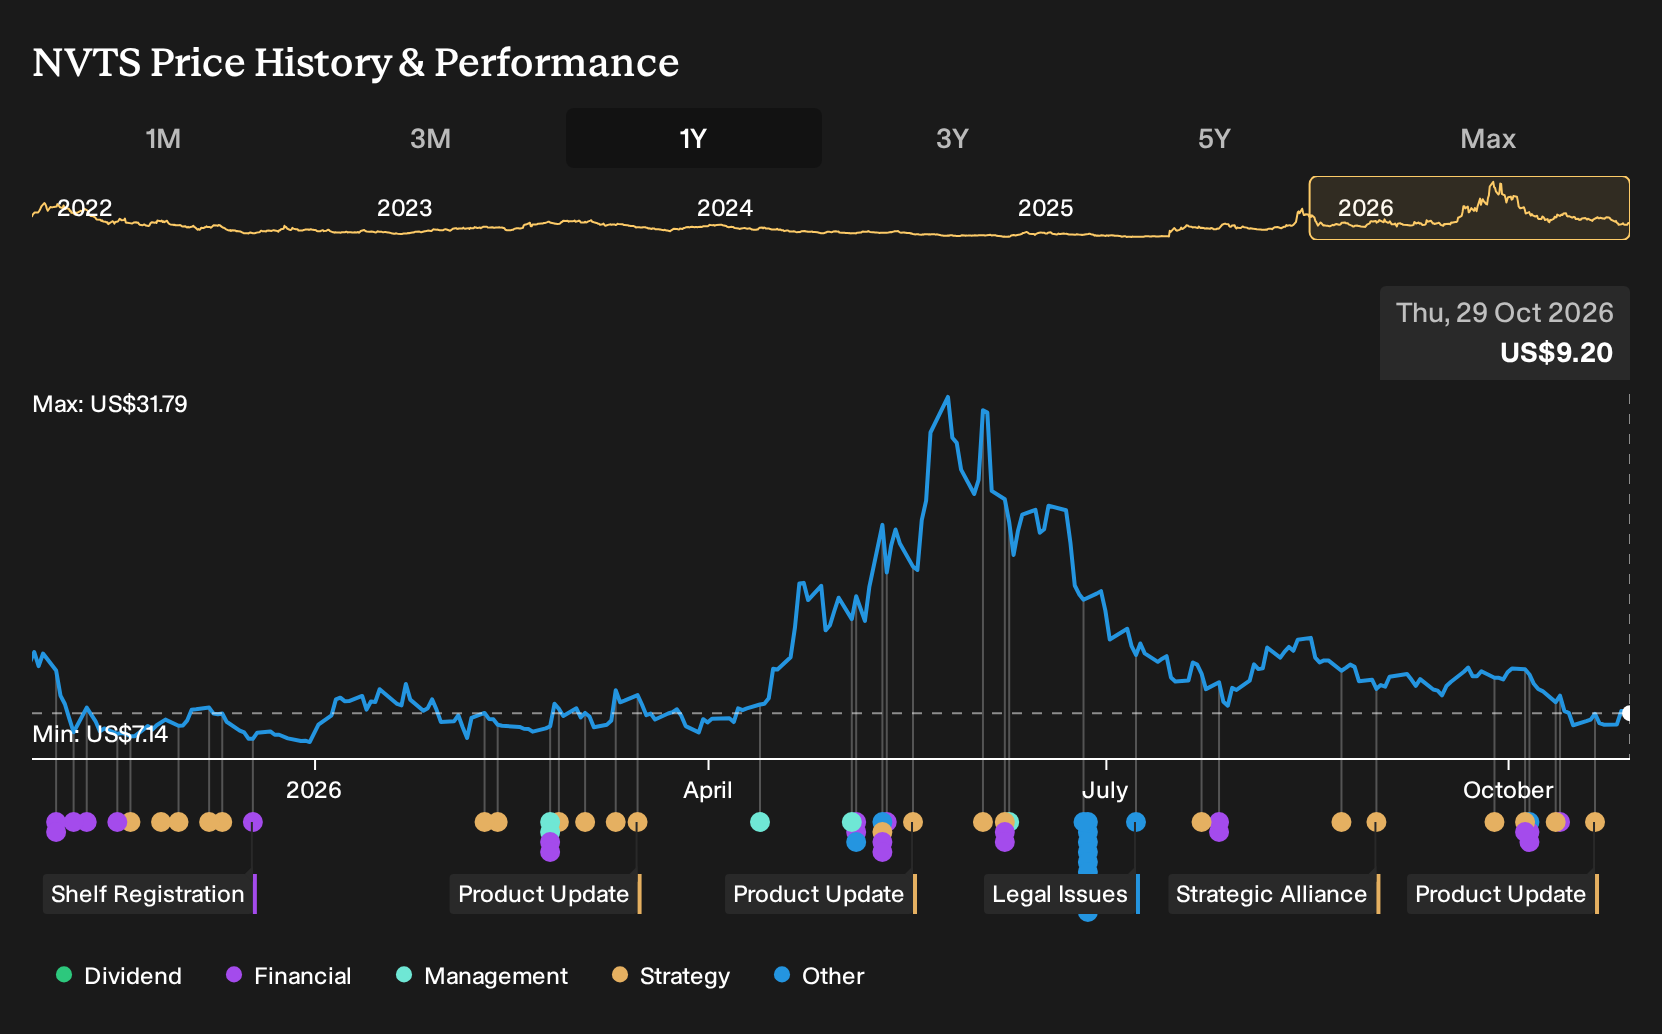
Exploring Other Perspectives
You can read the same UHV SiC launch and still reach a very different takeaway. The most bearish Navitas Semiconductor analysts worry that leaning harder into AI infrastructure raises volatility, and they were only modeling about US$123.6 million of revenue and US$24.8 million of earnings by 2029. Their cautious view predates this announcement, so you may want to see how their narrative shifts once the new grid focused modules are fully reflected in the numbers.
Explore 2 other Navitas Semiconductor fair value estimates, including one that suggests it could be worth just $14.08!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Navitas Semiconductor research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Navitas Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Navitas Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Navitas Semiconductor?
Once you have a view on Navitas Semiconductor, it can help to widen the lens and compare it with other opportunities that match your risk profile and income goals. The Simply Wall St Screener gives you a structured way to do that by filtering for traits that matter most to you.
- If you care about resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without stressing the finances.
- For investors who want a focus on quality at a reasonable price, scan a curated set of 30 high quality undervalued stocks that combine dependable cash flows with sensible valuations.
- If income is a priority, shortlist a pool of 7 dividend fortresses that aim to pair higher yields with business models built for durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com