
Is Comstock Resources (CRK) Undervalued After Lowered Earnings Forecasts?
Comstock Resources (CRK) heads into its early November earnings report with expectations set low, as analysts now project quarterly earnings of $0.03 per share and reduced revenue forecasts.
Recent trading has been choppy for Comstock Resources, with the share price falling 1.88% over the last session to US$14.59. However, the stock has delivered a 16.63% 30-day share price return, while the year-to-date share price return is down 38.13%. The 5-year total shareholder return of 63.04% suggests much stronger longer-term sentiment.
Scan how other hand-picked energy producers are priced around earnings season by running the 30 high quality undervalued stocks alongside Comstock Resources.
After a sharp 30 day rebound and a steep year to date decline, Comstock Resources sits at a crossroads. Is this recent rally a small preview of upside, or has the bulk of the move already played out before earnings?
Most Popular Narrative: 4% Undervalued
On Simply Wall St's widely followed narrative, Comstock Resources screens slightly cheap, with a fair value of $15.23 against the latest $14.59 close. That small gap sits on top of a much bigger debate about how durable its Haynesville gas story really is.
The company's proactive development of Western Haynesville specific midstream infrastructure (such as a major new gas treating plant) will allow for higher production levels, improved price realizations, and increased ability to capitalize on expanding U.S. LNG export capacity, thereby supporting revenue growth.
See why 10 investors see Comstock Resources as 4% undervalued.
Result: Fair Value of $15.23 (UNDERVALUED)
Still, heavy dependence on the Haynesville shale and the ongoing need for large drilling and midstream spending could quickly undermine the current Comstock Resources valuation story.
Find out about the key risks to this Comstock Resources narrative.
Another View On Comstock Resources Valuation
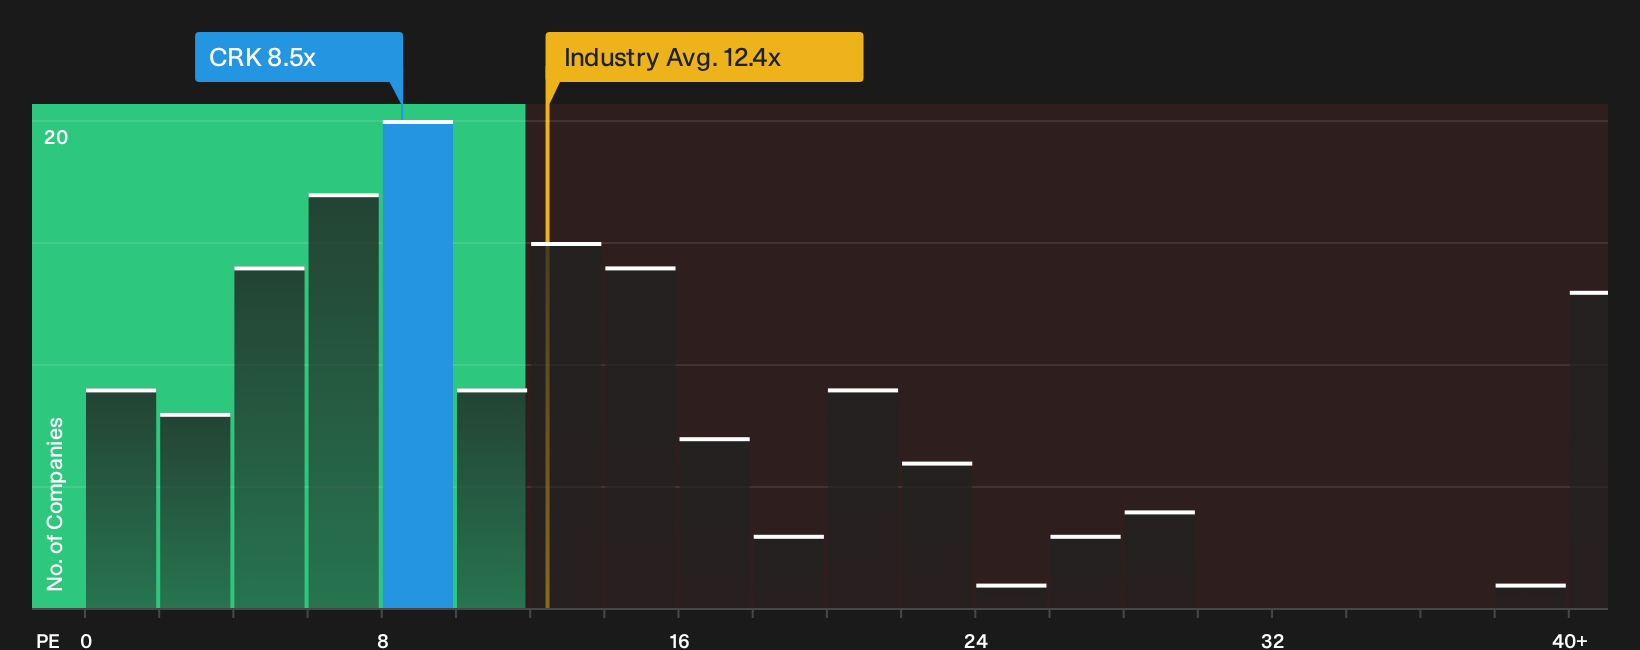
The Simply Wall St narrative focuses on fair value and long term earnings assumptions, yet the market is still paying 8.5x P/E for Comstock Resources compared with a fair ratio of 6.1x and a US Oil and Gas industry average of 12.3x. That gap hints at both room for re rating risk and peer related upside. Which side of that trade do you want to be on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Comstock Resources is clearly split. Use this as your cue to move quickly, review the full picture, and decide where you stand by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Comstock Resources?
If you only focus on Comstock Resources today, you risk missing other compelling setups that could fit your goals even better across quality, value, and resilience.
- Target potential mispricings by scanning a curated pool of quality companies using the 30 high quality undervalued stocks.
- Prioritize resilience in tougher markets by filtering for companies with robust financial footing through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed opportunities that the crowd might be ignoring by running the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com