
Westlake (WLK) Opens Texas PVCO Facility, Is The Stock Still Cheap?
Event backdrop for Westlake stock
Westlake (WLK) is in focus as investors weigh two fresh developments: a quarterly earnings report with lowered expectations and the completion of a large PVCO pipe facility in Wichita Falls, Texas.
Across the past month, Westlake’s 4.1% share price return contrasts with a weaker 90 day share price move, which is down 6.4%, while the 3 year total shareholder return has fallen 41.9%. This points to fading long term momentum despite recent interest around earnings and the new PVCO facility.
Compare Westlake with other building materials players that screen for resilient balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (23 results) while this earnings story unfolds.
Recent gains in Westlake look modest against a multi year slide, which leaves a key tension: Are you seeing an early reflection of business progress, or just investors repositioning ahead of earnings and the PVCO expansion story as it feeds into value?
Most Popular Narrative: 17% Undervalued
Westlake closed at $66.01 versus a most followed narrative fair value of $79.18, which frames the current setup as a discount despite analysts trimming their expectations.
Westlake''s three pillar profitability improvement plan, targeted to add $600 million of EBITDA benefit in 2026 with about $300 million already realized by mid year, remains an active lever through ongoing footprint optimization, cost savings and plant reliability efforts. These initiatives are intended to lower cost of sales and support net margin expansion.
See why 9 investors see Westlake as 17% undervalued.
Result: Fair Value of $79.18 (UNDERVALUED)
Still, the risk case is clear, with global chemical oversupply pressuring Performance and Essential Materials pricing, and higher North American energy costs capable of quickly squeezing Westlake margins again.
Find out about the key risks to this Westlake narrative.
Another View: SWS DCF says Westlake is Overvalued
The narrative fair value of $79.18 paints Westlake as 17% undervalued. The SWS DCF model tells a different story. On that cash flow view, an estimated value of $53.32 sits below the $66.01 share price. This frames the stock as overvalued instead. Which lens do you trust more right now?
For a closer look at the assumptions behind that cash flow view, Look into how the SWS DCF model arrives at its fair value.
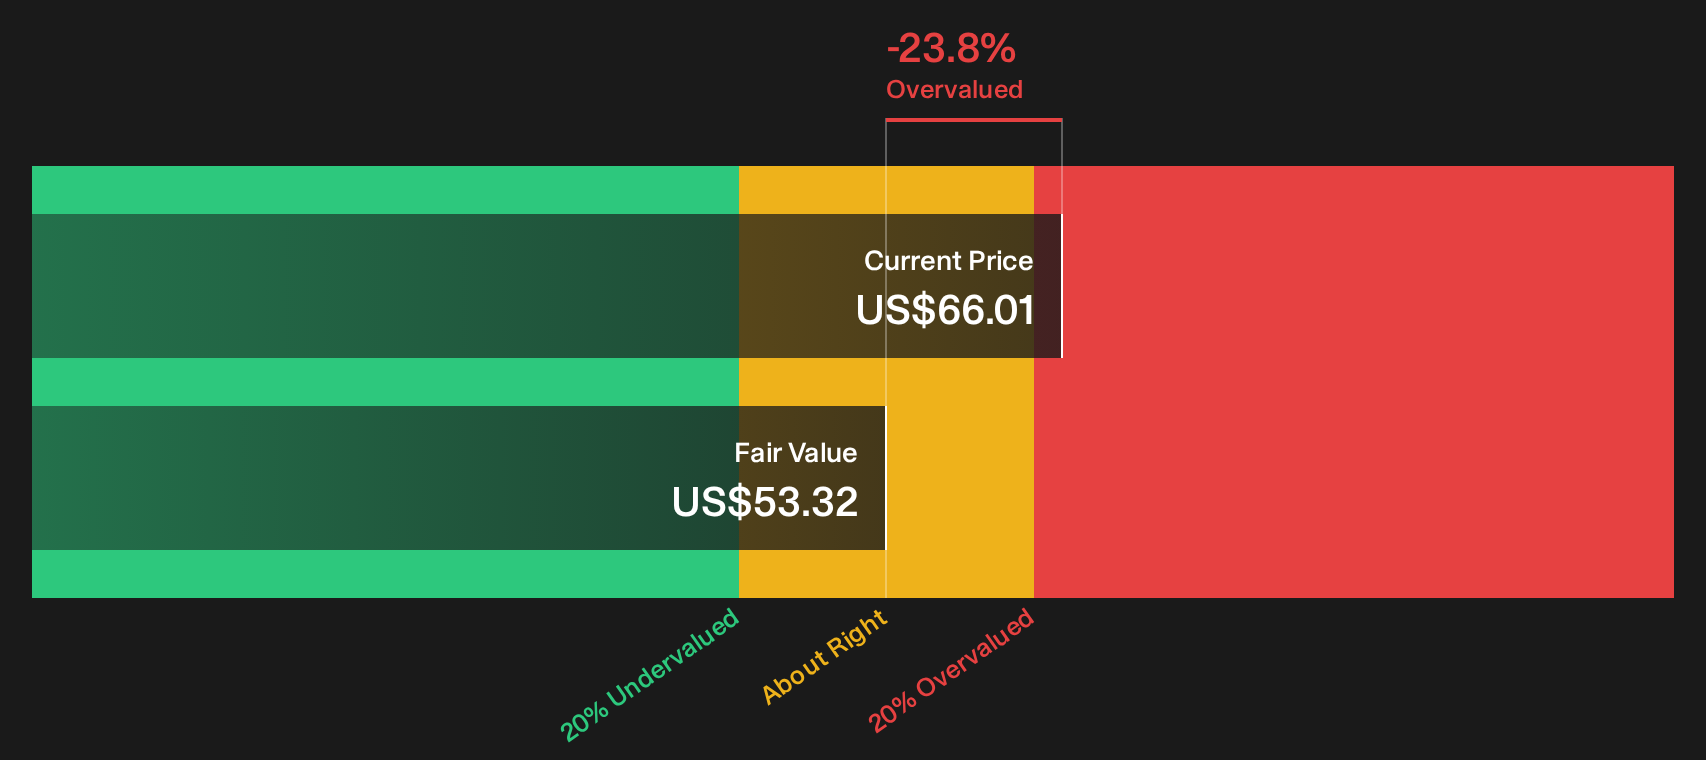
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westlake for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Westlake can be confusing, so use the data, not the noise, to ground your view and move quickly while sentiment is split. To weigh both the downside risks and upside potential in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more Westlake investment ideas?
If you only stop at Westlake, you could miss opportunities that fit your goals even better, so put the Simply Wall Street Screener to work for you.
- Target resilient compounding by focusing on dependable cash flows and robust finances through a curated 7 dividend fortresses that highlights income focused opportunities.
- Hunt for mispriced quality by scanning a concentrated 30 high quality undervalued stocks that filters for strong businesses trading at what may be discounted valuations.
- Reduce portfolio stress by leaning on a 30 resilient stocks with low risk scores that emphasizes resilient balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com