
What Danone (ENXTPA:BN)'s Sales Beat Means For Shareholders
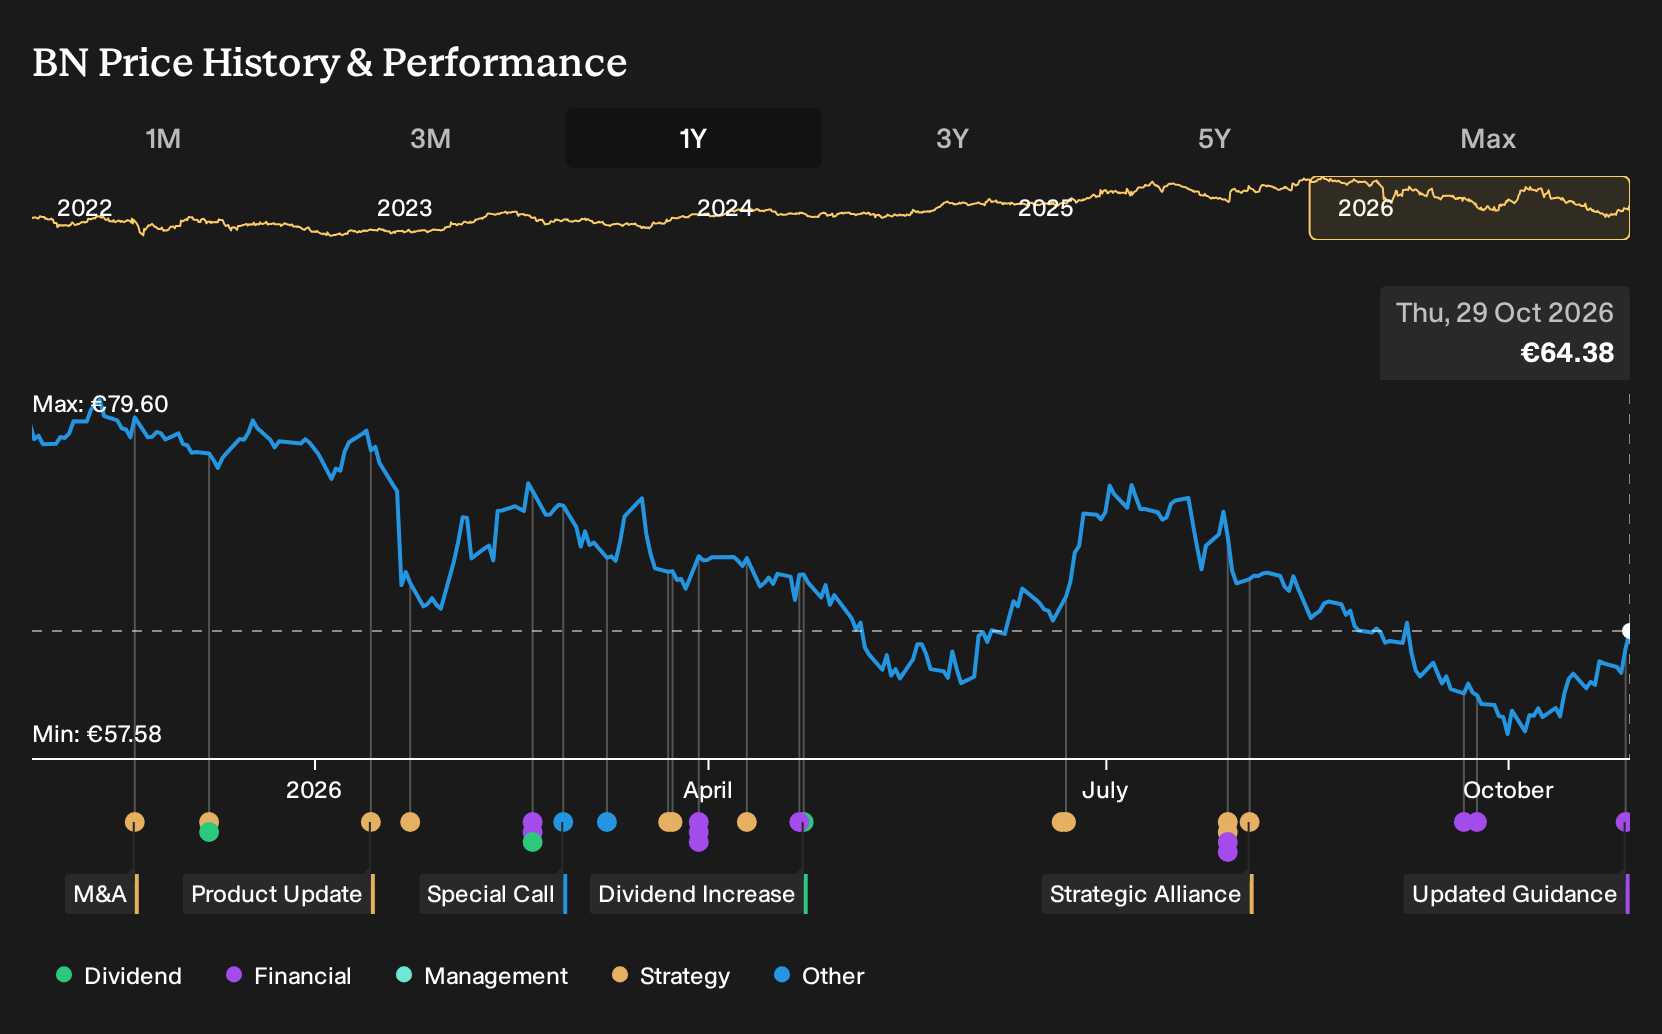
- Danone confirmed its 2026 guidance, targeting like for like sales growth between 3% and 5%, with recurring operating income expected to rise faster than sales, and Q3 2026 organic sales growth of 4.0% supported mainly by pricing, while also announcing new U.S. leadership after softer North America performance.
- The group launched a share buyback plan of about 3.5 million shares through the end of 2026 to offset dilution from employee share programs, which interacts directly with Danone’s capital allocation choices and the balance between reinvestment, incentives and returning cash to shareholders.
- We will now look at how Danone’s investment narrative could be influenced by the confirmed 2026 guidance and the announced share buyback.
Danone Investment Narrative Recap
To own Danone, you need to be comfortable with a slow and steady branded food group that leans on health focused categories, premium dairy, plant based and medical nutrition to compound earnings. The confirmed 2026 guidance, with like for like growth of 3% to 5% and recurring operating income rising faster, keeps that story intact rather than transforming it.
The near term swing factor sits in execution. Strong Q3 pricing and solid overall organic growth help, but soft North America and ongoing issues in segments like Mizone water in China keep operational risk real. Capacity ramp up, recall management and regional mix remain the biggest watchpoints.
The share buyback plan of about 3.5 million shares through the end of 2026 is the announcement that matters most here. It is sized to offset dilution from employee share programs, so it directly affects per share metrics without signalling a shift in Danone’s growth priorities or cash needs.
For you as an investor, the main operational catalysts still come from high protein dairy, medical nutrition, infant formula and emerging market IMF, not from financial engineering. The buyback can smooth share count while you focus on whether new U.S. leadership, capacity investments and sustainability projects translate into more stable margins and cash generation.
Danone's current analyst narrative points to €31.3b revenue and €2.8b earnings by 2029, based on revenue increasing 4.5% per year and earnings rising by about €0.9b from €1.9b today.
Uncover why Danone's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community sit between €78.52 and €118.79 per share, a wide span for the same Danone equity story. Those private investors have not yet reacted to the confirmed 2026 guidance or fresh U.S. leadership, so you are weighing their optimism against risks around North America execution and China softness.
Explore 2 other Danone fair value estimates, including one that suggests it could be worth just €78.52!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Danone research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Danone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Danone's overall financial health at a glance.
Looking for more investment ideas beyond Danone?
Once you are clear on where you stand with Danone, it can help to widen the lens and compare it with other opportunities that share similar financial traits. The Simply Wall St Screener lets you filter for exactly the kind of businesses you want to research next.
- If capital protection sits high on your list, you could focus on companies that pair steadier profiles with robust fundamentals through our 220 resilient stocks with low risk scores.
- For investors who care about financial resilience first, you might zero in on businesses with cleaner balance sheets and solid core metrics via the list of solid balance sheet and fundamentals (203 results).
- If you prefer to look where fewer people are paying attention, you can scan a pool of under-followed opportunities with strong underlying quality using the 605 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com