
What to Expect From Apple’s Q4
Apple (AAPL) will report its fourth-quarter earnings on Nov. 2. Strong demand for the iPhone and Mac is expected to support the company's performance, although supply constraints could limit sales growth.
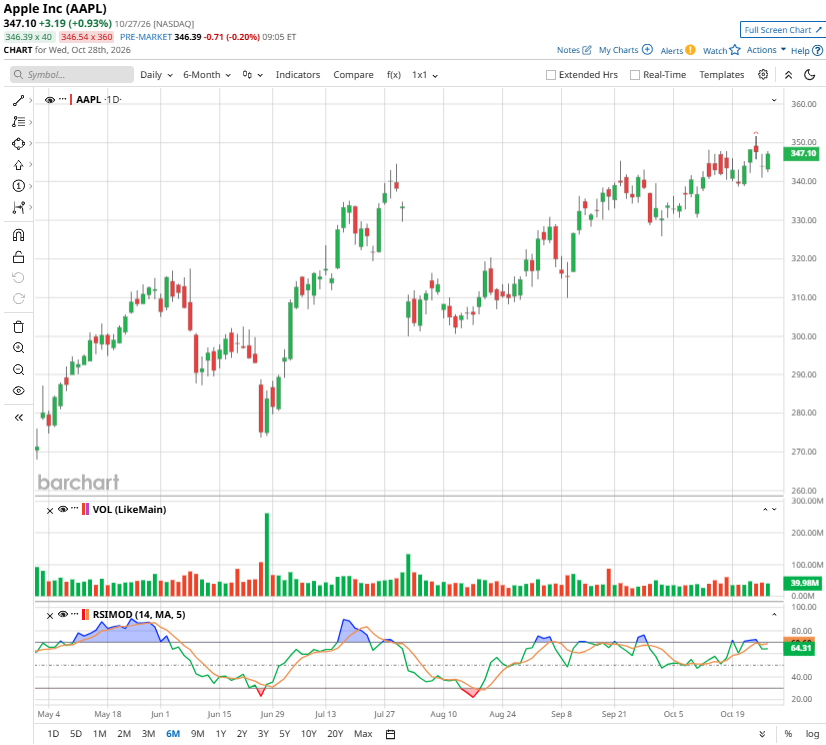
AAPL stock has gained 28% so far this year and hit a new 52-week high of $351.73 on Oct. 23. The rally, supported by strong momentum in Apple's products and services businesses, has pushed the stock's valuation higher ahead of the Q4 earnings announcement. Let's take a closer look.
Supply Challenges Could Hurt Apple’s Q4 Growth
Apple’s Q4 report will likely reflect slower growth despite sustained demand for its core hardware products. During the Q3 earnings call, management indicated that customer demand for the iPhone and Mac remained robust but cautioned that supply constraints were expected to intensify sequentially, impacting growth.
Consequently, management projected total revenue growth of 9% to 11% year-over-year (YOY) for Q4. That signaled moderation from the stronger growth reported in the preceding quarter.
Apple delivered revenue of $109.4 billion in Q3, up 16% YOY. Performance remained broad-based, with every geographic segment recording double-digit growth. Product revenue increased 18% YOY to $78.7 billion, supported by strong contributions from the iPhone and Mac.
The iPhone remained Apple’s largest revenue contributor, generating $54.3 billion, up 22% YOY. The iPhone 17 lineup drove growth, with double-digit gains across most markets. Apple also reported an all-time high in its active iPhone installed base and a June-quarter record for customers upgrading their devices. These indicators suggest that the company continues to benefit from customer retention, upgrade demand, and the strength of its broader ecosystem.
Mac revenue rose 29% YOY to $10.4 billion in Q3. The performance reflected strong demand for the MacBook Neo and MacBook Pro, with growth across both developed and emerging markets.
Although Apple expects iPhone demand to remain strong in the September quarter, management anticipates supply constraints and unfavorable foreign exchange movements will weigh on the reported growth rate. The company projected mid-teens YOY growth in iPhone revenue, below the 22% YOY growth achieved in Q3.
Apple’s Services segment is expected to sustain momentum. Management indicated that Services revenue should grow at a pace broadly comparable to Q3. The segment generated $30.7 billion in Q3, an increase of 12% YOY.
The business benefits from Apple’s extensive installed base of more than 2.5 billion active devices, which provides a substantial platform for recurring revenue generation. Paid subscriptions now exceed 1.5 billion, while both transacting accounts and paid accounts reached new quarterly records. The company also reported double-digit growth in these account categories across emerging markets. Advertising, the App Store, AppleCare, Apple Music, Apple TV+, cloud services, and payment-related offerings are among the businesses supporting this expansion.
The company's earnings outlook also suggests a more moderate growth trajectory in Q4. Slower revenue growth and higher memory costs could pressure margins and constrain earnings growth. Analysts expect Apple to report EPS of $1.98, representing about 7% YOY growth. This would mark a notable deceleration from the 29% increase in earnings reported in Q3. However, the previous quarter’s comparison included a $0.11 per share benefit from tariff refunds.
Is Apple Stock a Buy?
Apple’s Q4 performance is likely to be supported by resilient iPhone and Mac demand and continued Services growth, although supply constraints and higher memory costs could moderate revenue and earnings growth. With expected EPS growth slowing to 7% and AAPL stock trading near record highs, investors should take caution before going long on Apple shares ahead of earnings.
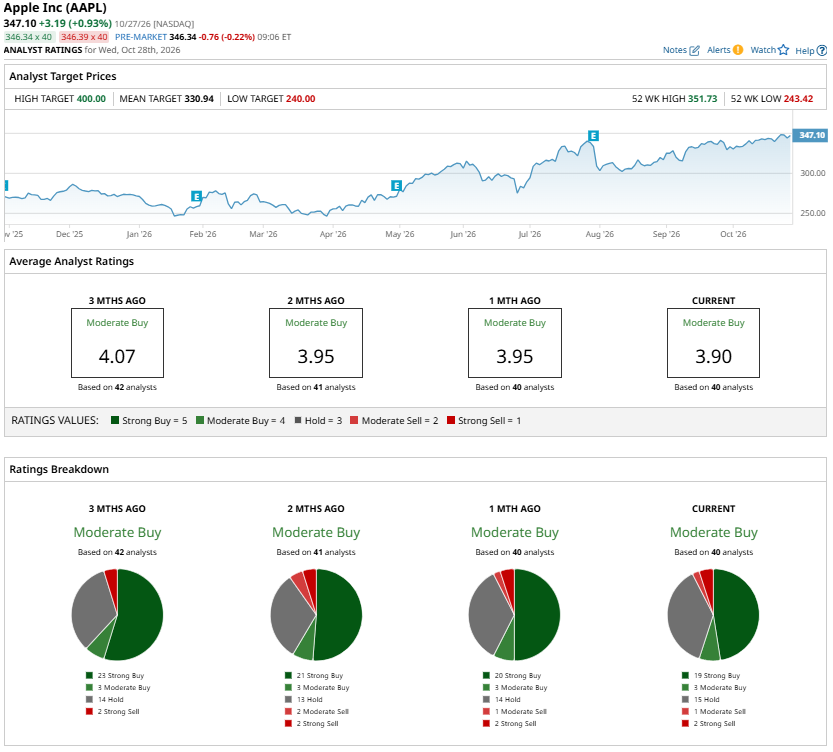
Overall, Wall Street analysts maintain a consensus “Moderate Buy” rating for Apple stock.
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.