
Dear CoreWeave Stock Fans, Mark Your Calendars for November 10
The neocloud trade is cracking. CoreWeave (CRWV) and peers have built their businesses on a simple promise based on seemingly endless demand for artificial intelligence (AI) compute and access to cheap capital. That promise is now being stress-tested in real time, and the bond market is the one asking the uncomfortable questions.
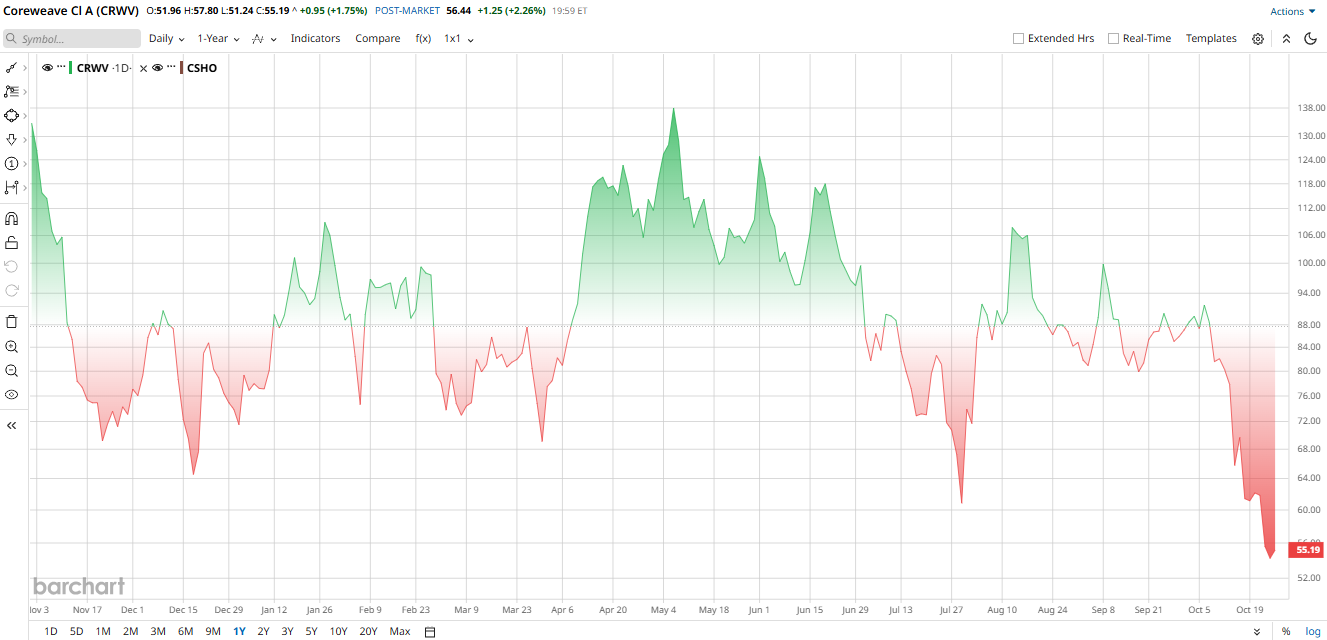
But CoreWeave is forcing investors to answer right now. Shares of the AI infrastructure darling recently touched a fresh 52-week low of $51.24. CRWV stock is now down more than 56% over the past year and down a staggering 68% from its June 2025 peak of $187.
With third-quarter results due Nov. 10, the CoreWeave debate has shifted from "How high can it fly?" to “Can it survive its own balance sheet?” Let's take a closer look.
A Pure Bet on AI Infrastructure
CoreWeave may not be the most immediately recognizable household name, but it does power some of the biggest names in tech. The company has 51 data centers filled with more than 250,000 Nvidia (NVDA) GPUs, processing AI workloads about 35 times quicker and 80% cheaper than older cloud platforms. Additionally, CoreWeave's customers include Microsoft (MSFT), Meta Platforms (META), OpenAI, and Anthropic (ANT), while Nvidia is one of its biggest institutional shareholders.
All told, CoreWeave is as "pure" as it gets when it comes to owning a piece of the AI boom
Why CoreWeave Stock Has Crashed in 2026
CoreWeave stock's collapse has been brutal, with shares down 15% year-to-date (YTD) and nearly 57% for the past year. The October selloff can be traced back directly to some of CoreWeave's unsecured debt trading at a yield of roughly 15%. That has driven bonds into distressed territory. For CoreWeave, there is also at least a meaningful probability that it may not be able to meet its obligations, which is being priced into the market.
The actual harm comes with what happens going forward. CoreWeave will continue to borrow money to finance its ramp-up of large data centers because it needs to do so to win amid the AI boom. At its core, the bull thesis has revolved around easy access to cheap capital. That statement is being challenged now. The bond market is saying the opposite, while Nvidia CEO Jensen Huang has responded by saying CoreWeave's cost of capital is indeed shrinking.
What to Expect From Q3 Earnings
Wall Street expects $3.54 billion in Q3 revenue for CoreWeave, up 159% year-over-year (YOY). Meanwhile, the company forecast revenue of $3.45 billion to $3.6 billion for the quarter. Looking beyond Q3, analysts also expect full-year revenue of $12.87 billion and a loss per share of $4.97 in fiscal 2026.
The company does have some positives working for it. CoreWeave's massive revenue backlog is now $104 billion, up 246% YOY. Meanwhile, the company reported in September that it had "signed short-dated customer contracts of approximately three to six months, with pricing of approximately $40 million per megawatt" in Q3.
The company has beaten estimates before, and there is a chance it will outperform estimates for Q3. The wild card will be the stock's reaction, however, with options suggesting volatility. Investors will want to pay close attention not only to the top line, but also interest expense, capital expenditures guidance, and any talk about refinancing.
What Does Wall Street Think of CRWV Stock?
Wall Street is split on CoreWeave stock. On Oct. 19, Goldman Sachs upgraded CRWV stock to a “Buy” from “Neutral” while cutting its price target to $106 from $139 amid the selloff. Other firms have also kept their positive ratings while cutting targets. UBS recently cuts its target to $105 from $120, while Bank of America kept its target at $140. Morgan Stanley is more conservative with a $70 target on CoreWeave, while HSBC's target of $39 is the lowest price tag on Wall Street.
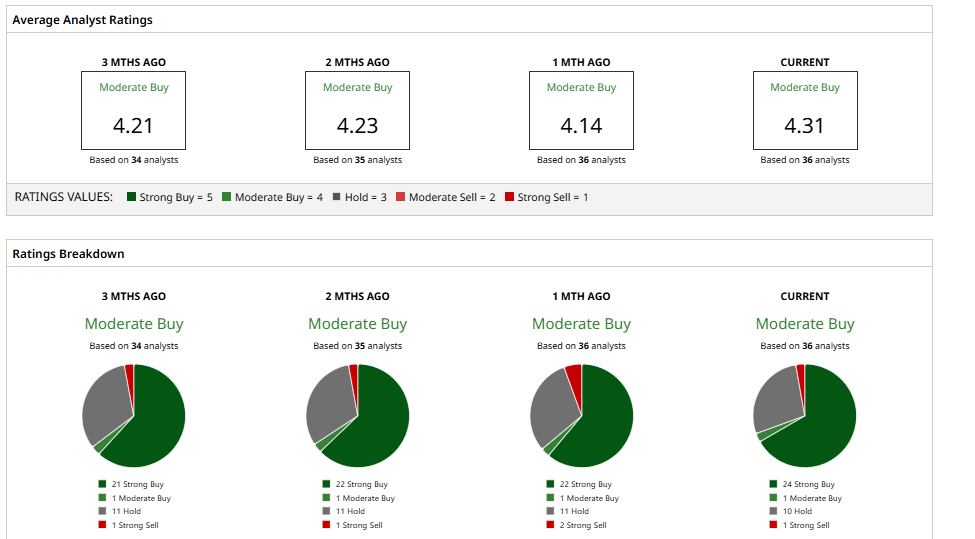
Overall, CRWV stock has a consensus "Moderate Buy" rating. The mean price target of $128.57 suggests potential upside of 112% from current levels. Some analysts believe a significant recovery may still occur, but investors are worried about the dangers threatening the AI infrastructure company.
If investors are willing to endure the volatility, then CoreWeave may present an opportunity as AI compute demand increases. Still, the company's financial risks are a significant concern. The bond market doesn't provide a comforting message, with CRWV stock appearing to be a high-risk proposition.
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.