
Exa Integration Could Be A Game Changer For ZoomInfo Stock (GTM)
- ZoomInfo Technologies recently launched a native integration with Exa, letting mutual customers and developers feed ZoomInfo GTM Intelligence directly into Exa’s AI agent workflows through Exa Connect, APIs, and the GTM.AI MCP server.
- The link between ZoomInfo’s GTM Context Graph and Exa’s single-request agent routing gives enterprise users a unified stream of B2B identity data, buying signals, and governance controls inside the agent ecosystems they already rely on.
- We will now look at how this deeper Exa integration could influence ZoomInfo Technologies’ investment narrative around AI driven go to market workflows.
Scan how ZoomInfo Technologies fits into the broader AI buildout by reviewing a hand picked 54 AI infrastructure stocks that are wiring agent workflows into real go to market data streams.
ZoomInfo Technologies Investment Narrative Recap
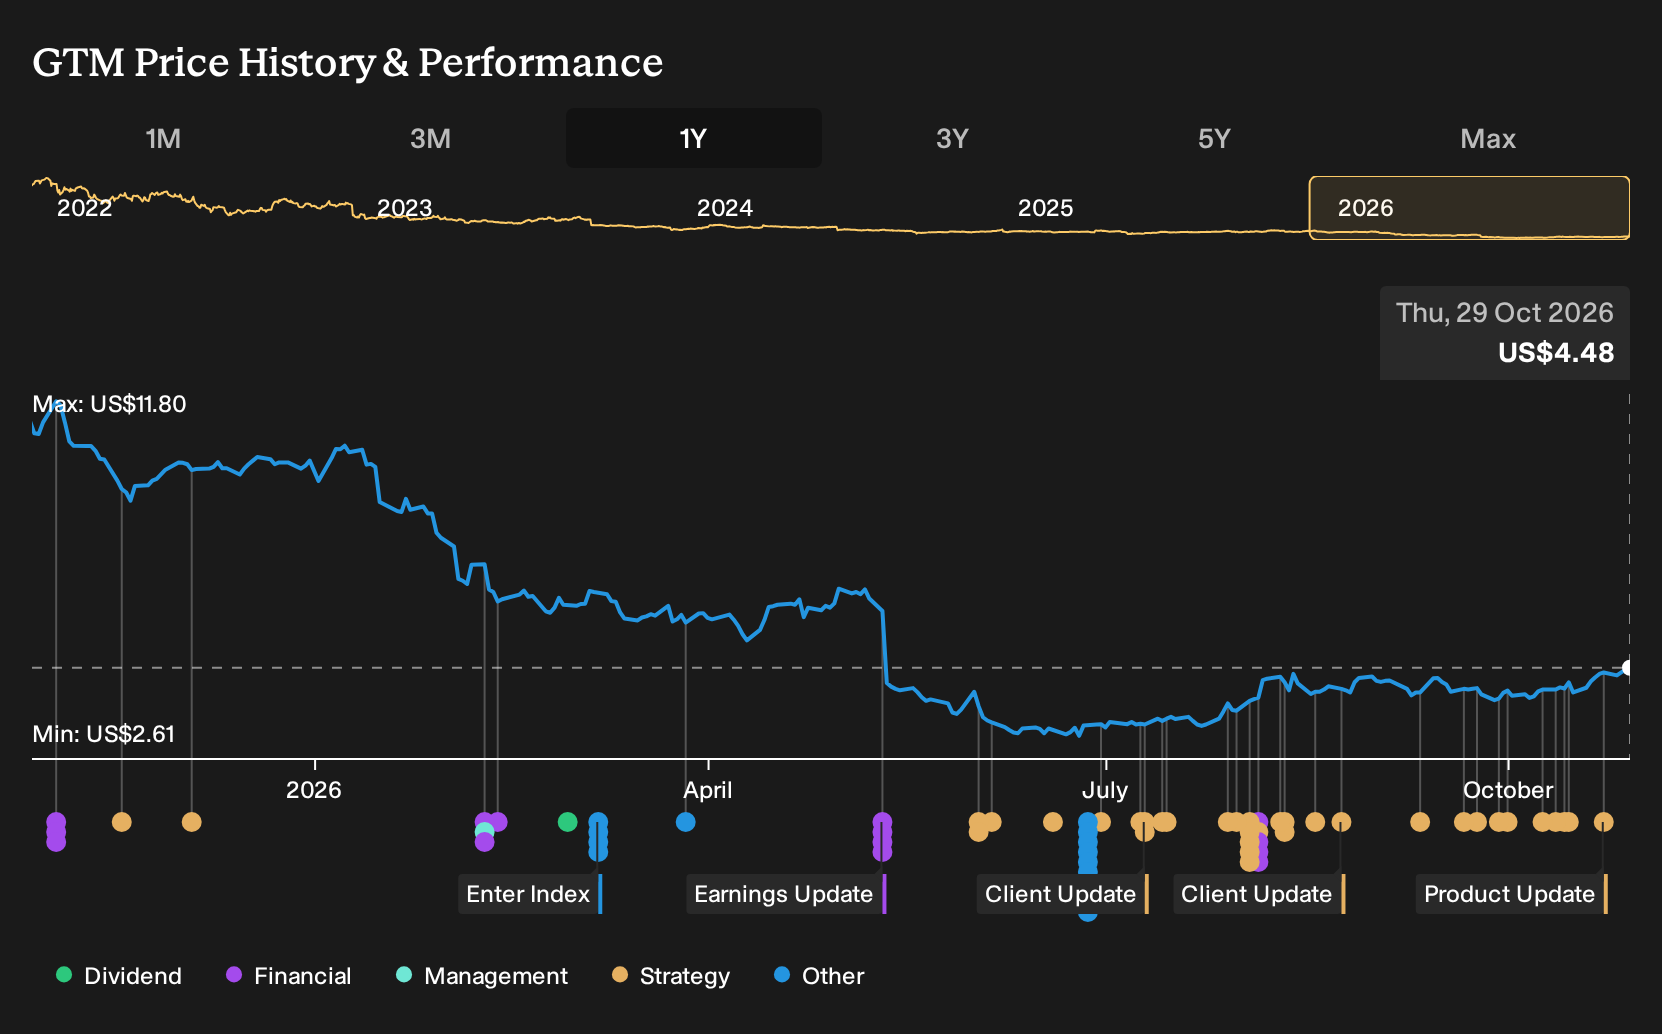
To own ZoomInfo Technologies, you have to buy into the idea that high quality B2B data remains a foundational input for AI driven go to market workflows, even while revenue is expected to decline modestly and the business is still loss making. The short term swing factor is execution on upmarket, higher value customers without losing too much breadth as downmarket revenue falls.
The biggest operational concern is concentration and product commoditization. Heavy investment in AI and automation raises the bar for differentiation just as regulation, debt levels, and weak share performance increase pressure on management. The Exa integration looks directionally helpful for relevance, but on its own it does not change the near term risk profile.
The Exa connector is the operational story investors should focus on here because it plugs ZoomInfo GTM Intelligence directly into an emerging agent ecosystem rather than asking customers to rip and replace existing workflows. Mutual clients can keep their current Exa based processes and simply route identity resolved B2B data, contact enrichment, and buying signals through GTM.AI.
That matters for catalysts because the stronger ZoomInfo’s presence is inside third party agent platforms, the more it can support the thesis that enterprises standardize on it as a data foundation even while headline revenue is expected to drift lower. It also speaks directly to the commoditization risk, since tighter workflow integration and governance tooling are harder for lower cost datasets and open source competitors to copy.
ZoomInfo Technologies Forecasts Behind the Exa Story
ZoomInfo Technologies sits on an awkward mix of shrinking top-line expectations and sharply improving profitability in analyst models. That tension is exactly what makes the deeper Exa integration worth watching.
Consensus assumptions today build in revenue declining by 1.3% a year for the next three years. Analysts still expect a swing from a loss of US$541.0 million in earnings today to US$391.8 million by 2029, with profit margins moving from a 43.0% loss to a 32.4% margin over roughly the same window. That is a very large earnings shift in dollar terms, even with only modest pressure on sales.
For that earnings bridge to hold together, the stock would need to reach a P/E of 3.9x on those 2029 profits. This compares with a current multiple of 2.2x based on loss-making earnings. That implied future P/E also sits well below the 13.5x level cited for the broader US Interactive Media and Services peer group, so the scenario is not built on a premium valuation multiple.
Analysts are also assuming the share count gradually contracts, with a projected 6.57% annual decline in shares outstanding over the next three years. For investors, that means a lot of the upside case is tied to margin recovery, lower dilution, and a lower headline valuation multiple doing the heavy lifting rather than a growth rebound in revenue.
ZoomInfo Technologies' narrative projects US$1.2b revenue and US$391.8 million earnings by 2029. This bakes in a 1.3% yearly revenue decline and a very large earnings increase from a loss of US$541.0 million today.
Uncover why ZoomInfo Technologies' fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed ZoomInfo Technologies as a test of whether GTM.AI and agent integrations can offset shrinking seats, with forecasts for roughly flat revenue and earnings of about US$366.1 million by 2029. You now have the Exa connector on top of that, so treat these pre news views as a starting point and compare several angles before deciding what feels realistic for you.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests as much as 183% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond ZoomInfo Technologies?
If ZoomInfo Technologies is on your radar, it can help to compare it with other opportunities that fit different risk, quality, and income profiles. The Simply Wall St Screener gives you a structured way to line up candidates side by side and pressure test your thesis across multiple angles.
- If capital preservation is high on your list, start by reviewing a 30 resilient stocks with low risk scores that historically score well on resilience and balance sheet strength.
- For investors who want income potential, scan a curated 7 dividend fortresses that pair higher yields with more robust cash generation.
- If you are hunting for underfollowed opportunities, check a hand picked 18 high quality undiscovered gems that combine solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com