
Liberty Global (LBTYA) Stock Looks Like A Bargain On Sales
Liberty Global has seen a steep share price slide in recent years, and the question now is whether the current US$7.70 level still lines up with what the business delivers in sales. With the stock under pressure, investors are increasingly asking how much revenue power they are actually paying for at this price.
- The share price has fallen 46.8% over the past 5 years, which puts the focus squarely on whether the underlying sales profile can justify the value the market assigns today.
- The group relies heavily on its ability to convert telecom and media services into consistent top line revenue, so expectations for subscriber stability, pricing and capital intensity can all influence how its sales base supports the current valuation.
- There is a second opinion on Liberty Global worth weighing. See what analysts think Liberty Global's shares could be worth.
The stock's next move may depend on whether Liberty Global's current price still makes sense when you compare it with the sales the business is generating.
If you want to stress test Liberty Global's valuation question against a broader set of opportunities, compare it with 30 high quality undervalued stocks.
Does Liberty Global Look Undervalued on Sales?
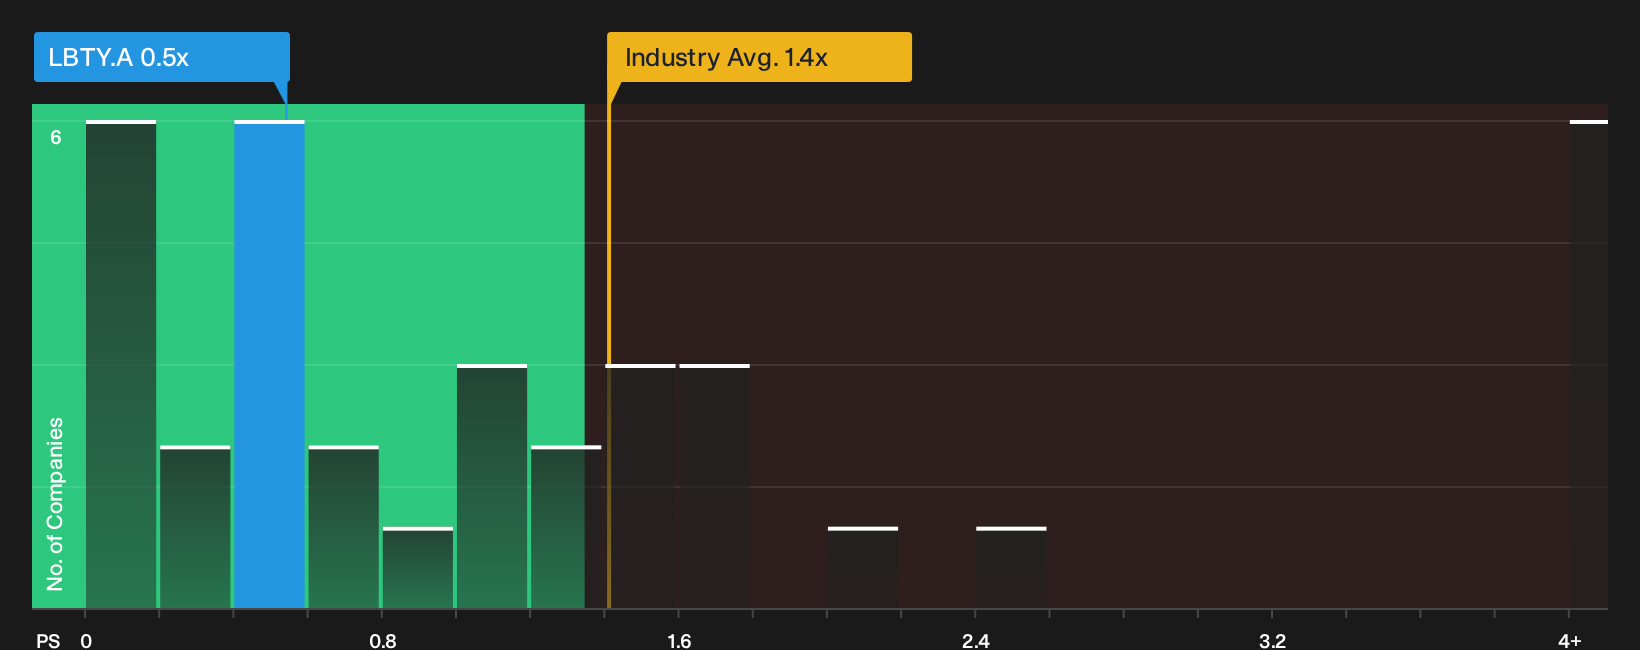
P/S works well for Liberty Global because investors can link the share price directly to the revenue line, which is more stable than earnings for a capital heavy telecom group. On this yardstick, the stock trades on a P/S of about 0.5x, against an industry average of roughly 1.4x and a broader peer mark near 2.2x. That is a sizeable gap between what the market currently pays for Liberty Global's sales and what it pays for telecom revenue more generally.
The valuation model that blends the company’s growth profile, margins, scale and risk points to a higher P/S as a reasonable anchor, and Liberty Global’s present multiple sits below that mark. For an investor comparing options across the sector, this discount suggests the market is placing a relatively low price on each dollar of Liberty Global revenue, while peers command richer tags for their turnover. Explore the numbers behind Liberty Global's P/S valuation.
The Liberty Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Liberty Global valuation puzzle leaves off, by spelling out which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than today’s price on the market. Each storyline links a specific set of potential catalysts and risks to an implied fair value, so you can track over time which version of Liberty Global's future appears to be taking shape.
The community is split on Liberty Global, with one camp focused on asset value against the share price and the other zeroed in on leverage and cash strain.
Bull case: 36% undervalued
"Liberty Global ($LBTYA) closed October 16 at $7.80 per share, putting the combined market value of its three share classes below $3 billion..."
Discover why this Narrative puts Liberty Global at 36% undervalued.
Bear case: 10% overvalued
"Reliance on such transactions to support the balance sheet and fund commitments can point to a business that still needs portfolio sales rather than internal cash generation..."
Explore why this Narrative puts Liberty Global at 10% overvalued.
One more angle on Liberty Global that could change your view
Liberty Global’s share price and sales multiple tell only part of the story, because our broader checks have highlighted specific areas of concern that investors often ignore at first glance. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com