
Do Lower Charge Offs Change The Bull Case For QCR Holdings (QCRH)?
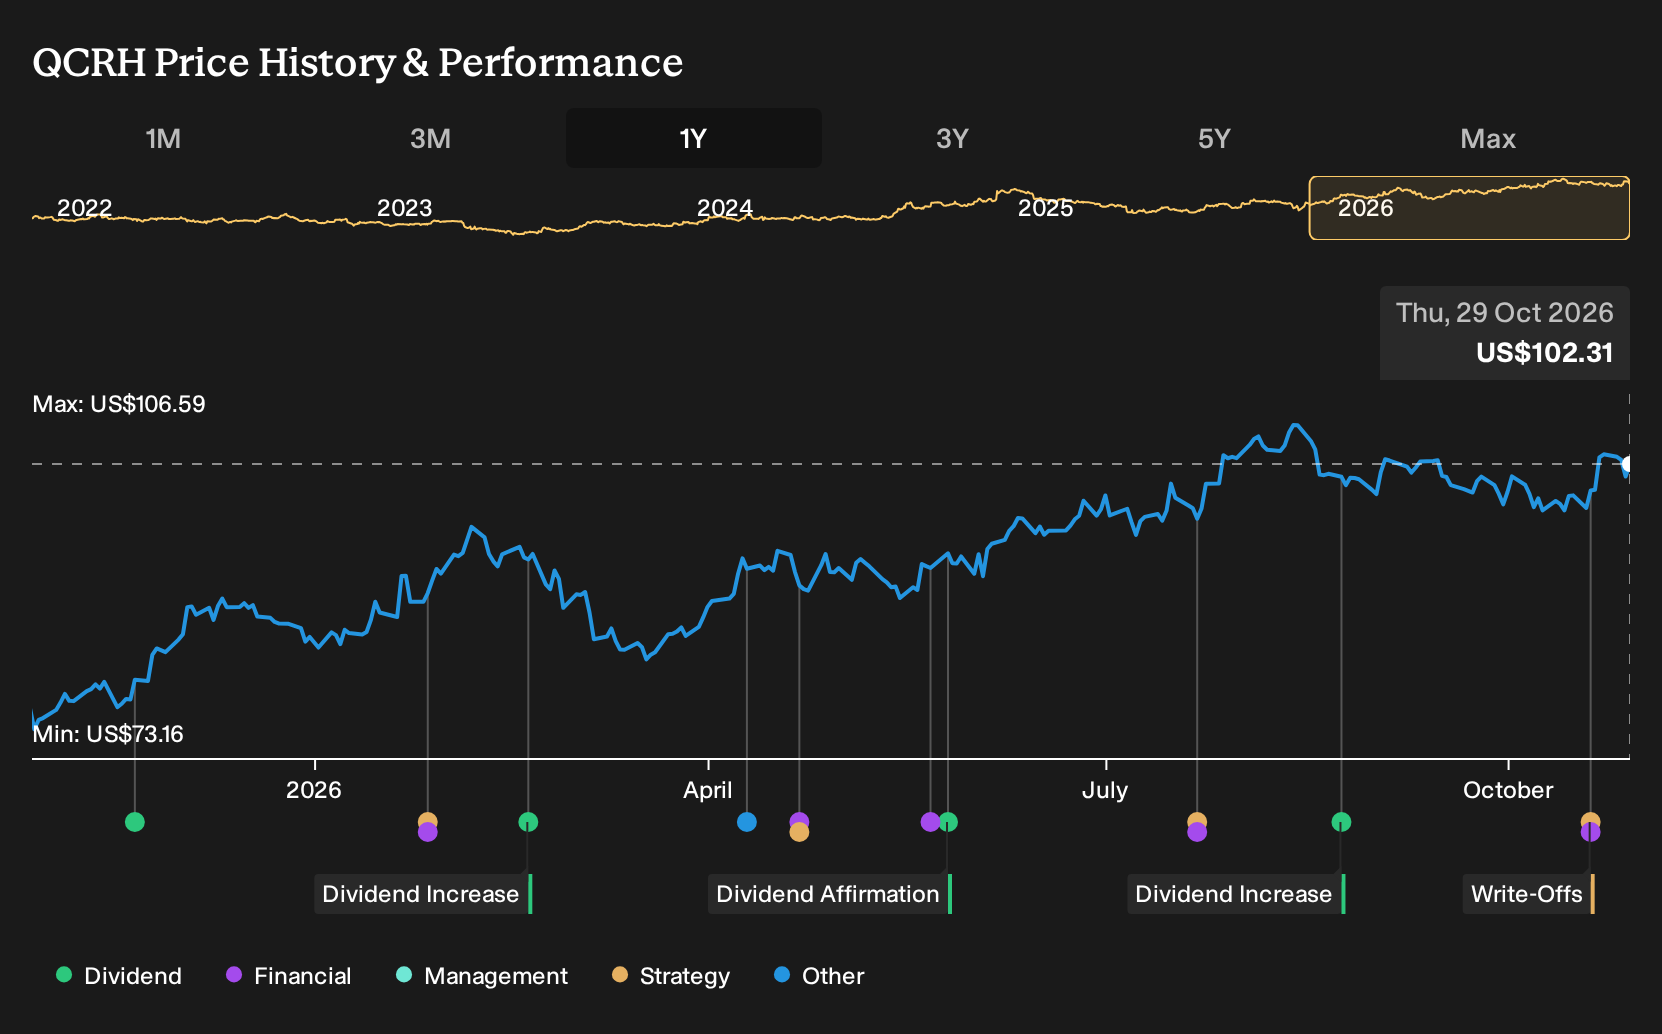
- QCR Holdings reported third quarter 2026 results, with net interest income of US$68.69 million, net income of US$36.43 million, and net charge offs of US$3.1 million that were lower than the prior quarter and the lowest level reported in 2026.
- The combination of higher quarterly net interest income compared with a year earlier and reduced charge offs from the m2 portfolio winddown highlights how QCR Holdings is balancing earnings power with credit cleanup.
- This raises the question of how QCR Holdings' lower third quarter net charge offs may influence the longer term investment narrative.
Compare QCR Holdings' credit clean up story with other resilient balance sheet plays by scanning a hand picked 30 resilient stocks with low risk scores that share similar risk focused profiles.
QCR Holdings Investment Narrative Recap
To own QCR Holdings, you need to be comfortable with a regional bank that is still mid journey on digital upgrades, managing LIHTC concentration and preparing to cross the US$10b asset threshold. The latest quarter supports that credit clean up remains on track, with net charge offs at US$3.1 million, the lowest level reported in 2026.
The near term swing factor remains execution on technology integration and cost control, not this specific quarter. Key risk still sits in potential expense pressure or LIHTC volatility that could weigh on efficiency and earnings, and this earnings print does not materially change that equation.
The third quarter earnings release is the clearest lens for this news. Net interest income of US$68.69 million and net income of US$36.43 million, alongside basic EPS from continuing operations of US$2.23, show QCR Holdings producing solid profitability while the m2 portfolio winds down and credit costs ease.
For catalysts, you would likely focus on whether this earnings power can continue as the unified Jack Henry SilverLake core conversion progresses and LIHTC securitizations are used to manage under US$10b in assets through 2026. The quarter keeps that operational story intact, while underscoring that execution and cost discipline are still the main watchpoints.
QCR Holdings Forecast Setup and Valuation Anchors
For QCR Holdings, the consensus blueprint is fairly clear. Analysts are building their models around revenue rising by 6.7% a year over the next three years, with profit margins easing from 37.4% today toward 33.5% over that window. Earnings today are set at US$142.0 million and the same group expects that figure to reach US$154.3 million by 2029, which is an increase of about US$12 million on current profit.
Based on those inputs, the revenue line is projected to reach US$460.3 million by 2029 and earnings are expected to match the US$154.3 million figure in that same year. To align this with current pricing, analysts are using a P/E of 13.3x on the 2029 earnings estimate, compared with 11.5x today for both QCR Holdings and the broader US banks industry in the report, and are discounting those future cash flows at roughly 7.2% to 7.24%.
QCR Holdings' narrative projects US$460.3 million revenue and US$154.3 million earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about US$12 million from US$142.0 million today.
Uncover why QCR Holdings' fair value indicates an 8% potential upside to its current price that may not last much longer.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QCR Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for QCR Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QCR Holdings' overall financial health at a glance.
Looking for more QCR Holdings style investment ideas?
If the QCR Holdings story appeals to you because of its mix of earnings power and balance sheet discipline, it can be useful to line it up against other companies that share similar qualities using the Simply Wall St Screener.
- If capital preservation comes first for you, compare QCR Holdings with a list of solid balance sheet and fundamentals (23 results) that aim to prioritize financial resilience.
- If value is your core filter, set QCR Holdings alongside a 30 high quality undervalued stocks that pair strong fundamentals with pricing that analysts suggest may be attractive.
- If you prefer less followed opportunities, contrast this regional bank with a 18 high quality undiscovered gems that combine solid financial profiles with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com