
Is Stronger Earnings Altering The Investment Case For BancFirst (BANF)?
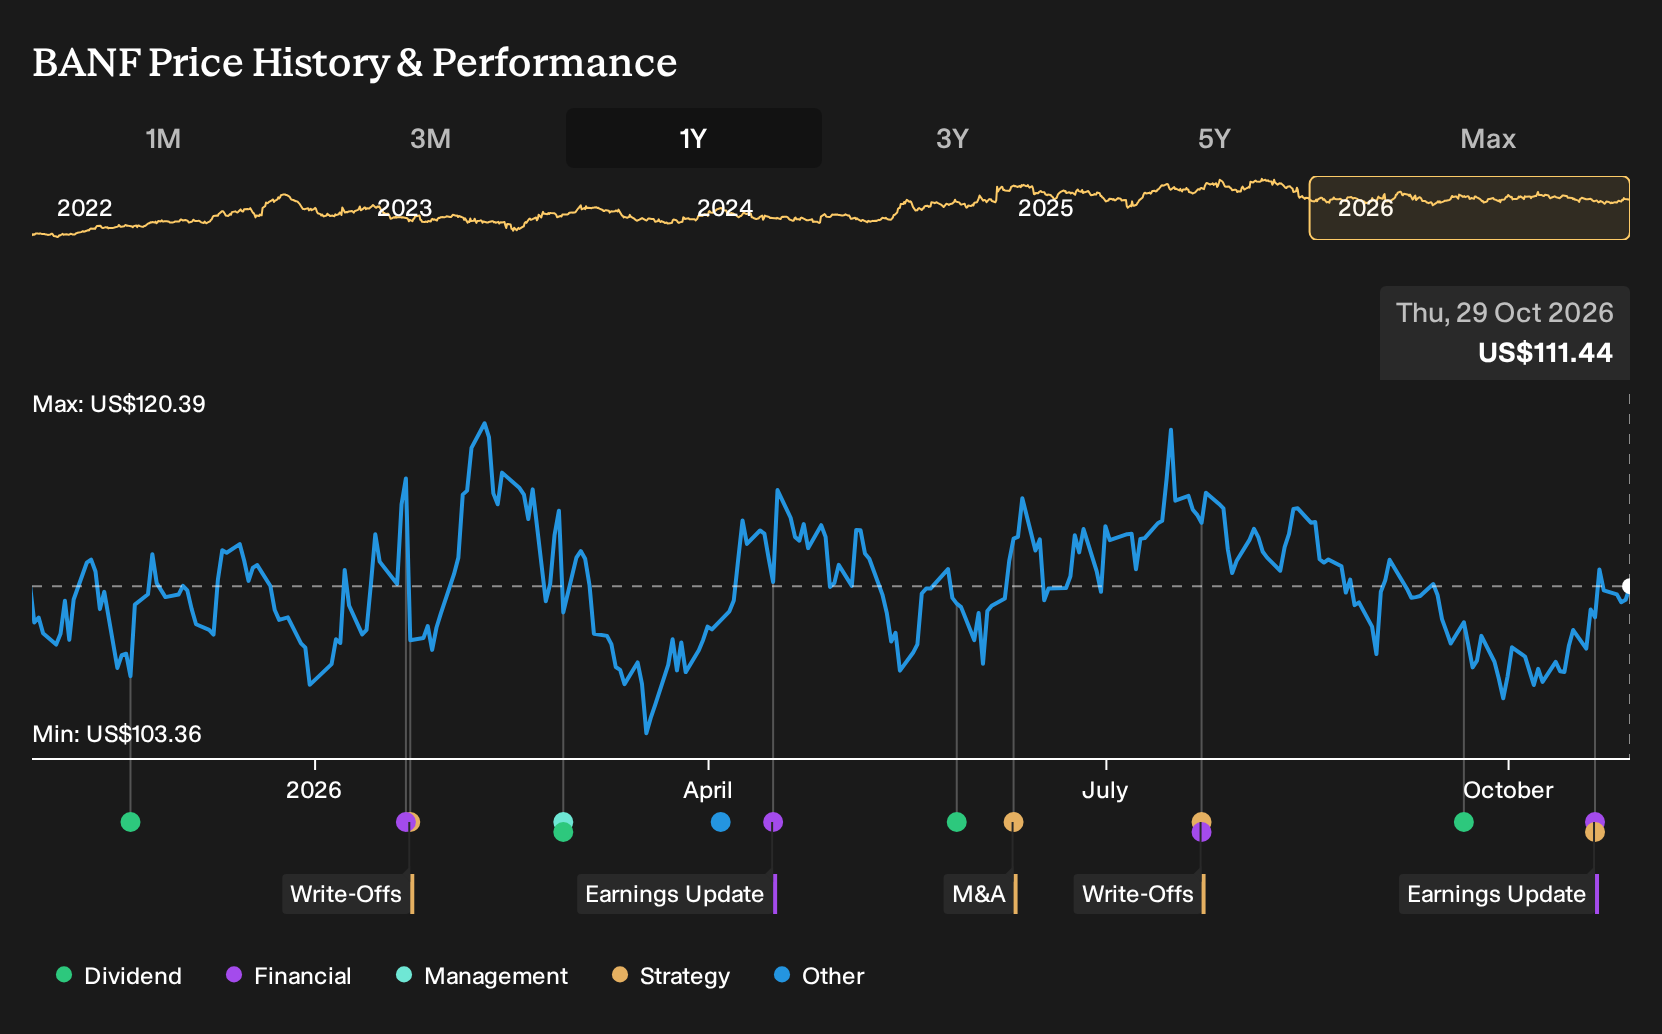
- BancFirst reported third quarter 2026 net income of US$67.25 million and basic EPS from continuing operations of US$2, with year-to-date net income of US$196.94 million and basic EPS of US$5.86, alongside higher quarterly net charge-offs of US$4.0 million.
- The combination of rising earnings and increased net charge-offs highlights how BancFirst is balancing profitability with evolving credit costs across its loan portfolio.
- We will look at how BancFirst's stronger earnings per share profile influences the investment narrative that analysts outlined before this update.
Compare BancFirst's latest earnings and credit trends with a curated 30 resilient stocks with low risk scores that also aims to balance profit with tighter control of loan losses.
BancFirst Investment Narrative Recap
To own BancFirst, you need to be comfortable with a slower growth profile that leans heavily on consistent profitability, strong capital and disciplined lending rather than big revenue leaps. The latest quarter fits that story. Earnings per share from continuing operations reached US$2, while year to date EPS rose to US$5.86, so the near term earnings engine still looks intact.
The sharper rise in net charge offs to US$4.0 million keeps credit quality front and center for the next few quarters. For now, the move looks manageable relative to earnings. As a result, the core near term catalyst remains how efficiently BancFirst integrates its Tulsa expansion while holding the efficiency ratio and net margins in check.
The most relevant update here is the third quarter 2026 earnings release. Net income of US$67.25 million for the quarter and US$196.94 million for the first nine months shows that BancFirst is still generating meaningful profit while absorbing higher loan losses. That mix matters for a bank that already trades at a premium P/E to peers.
Higher charge offs alongside solid earnings put the focus on execution. Investors watching BancFirst will likely track whether future quarters keep this balance between profitability and credit costs, especially as analysts have flagged only moderate expected revenue and earnings growth. Any drift in costs or credit metrics could affect how much investors are willing to pay for that quality profile.
What The Analyst Scenario Implies For BancFirst
BancFirst's narrative projects US$874.9 million in revenue and US$286.7 million in earnings by 2029. This scenario assumes 7.0% yearly revenue growth and an earnings increase of about US$34.9 million from the current US$251.8 million level.
Uncover why BancFirst's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for BancFirst from 2 members of the Simply Wall St Community cluster tightly between about US$122.33 and US$124.33, so you are not seeing extreme bargain or bubble calls here. Those views were formed before the higher net charge offs and Tulsa expansion updates, which gives you a reason to compare multiple viewpoints and reassess how earnings resilience and credit costs could influence your own expectations.
Explore another BancFirst fair value estimate, including one that suggests it could be worth just $122.33.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BancFirst research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BancFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BancFirst's overall financial health at a glance.
Looking For More Investment Ideas Beyond BancFirst?
If BancFirst has sharpened your focus on quality and risk, use that same lens to scan wider across the market. The Simply Wall St Screener lets you filter for different strengths so you can build a watchlist that matches how you think about earnings durability, dividends and balance sheet resilience.
- If income consistency matters to you, start with companies aiming to deliver solid regular payouts through the 7 dividend fortresses.
- If long term value is your priority, look for resilient businesses trading below what their fundamentals might justify by scanning the 30 high quality undervalued stocks.
- If financial strength is non negotiable, focus on companies with cleaner balance sheets and sturdier fundamentals using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com