
How Upcoming Earnings At EPAM Systems (EPAM) Has Changed Its Investment Story
- EPAM Systems is set to report quarterly results for the September 2026 period, with consensus expectations of earnings of $3.41 per share on revenue of $1.42b, which would represent year over year improvements in both metrics based on analyst estimates available at the time.
- The market focus sits on the tension between an expected 10.7% EPS uplift and only 1.7% revenue growth. This highlights how much of EPAM Systems' near term story now rests on mix, efficiency and margin quality rather than headline top line expansion.
- We will now look at how EPAM Systems' expected 10.7% EPS uplift could influence the existing investment narrative around AI led work.
EPAM Systems Investment Narrative Recap
To own EPAM Systems, you need to believe the business can keep tilting its work toward higher value AI native and consulting heavy projects while keeping delivery efficient across regions. The expected 10.7% uplift in EPS with only 1.7% revenue growth reinforces that margins and mix remain the key short term catalyst rather than top line acceleration.
The biggest near term risk is that slow client decision making, weak task based demand in North America, and working capital pressure keep a lid on both revenue growth and free cash flow. The updated earnings expectations do not materially change that risk balance; they mostly sharpen the focus on execution quality.
Recent commentary around AI native work contributing more than 11% of revenue and growing at double digit sequential rates is the clearest operational link to the current earnings setup. If that type of work keeps gaining share, the expected EPS improvement for the September quarter would sit neatly alongside the margin gains seen earlier in 2026.
EPAM Systems is also leaning on partnerships, including its OpenAI Advanced Partner agreement and applied AI work with Anthropic, to support this shift. These relationships matter for the catalyst roadmap because they underpin larger, more complex programs and potential vendor consolidation deals while also raising the execution bar if demand softens anywhere else in the portfolio.
EPAM Systems Long Term Assumptions To Watch
EPAM Systems' narrative projects revenues of US$6.3b and earnings of US$538.7 million by 2029. That profile rests on analysts baking in 4.2% yearly revenue growth and an earnings uplift of about US$137 million from the current US$401.7 million base.
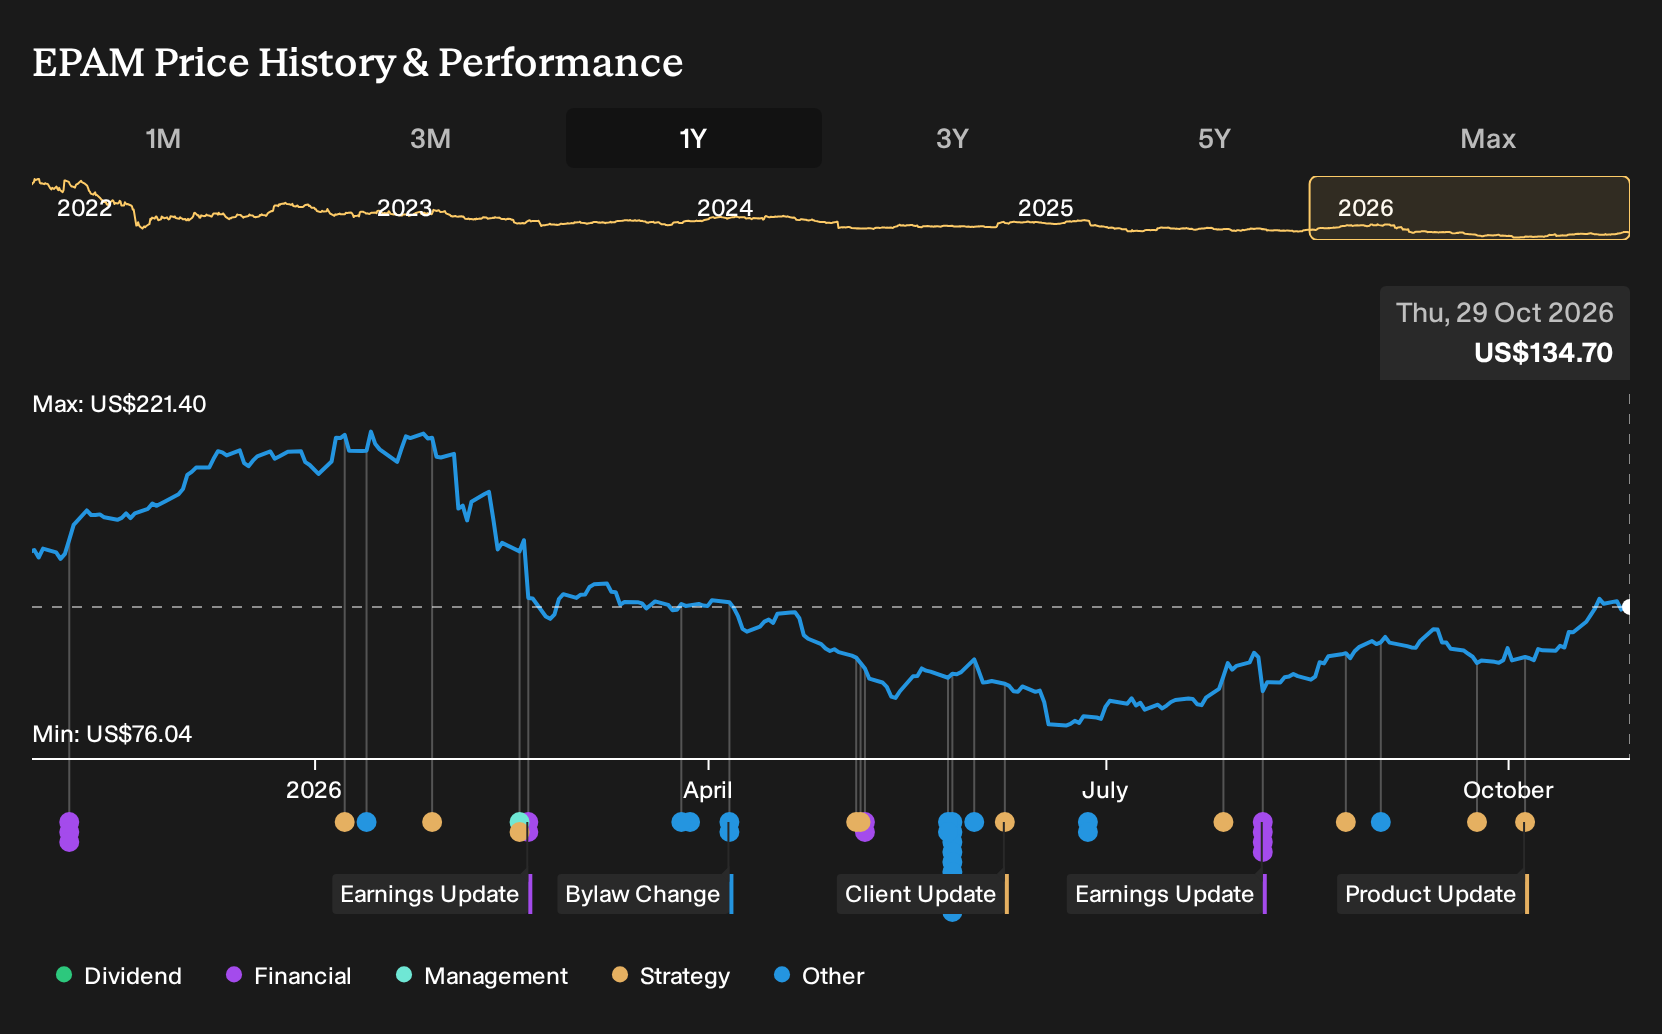
Uncover why EPAM Systems' fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One contrasting angle around EPAM Systems is pricing power in North America. The most cautious analysts were already assuming only 3.2% annual revenue growth and about US$531.6 million of earnings by 2029, compared with the higher consensus path. That is a much tougher story. Use this earnings print to test which version you find more convincing.
Explore 5 other EPAM Systems fair value estimates, including one that suggests as much as 21% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EPAM Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for EPAM Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPAM Systems' overall financial health at a glance.
Looking For More EPAM Systems Style Investment Ideas?
Once the EPAM Systems story is on your radar, it often helps to widen the search to other companies with similar return profiles, different risk trade offs, or stronger balance sheets. The Simply Wall St Screener can help you quickly surface a handful of candidates that match the type of earnings and quality mix you are looking for.
- If you care most about quality at a reasonable entry point, start by scanning the market for companies that look mispriced on fundamentals using our 30 high quality undervalued stocks.
- For readers who want resilience front and center, focus on businesses with stronger financial positions and more conservative leverage through the list of solid balance sheet and fundamentals (23 results).
- If dependable income is a priority, concentrate on cash generators offering higher yields and payout support using the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com