
How Raised Earnings Guidance At IDACORP (IDA) Has Changed Its Investment Story
- IDACORP reported third quarter 2026 revenue of US$608.04 million and net income of US$160.21 million, with diluted earnings of US$2.73 per share. The company also posted higher earnings for the first nine months of the year compared with the same period in 2025.
- The utility raised its full year 2026 earnings guidance to a range of US$6.40 to US$6.50 per diluted share, highlighting that customer growth, rate driven revenues, and large contract users are contributing to reported profitability, while battery storage and grid projects progress in the background.
- We will now examine how IDACORP's raised full year earnings guidance could influence the existing investment narrative built around capital spending.
Scan how IDACORP's upgraded outlook compares with other regulated utilities making similar grid and storage investments by reviewing the hand picked 43 power grid technology and infrastructure stocks in one place.
IDACORP Investment Narrative Recap
To own IDACORP, you need to be comfortable with a regulated utility leaning into heavy grid, storage and generation spending while relying on continued load growth from households and large industrial users. The upgraded full year earnings guidance suggests the operating environment is currently supportive, although it does not fundamentally change that long term capex story.
The near term swing factor remains execution on large customer contracts and timely cost recovery on that US$1.3b to US$1.5b annual spend. The biggest risk still sits with hydropower variability and regulatory pushback on rates, and the latest results do not materially reduce either exposure.
The raised 2026 earnings guidance to US$6.40 to US$6.50 per diluted share is the announcement that matters most for this update. It links directly to higher current year profitability at IDACORP and confirms that customer growth, rate driven revenue and large contract usage are flowing through the income statement.
For catalysts, that guidance range frames how much earnings headroom IDACORP has while it pushes ahead with battery storage, transmission and generation projects. It also highlights the role of the Idaho earnings support tax credit mechanism, since management now expects to use less than US$10 million of extra credits if conditions stay in line with assumptions.
What IDACORP's Long Term Forecasts Assume
Analyst models around IDACORP lean heavily on a story of rising scale and fatter profit margins. The consensus view bakes in revenue growth of 11.5% a year over the next three years and assumes the profit margin steps up from 18.8% today to 21.0% by around 2029. That combination pairs higher grid and generation spending with an expectation that a larger regulated rate base and growing large customer usage support more profitable operations over time.
Earnings forecasts sit at the center of this narrative. Analysts are looking for IDACORP to move from US$338.6 million of earnings today to US$525.8 million by 2029, with the most optimistic projections running as high as US$589.4 million. That implies an earnings increase of roughly US$187 million across the period. For you as an investor, the important point is that the projected jump in profit ties back to both customer growth and successful conversion of the capital plan into allowed returns.
The assumptions do not stop at the income statement. Forecasts include 7.0% yearly growth in share count for the next three years as equity raises help fund grid, storage and generation projects. That means headline earnings growth is being asked to work harder to offset a larger share base. It also means any per share outcome you focus on, such as the US$8.15 earnings per share figure implied by the 2029 estimate, is closely linked to how management sequences spending, rate cases and equity issuance.
How The IDACORP Valuation Ties Back To 2029
Current analyst valuation work anchors to a specific future snapshot. For the consensus price target to hold, forecasts assume IDACORP reaches US$2.5b of revenue and US$525.8 million of earnings in 2029, with the stock trading on a P/E of 25.2x at that point. Those valuation multiples compare with a current P/E of 24.3x for IDACORP and a sector P/E of 20.3x for US electric utilities. The framework effectively prices the company as a relatively higher multiple utility whose capital plan and earnings mix merit a premium to the wider peer group.
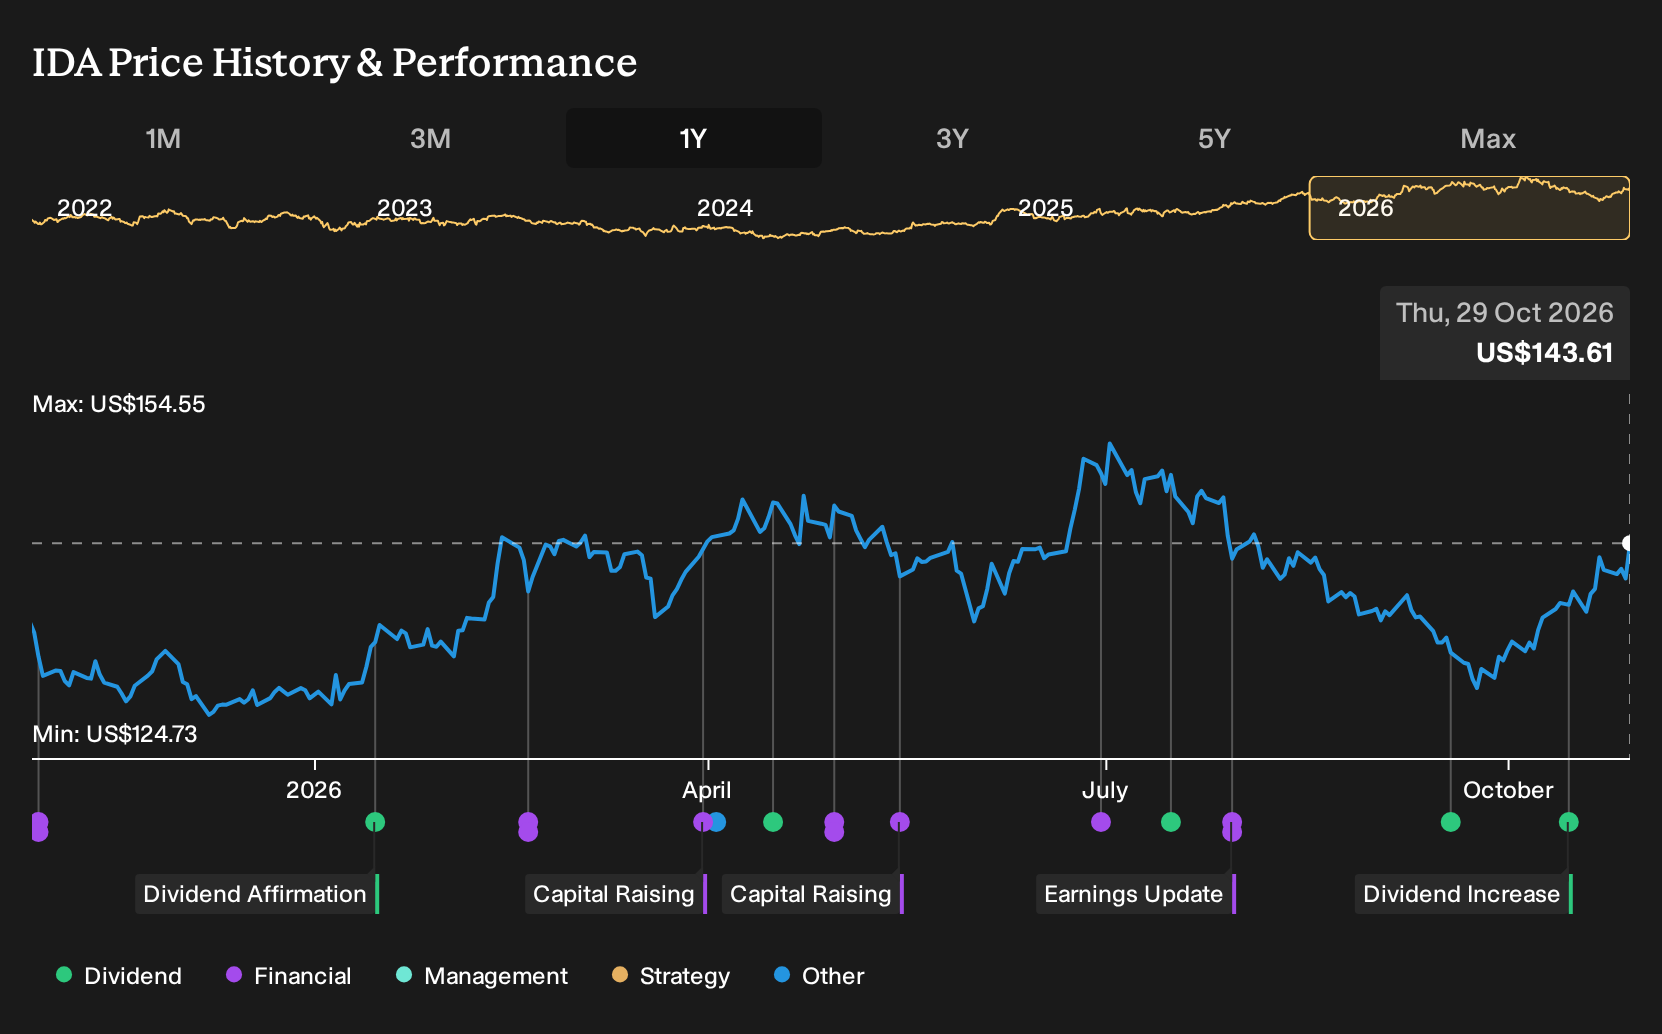
The price targets also rest on only a modest gap to where IDACORP trades today. With a consensus target of US$151.44 against a current share price of US$142.06, analysts see about 6.2% upside embedded in their models. That narrow spread suggests they broadly view the stock as close to fairly valued on their assumptions. For you, the practical takeaway is that any disagreement with those 2029 revenue, earnings or P/E assumptions quickly translates into a different view on what the shares are worth.
Model inputs include an assumed discount rate around 7.2% to 7.24% when translating those 2029 cash flows and earnings back to present value. That rate reflects both business specific risks such as hydropower variability and regulatory timing, and a return hurdle analysts use across the regulated utility space. If your required return is higher or lower than 7% to 8%, your own estimate of what constitutes a reasonable entry price for IDACORP could diverge meaningfully from the consensus target.
IDACORP's narrative projects US$2.5b revenue and US$525.8 million earnings by 2029. This requires 11.5% yearly revenue growth and an earnings increase of about US$187 million from US$338.6 million today.
Uncover why IDACORP's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$114 to US$151, with some members seeing IDACORP as materially undervalued while others cluster near the current analyst target. You can weigh those retail views against hydropower, regulatory and large contract risks, all of which could shift how future earnings play out.
Explore 2 other IDACORP fair value estimates, including one that suggests up to 5% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your IDACORP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for IDACORP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDACORP's overall financial health at a glance.
Looking For More Investment Ideas Beyond IDACORP?
If the IDACORP story has sharpened your thinking about regulated utilities, you can broaden that momentum into a wider watchlist using the Simply Wall St Screener. You can filter for different risk, income and quality profiles, then line those results up against what you have just seen here.
- For investors who want potential upside with a margin of safety, consider scanning a curated set of 30 high quality undervalued stocks that pair stronger fundamentals with discounted share prices.
- If capital preservation and steadier profiles matter more to you, focus on a 30 resilient stocks with low risk scores that concentrates on businesses with lower risk scores and more resilient balance sheets.
- When you want quality first and foremost, build a watchlist from a 18 high quality undiscovered gems that screens for solid fundamentals in companies that are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com