
Plug Power (PLUG) After Its Engineering Hire And The Debate Over Fair Value
Plug Power (PLUG) has put engineering execution in the spotlight with the appointment of Dr. Lee Sweetland as Global Engineering Industrialization Lead, a move aimed at tightening its hydrogen manufacturing and fuel cell stack operations.
For Plug Power shareholders, the recent appointment comes against a bruising backdrop, with the 30-day share price return down 26.8% and the year-to-date share price return down 36.32%, while the 1-year total shareholder return has fallen 47.21% and the 5-year total shareholder return has dropped 96.3%. This points to fading long-term momentum, despite a small 7-day share price rebound of 2.9%.
Scan beyond Plug Power and examine other hydrogen and clean energy players using our hand picked screener of 30 resilient stocks with low risk scores to compare balance sheet strength.
Plug Power now trades at a fraction of its past market value, even after the recent appointment reset the engineering story. Is most of the re rating already spent, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 60% Undervalued
Plug Power last closed at $1.42, while the most followed narrative frames fair value at $3.55. This suggests a wide gap that hinges on execution in hydrogen production, liquidity moves, and future margins.
Operational improvements such as gross margin enhancements from Project Quantum Leap, restructuring, facility consolidation, and favorable hydrogen supply agreements are already yielding sharply better margins and targeting breakeven gross margin by Q4, which can lead directly to improved net margins and earnings.
See why 204 investors see Plug Power as 60% undervalued.
Result: Fair Value of $3.55 (UNDERVALUED)
Still, this Plug Power story rests on fragile supports, with ongoing losses and liquidity pressure both capable of quickly undermining the case for a 60% undervaluation.
Find out about the key risks to this Plug Power narrative.
Another Lens On Plug Power’s Valuation
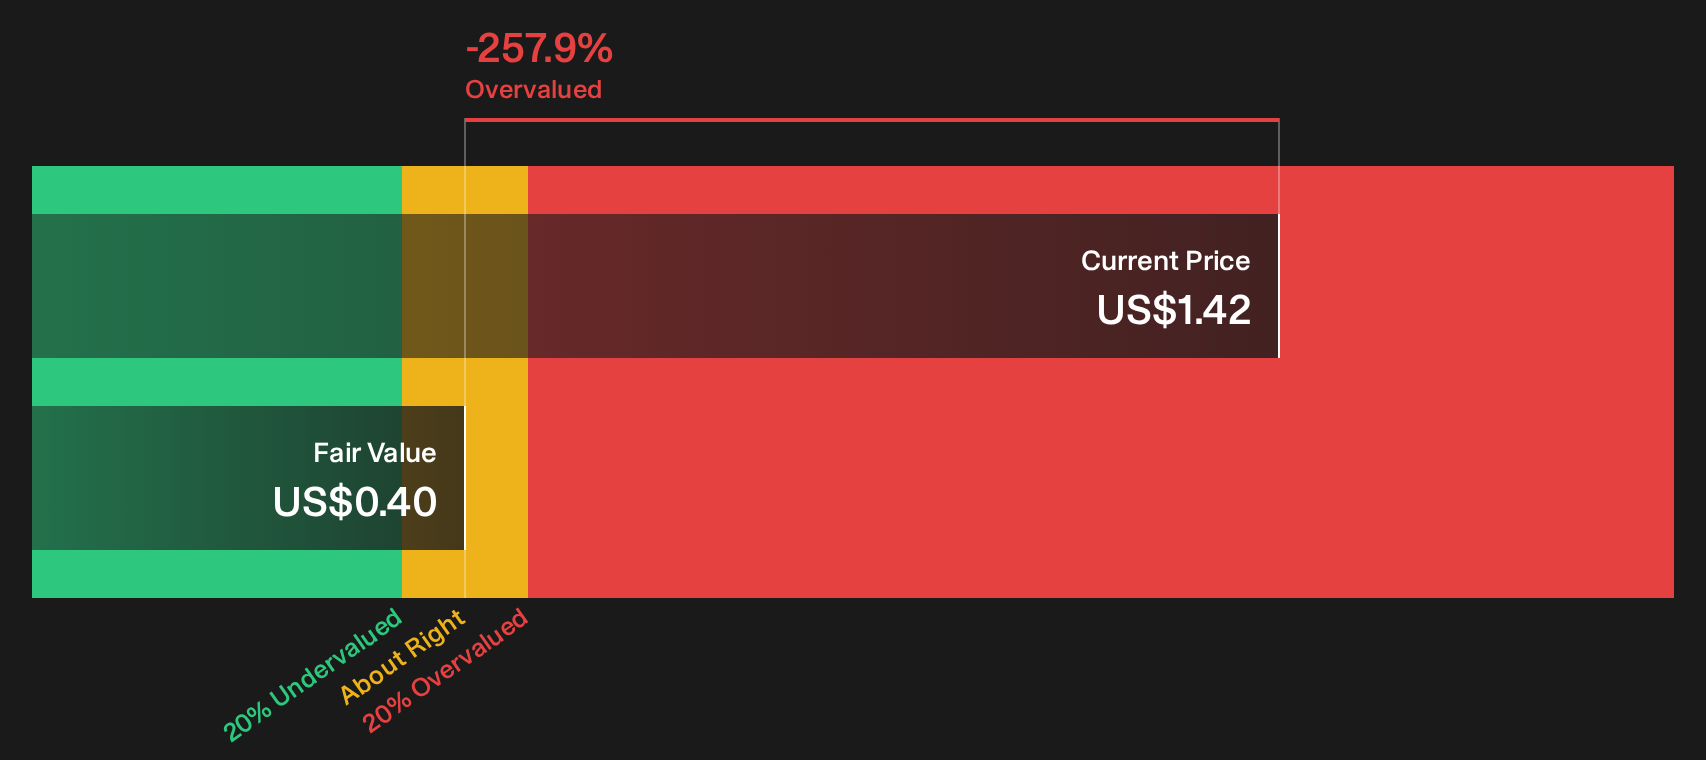
The analyst narrative points to Plug Power trading around a 60% discount to an implied fair value of $3.55, based on future earnings and margin repair. Our DCF model presents a very different perspective. It places fair value closer to $0.40, which suggests the shares appear expensive on that framework.
That gap raises a simple question: Is the market underestimating Plug Power’s ability to convert hydrogen projects into durable cash flow, or is the upbeat narrative extending further than the future cash can realistically support?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Plug Power can either paralyze you or push you to test the arguments yourself and move quickly while sentiment is unsettled. To weigh the tension between concerns and potential upside, start with the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Plug Power?
If Plug Power has sharpened your focus on risk, reward, and execution, broaden your watchlist with other ideas that match clear financial filters and disciplined criteria.
- Target stability first and see which companies pass our balance sheet stress tests with the list of solid balance sheet and fundamentals (23 results).
- Hunt for upside potential by filtering for companies that combine quality fundamentals with pricing that looks appealing in our 30 high quality undervalued stocks.
- Build a cash flow anchor for your portfolio by zeroing in on income ideas inside the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com