
Paychex Earnings Preview: What to Expect
Rochester, New York-based Paychex, Inc. (PAYX) is a human capital management (HCM) and payroll services provider with a market capitalization of approximately $38.9 billion. The company offers cloud-based solutions that help businesses manage their workforce, payroll, employee benefits, retirement plans, and HR operations. Its competitive strengths include deep regulatory expertise, a broad customer base, and long-standing client relationships. Paychex is also investing in artificial intelligence, automation, and workforce analytics to improve its services and streamline business operations.
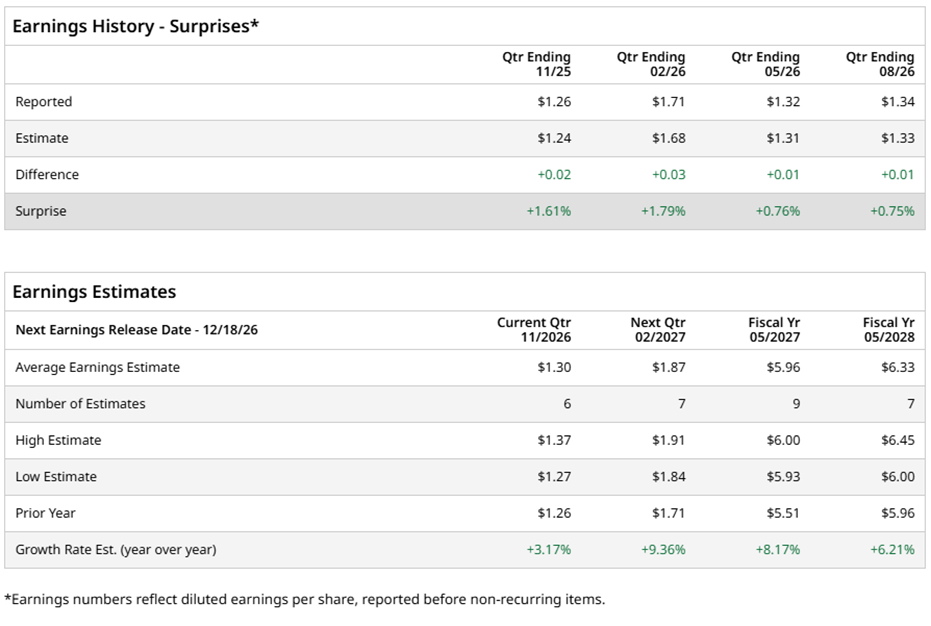
The industry-leading HCM company is expected to announce its fiscal second-quarter earnings for 2027 in the near term. Ahead of the event, analysts expect Paychex to report a profit of $1.30 per share on a diluted basis, up 3.2% from $1.26 per share in the year-ago quarter. Paychex has also built a solid track record, beating analysts’ EPS estimates in each of its last four quarterly reports.
For the full year, analysts expect Paychex’s EPS to be $5.96, up 8.2% from $5.51 in fiscal 2026. Looking further ahead, its EPS is expected to rise by another 6.2% year over year (YOY) to $6.33 in fiscal 2028.
PAYX stock is down 6.8% over the past 52 weeks, notably underperforming the S&P 500 Index’s ($SPX) 12% gains over the same period. Similarly, PAYX is also lagging behind the State Street Technology Select Sector SPDR ETF’s (XLK) 24.1% gains over the past year.
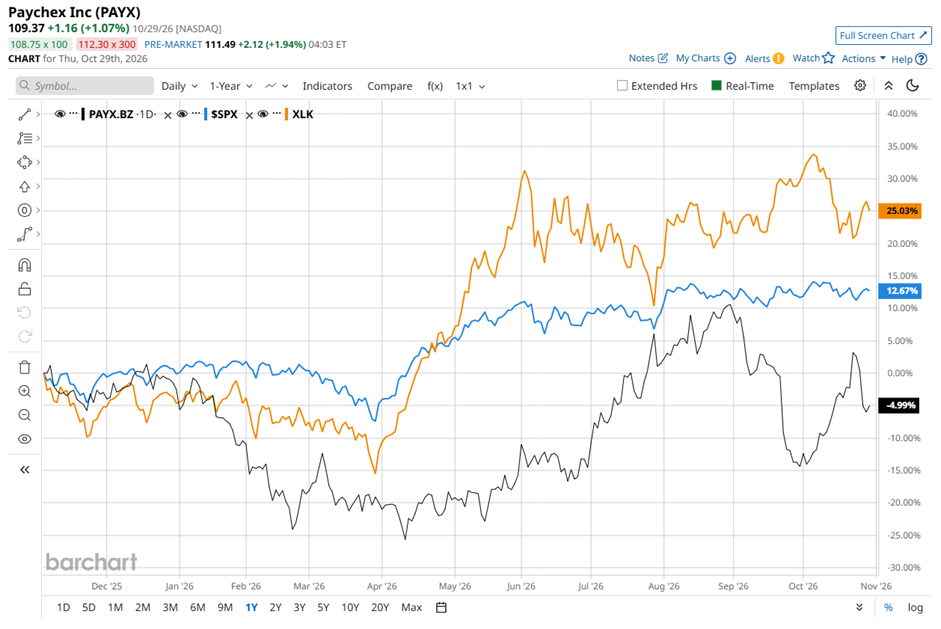
Paychex’s shares have faced pressure as investors weigh steady earnings growth against signs of slowing business momentum. The shares came under sharp selling pressure in September, falling about 9% after the company released its fiscal Q1 2027 results on Sept. 23. While revenue increased 6% annually to $1.6 billion and adjusted EPS rose 10% YOY to $1.34, revenue was largely in line with expectations, offering little upside surprise.
Growth across its businesses was mixed. Management Solutions revenue increased 4%, while PEO and Insurance Services delivered stronger 12% growth. However, softer hiring activity and fewer new business formations among small and mid-sized companies have weighed on payroll volumes. Rising costs and concerns about margin pressure have also added to the cautious sentiment, alongside lower analyst price targets following the earnings report.
The company’s unchanged full-year guidance, projecting 5% to 6% revenue growth and 7% to 9% adjusted EPS growth, provided limited fresh momentum. Cash flow and the pace of share buybacks have also drawn attention.
On the positive side, Paychex is expanding its technology offering. Its AI-powered WISE platform became available through Microsoft 365 Copilot and Teams in August, adding another distribution channel for its workforce management solutions.
Analysts remain measured on PAYX, with a consensus rating of “Hold.” Out of 20 analysts covering the stock, two recommend a “Strong Buy,” 16 give a “Hold,” and two advise a “Strong Sell.” PAYX’s average analyst price target is $114.93, indicating potential upside of 4.6% from the current level.
On the date of publication, Sristi Suman Jayaswal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.