
Do Stronger Earnings Change The Bull Case For Zions Bancorp Stock (ZION)?
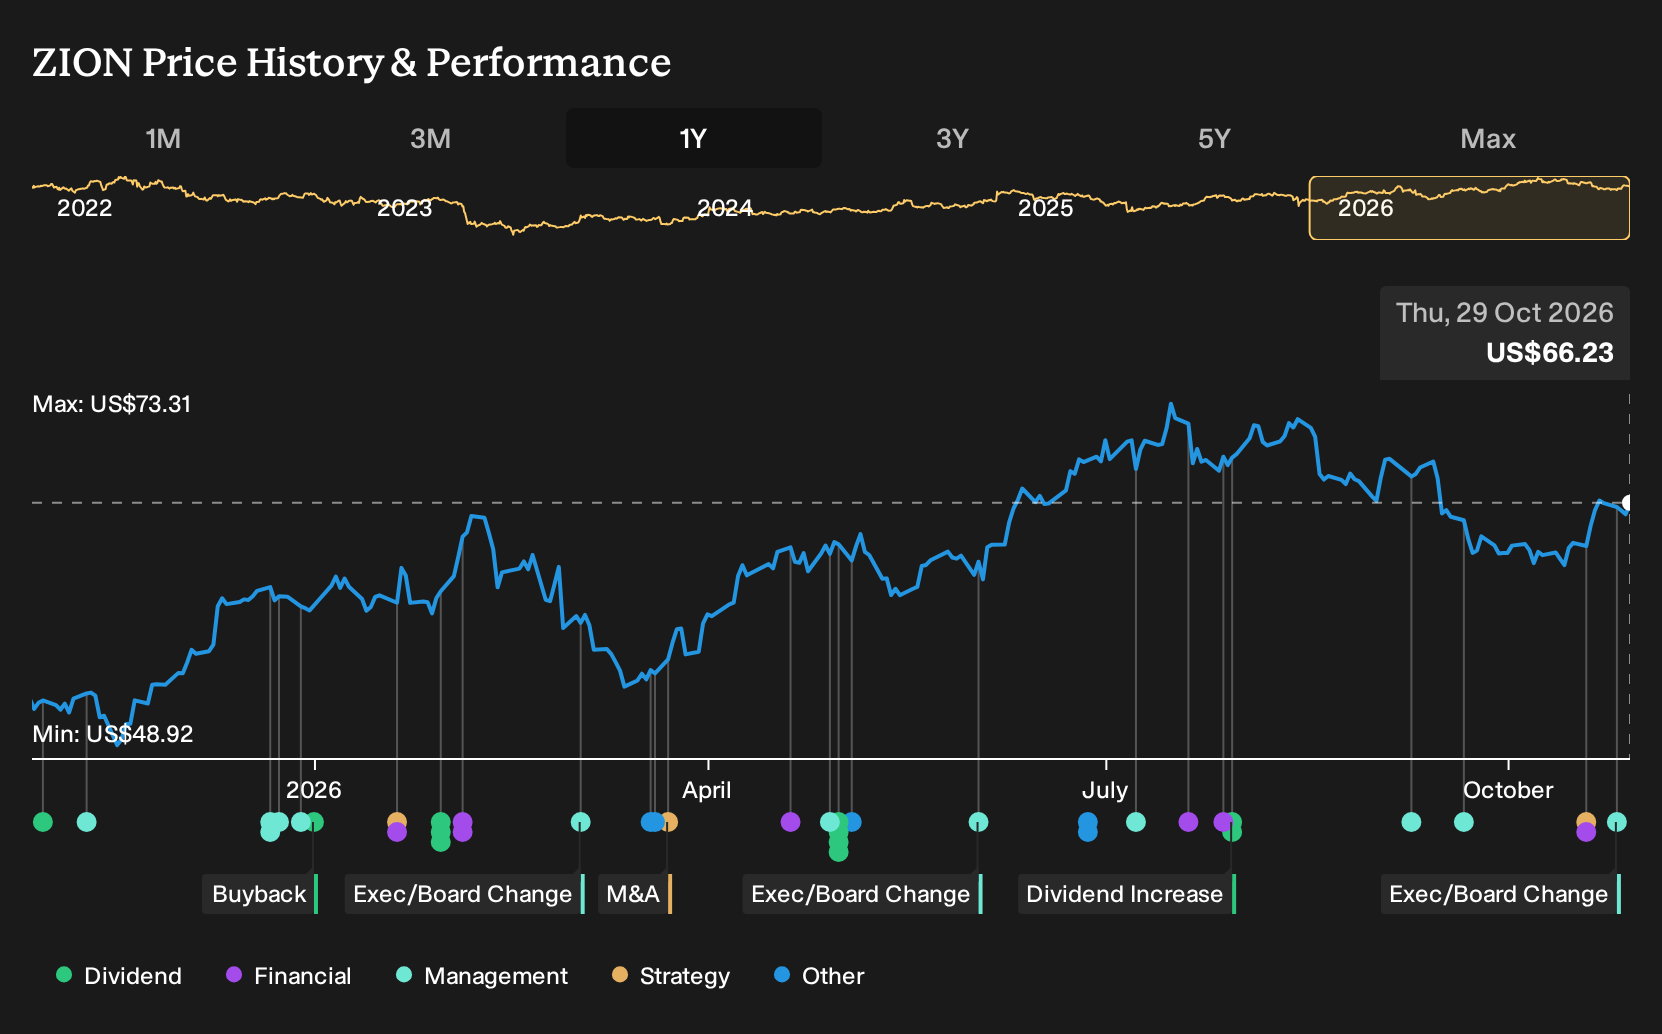
- Zions Bancorporation, National Association recently reported third quarter 2026 results that showed net interest income of US$684 million and net income of US$263 million, alongside much lower net charge offs of US$3 million compared with US$56 million a year earlier.
- Management also completed a US$150 million share repurchase program and appointed Michael MacDonald as President of California Bank & Trust, while he continues to lead Zions Capital Markets. This concentrates more leadership influence over both core commercial banking and fee based capital markets activity.
- We will now look at how Zions Bancorporation's stronger earnings and sharply lower net charge offs could reshape its broader investment narrative.
Scan beyond Zions Bancorporation National Association and compare its latest earnings and credit trends with a curated list of solid balance sheet and fundamentals (23 results) to see how other financially robust banks stack up.
Zions Bancorporation National Association Investment Narrative Recap
To own Zions Bancorporation National Association, you need to be comfortable with a regional commercial bank that leans heavily on Western US economies, funding discipline and gradual efficiency gains. The latest quarter supports that story, with higher net interest income of US$684 million and net income of US$263 million, plus very low net charge offs of US$3 million.
The near term swing factor still looks like deposit pricing and loan quality. Intense competition for funding could squeeze net interest income, while any weakness in Western real estate or commercial credit would test today’s clean loss numbers. The sharp drop in net charge offs helps, but does not remove that risk.
The appointment of Michael MacDonald as President of California Bank & Trust, while he continues to lead Zions Capital Markets, ties together two important earnings drivers. Commercial and corporate banking in California and fee based capital markets activity now report through one leader, which can matter for how cross selling and risk appetite play out.
For you, the question is whether this leadership structure improves execution on existing catalysts, such as commercial loan growth, fee income expansion and tighter cost control, without loosening credit standards. If MacDonald coordinates product, coverage and capital markets effectively, Zions Bancorporation National Association could deepen relationships with West Coast clients, though concentration in those same markets remains a key exposure.
Zions Bancorporation National Association's narrative projects US$3.8b revenue and US$949.6 million earnings by 2029. This assumes revenue growth of 1.3% per year and an earnings decline of about US$250 million from current earnings of US$1.2b.
Uncover why Zions Bancorporation National Association's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from about US$72.73 to an extremely high US$44,072.55, which shows just how far apart retail views on Zions Bancorporation National Association can sit. When you set those gaps against risks around Western US credit conditions and deposit competition, you are looking at very different paths for future performance.
Explore 2 other Zions Bancorporation National Association fair value estimates, including one that suggests it could be worth just $72.73.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zions Bancorporation National Association research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zions Bancorporation National Association. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zions Bancorporation National Association's overall financial health at a glance.
Looking for more investment ideas beyond Zions Bancorporation National Association?
If Zions Bancorporation National Association has sharpened your focus on balance sheet strength and risk control, it can help to widen your search across other companies with different income profiles, payout policies and volatility patterns.
- For income focused portfolios that aim to combine yield with resilience, review a curated set of higher yielding companies through the 7 dividend fortresses.
- If capital preservation and smoother return profiles matter most to you, narrow your watchlist by scanning a 30 resilient stocks with low risk scores that scores well on financial soundness.
- When you want to cast the net wider and spot opportunities that are not heavily followed, sift through a 18 high quality undiscovered gems that pair solid fundamentals with thinner coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com