
SolarEdge Technologies (SEDG) Climbed, What Is Behind The Attention Now?
SolarEdge Technologies (SEDG) heads into its November 4 earnings release with attention centered on one question: Can expected earnings growth, paired with softer revenue, validate the recent shift in analyst sentiment around the stock?
Recent trading sums up the mixed mood around SolarEdge Technologies. The share price gained 3.54% over the last day but fell 8.36% across the past week and is down 25.89% on a 90 day share price return, while the 5 year total shareholder return has declined 91.13%. This points to fading long term momentum despite short bursts of optimism ahead of earnings.
Scan hand-picked alternatives to SolarEdge Technologies that currently screen as 30 high quality undervalued stocks with stronger recent share price trends and different earnings set ups.
For SolarEdge Technologies, a sharp rebound into earnings after a long slide raises a simple tension. Is this the start of a rebuild in value, or has most of the easy upside already played out in the price ahead of the valuation work?
Most Popular Narrative: 21% Undervalued
The most followed narrative on SolarEdge Technologies puts fair value at $38.45 per share, above the last close of $30.54. This frames upcoming earnings against a valuation gap that hinges on policy support, storage demand, and execution risk.
The rally in SolarEdge's stock appears to be pricing in robust future revenue growth driven by U.S. policy support (extension of manufacturing and storage credits). However, risks are rising as the elimination of the 25D residential solar tax credit is expected to cause a substantial drop in U.S. residential demand in 2026, only partially offset by third-party owned (TPO) shifts, potentially constraining topline growth.
See why 56 investors see SolarEdge Technologies as 21% undervalued.
Result: Fair Value of $38.45 (UNDERVALUED)
Still, two things could flip that 21% undervalued story for SolarEdge Technologies on its head: softer U.S. residential demand and fiercer inverter pricing pressure.
Find out about the key risks to this SolarEdge Technologies narrative.
Another View: SEDG Through The DCF Lens
Analyst narratives put SolarEdge Technologies at a fair value of $38.45 per share, which points to an undervalued story. The SWS DCF model tells a different tale. At $30.54, the stock sits above an estimated future cash flow value of $28.16, implying limited upside through that lens.
That gap between a higher narrative fair value and a lower DCF outcome leaves a simple question for investors: Which set of assumptions feels closer to how SolarEdge Technologies can realistically convert its pipeline into cash generation over time, and which one feels too optimistic for current conditions?
Look into how the SWS DCF model arrives at its fair value.
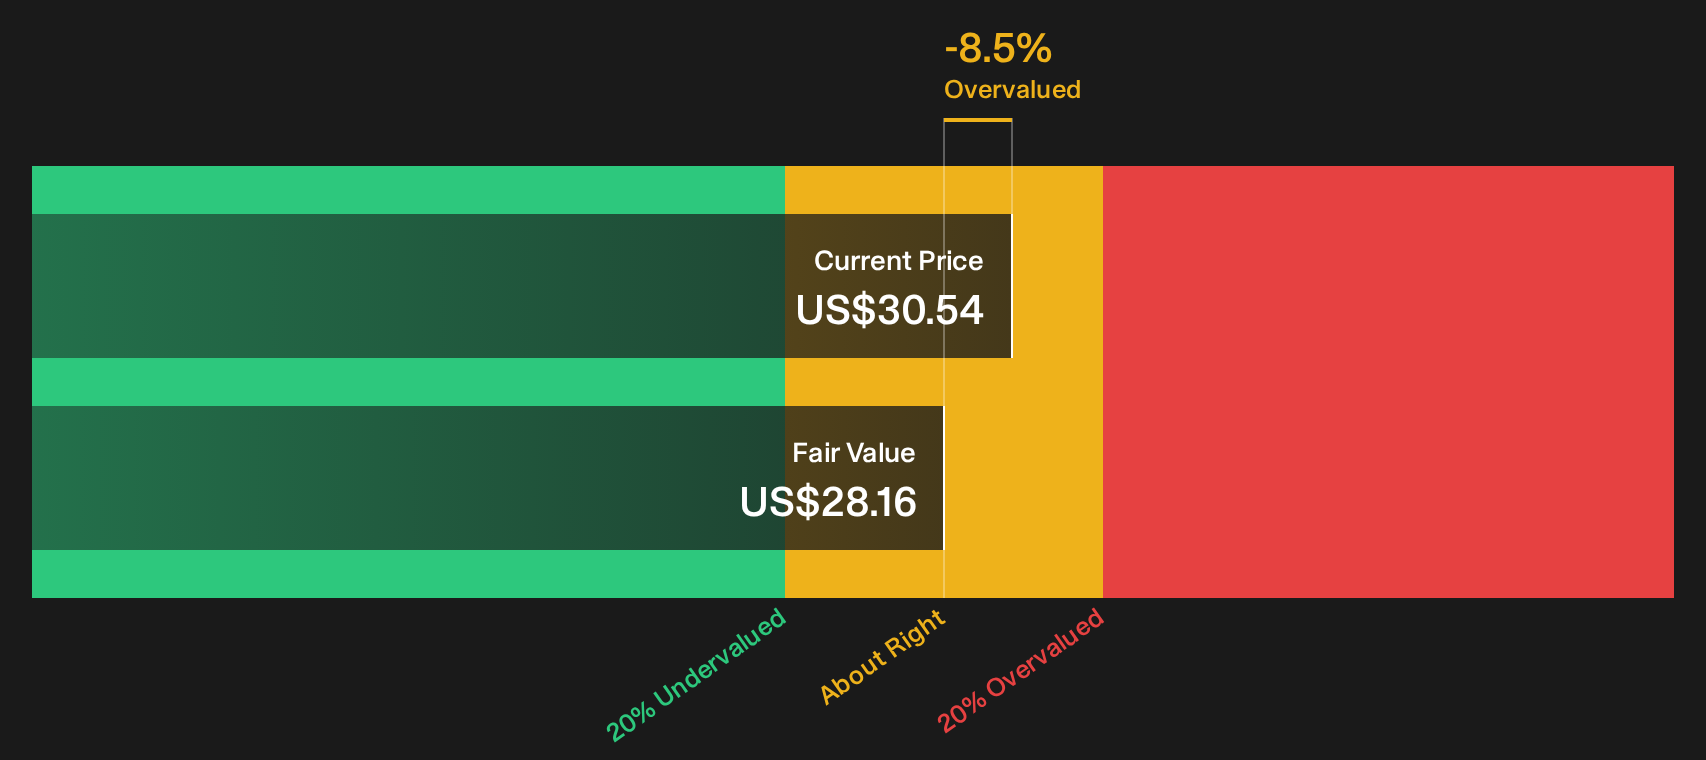
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SolarEdge Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on SolarEdge Technologies so far. If you want to move fast and form your own view, start by weighing the 2 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond SolarEdge Technologies?
If you stop with SolarEdge Technologies, you risk missing other setups that might suit your style better, so keep scanning and widen your opportunity set.
- Target stability first and stress test your watchlist against 30 resilient stocks with low risk scores that currently combine resilience with more balanced risk profiles.
- Spot mispriced potential and review the 18 high quality undiscovered gems that pair strong fundamentals with lighter market attention.
- Prioritise financial strength and build a shortlist from the list of solid balance sheet and fundamentals (23 results) to anchor your portfolio with sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com