
Frontier Stock Faces A Profit Test After Revenue Growth And Wider Q3 Loss
- Frontier Group Holdings reported third quarter 2026 results with revenue of US$1,355 million and a net loss of US$104 million, with wider losses for the nine month period.
- The airline is showing strong top line momentum while losses deepen, which may highlight pressure on costs, pricing, or both within its ultra low fare model.
- We will examine how Frontier Group Holdings' investment narrative focused on low cost leisure travel compares with rising losses alongside much higher revenue.
Scan the ultra low cost airline space for peers dealing with similar revenue strength and profit pressure by reviewing our curated 30 high quality undervalued stocks list built for this kind of setup.
Frontier Group Holdings Investment Narrative Recap
To own Frontier Group Holdings, you need to believe its ultra low fare model can translate strong demand into a path toward profitability without losing its cost edge. The latest quarter reinforced that tension. Revenue reached US$1,355 million, yet the airline still reported a net loss of US$104 million, with losses for the nine month period widening materially.
Over the next stretch, the main near term swing factor is whether Frontier can convert higher sales into better unit economics through tighter capacity, higher load factors, and sturdier ancillary revenue, while keeping non fuel costs in check. The biggest risk is that fixed costs, surplus capacity, and a leisure heavy customer base keep profitability out of reach and strain cash generation.
The third quarter 2026 earnings release is the key update to focus on. Frontier Group Holdings reported US$1,355 million in revenue versus US$886 million a year earlier, and a quarterly net loss that widened to US$104 million from US$77 million. For the nine months, revenue reached US$3,626 million, while the net loss expanded to US$466 million from US$190 million.
Those figures keep the spotlight on execution. Higher sales give Frontier more room to spread fixed costs, yet the deeper losses underline how sensitive the model is to oversupply, off peak demand, and rising labor and maintenance expenses. For investors tracking catalysts, progress on load factors, non fare revenue per passenger, and cost per seat will likely matter more than headline growth in ticket sales.
Frontier Group Holdings is modeled to reach US$6.1b in revenue and US$292.1 million in earnings by 2029, based on analysts' forecasts. That profile assumes revenue growth of 17.2% per year and an increase in earnings of about US$658 million from the current earnings of a US$366 million loss to the projected profit level.
Uncover why Frontier Group Holdings' fair value indicates a 3% potential upside to its current price before the market closes that discount.
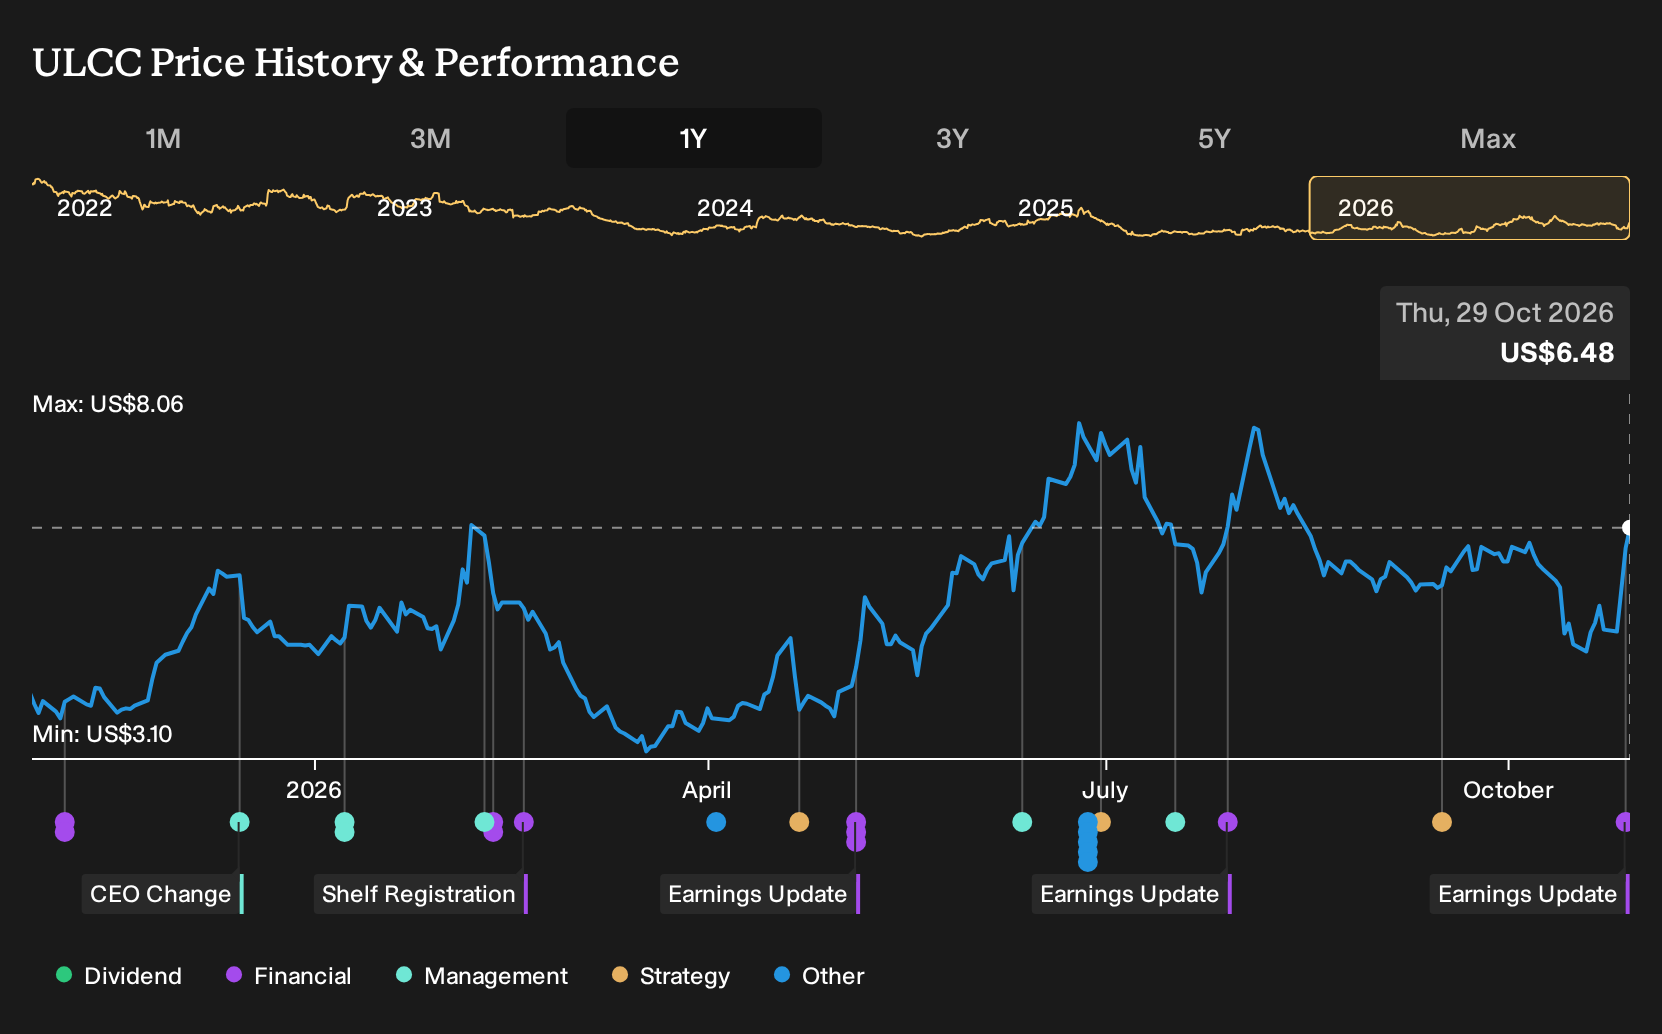
Exploring Other Perspectives
One alternate read on Frontier Group Holdings focuses on balance sheet strain rather than demand. The most cautious analysts already assumed revenue of about US$5.8b and earnings of roughly US$367.2 million by 2029, yet still landed on a US$4.0 price target. That more pessimistic path may be revisited after this earnings release. Consider it as one of several viewpoints to compare with your own expectations.
Explore 3 other Frontier Group Holdings fair value estimates, including one that suggests it could be worth just $6.67.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Frontier Group Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Frontier Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easier to evaluate Frontier Group Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Frontier Group Holdings?
If Frontier Group Holdings has sharpened your focus on risk, reward, and balance sheet strength, it can be useful to compare it with other candidates using the same lens. The Simply Wall St Screener lets you scan the market for companies that fit specific traits so you can build a watchlist that matches your own risk tolerance and return goals.
- If you prefer stability and lower downside risk, even if it means more modest upside potential, then shortlist companies from our 30 resilient stocks with low risk scores that score well on resilience metrics.
- If you lean toward durable cash flows and healthier finances, filter for candidates with sturdy balance sheets through the list of solid balance sheet and fundamentals (23 results) to see which businesses line up with that profile.
- For investors looking for quality at a reasonable entry point, start with the 18 high quality undiscovered gems and see which lesser known companies match your criteria on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com