
How Rating Upgrade At Century Aluminum Stock Has Changed Its Investment Story
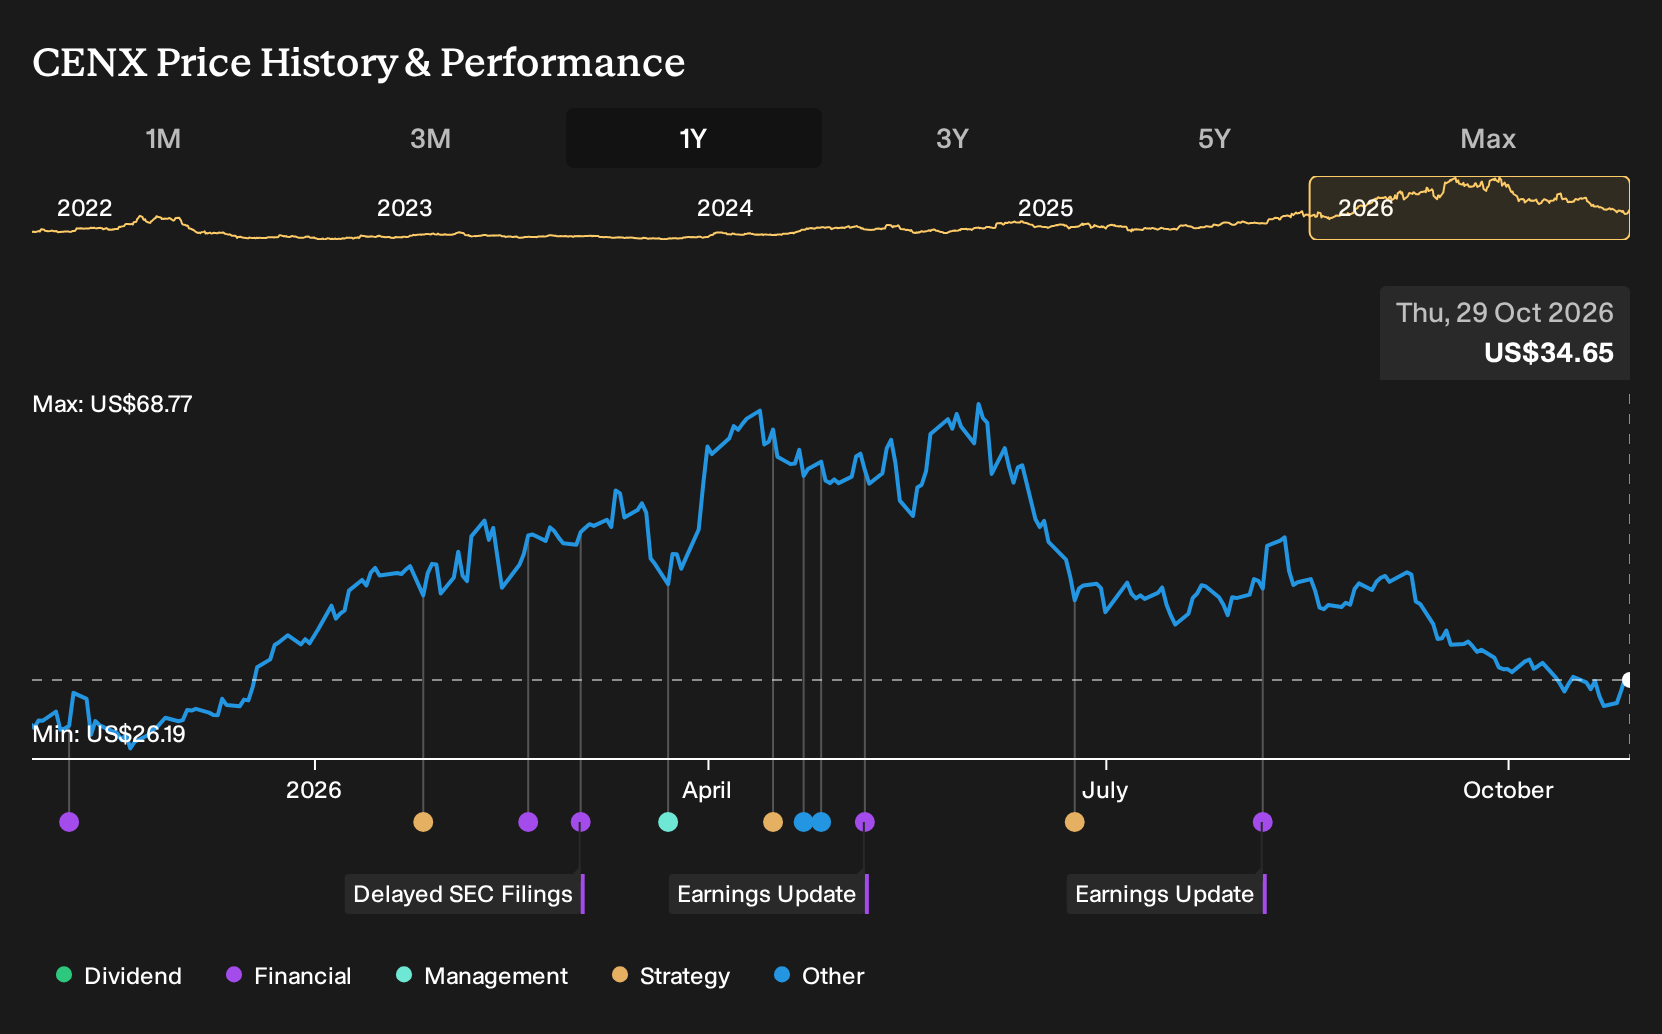
- Century Aluminum recently drew fresh attention after Argus issued a rating upgrade, spotlighting the producer’s global smelting, anode, and alumina operations across the United States, Iceland, the Netherlands, and Jamaica.
- The upgrade pulls focus onto how effectively Century Aluminum can translate its expanded smelting footprint and vertically linked alumina and bauxite assets into earnings that are more resilient across different pricing and cost conditions.
- Next, the focus turns to how Century Aluminum’s broader investment narrative could shift as investors reassess execution risks following the Argus upgrade.
Scan how Century Aluminum’s upgrade fits into the wider move in metals and materials by lining up its profile against our hand picked list of solid balance sheet and fundamentals (23 results).
Century Aluminum Investment Narrative Recap
To own Century Aluminum, you need to be comfortable with a story built on tight primary aluminum supply, U.S.-focused smelting capacity, and an increasingly integrated raw materials chain. The short term swing factor remains how realized London Metal Exchange and regional premiums feed into pricing, given the recent US$95 million quarterly benefit from stronger premiums.
The biggest operational risk is cost creep and complexity, particularly around Jamalco, where lower bauxite quality is already a headwind. The Argus upgrade shines a light on execution at projects like Mt. Holly, Grundartangi, and Oklahoma, but it does not change the fact that missteps on costs or volumes could quickly dilute earnings power.
Recent attention on Century Aluminum ties most cleanly into progress across its restart and expansion projects, especially the proposed 750,000 tonne per year Oklahoma smelter and the full restarts at Grundartangi and the wider system. These moves are about lifting potential shipment volumes and spreading fixed costs over a larger production base.
For you as an investor, the hook is how efficiently the group can turn that extra capacity into cash while keeping energy, alumina, and bauxite costs under control. Execution on the Oklahoma build out, the TG4 turbine at Jamalco, and the Brimstone alumina agreement remains central to that story, with sentiment shifts around the Argus call sitting clearly in the background.
Century Aluminum Forecasts In Focus
Century Aluminum's current analyst narrative rests on forecasts that link its physical expansion to a larger financial footprint. Instead of only watching volume headlines from Oklahoma or Grundartangi, you can track whether the company is pacing in line with what the consensus numbers imply over the next several years.
Analysts in the Simply Wall St excerpt are modeling revenue growth of 20.9% per year over the next three years. On earnings, the same group expects profit to reach US$1.2b by around 2029, compared with earnings today of US$603.0m. That implies an earnings increase of roughly US$597m over the period, with margin assumptions stepping up from 22.6% now to 25.6% in three years, and a forecast year anchored in 2029 for both top line and bottom line estimates.
Century Aluminum's narrative projects US$4.7b revenue and US$1.2b earnings by 2029. This requires 20.9% yearly revenue growth and an earnings increase of roughly US$597m from US$603.0m today.
Uncover why Century Aluminum's fair value indicates a 74% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternate view leans hard on Jamalco risk. You see the Argus upgrade. The most cautious Century Aluminum analysts still worry that several more quarters of higher alumina costs could bite into profit. Their pre upgrade estimates pointed to roughly US$4.0b revenue and US$765.3m earnings by 2029, a much cooler story than consensus. That gap shows how far opinions can spread. Treat this as a prompt to explore both forecasts and decide which narrative you find more reasonable as new information arrives.
Explore 4 other Century Aluminum fair value estimates, including one that suggests it could be worth just $40.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Century Aluminum research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Century Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Century Aluminum's overall financial health at a glance.
Looking For More Ideas Beyond Century Aluminum?
Once you have a handle on Century Aluminum, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener gives you a fast way to spot candidates that match what you care about most, whether that is value, resilience, or future potential.
- If you like the idea of paying less for quality, start with companies that combine strong fundamentals and attractive pricing through our 30 high quality undervalued stocks.
- If capital protection matters to you, filter for stocks with sturdier balance sheets and lower overall risk using the 30 resilient stocks with low risk scores.
- If you want to broaden your watchlist with underfollowed stories, scan the 18 high quality undiscovered gems to find businesses that score well on quality but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com