
Enterprise Products Partners (EPD) Stock Still Looks Cheap Given Its Earnings Story
Enterprise Products Partners has delivered strong returns over recent years, which puts fresh focus on whether today's price still lines up with what its earnings can reasonably support. For anyone holding or considering Enterprise Products Partners, the issue is less about momentum and more about what the current valuation is asking those earnings to justify.
- Enterprise Products Partners has returned 147.3% over the past 5 years, which puts real weight on whether the current earnings profile can back up that kind of share price journey.
- The partnership's fee-based midstream model and focus on cash generation can shape how reliably its earnings convert into distributable cash, which is central to any valuation grounded in profits.
- There is a second opinion on Enterprise Products Partners worth weighing. See what analysts think Enterprise Products Partners's shares could be worth.
The stock's next move may depend on whether Enterprise Products Partners' current earnings are enough to justify the price investors are asked to pay today.
If you want a broader watchlist while you assess whether Enterprise Products Partners' earnings back up its recent 5 year return, a focused stock screen built on our screener containing 18 high quality undiscovered gems can be a useful second reference point.
Is Enterprise Products Partners Still Cheap on Earnings?
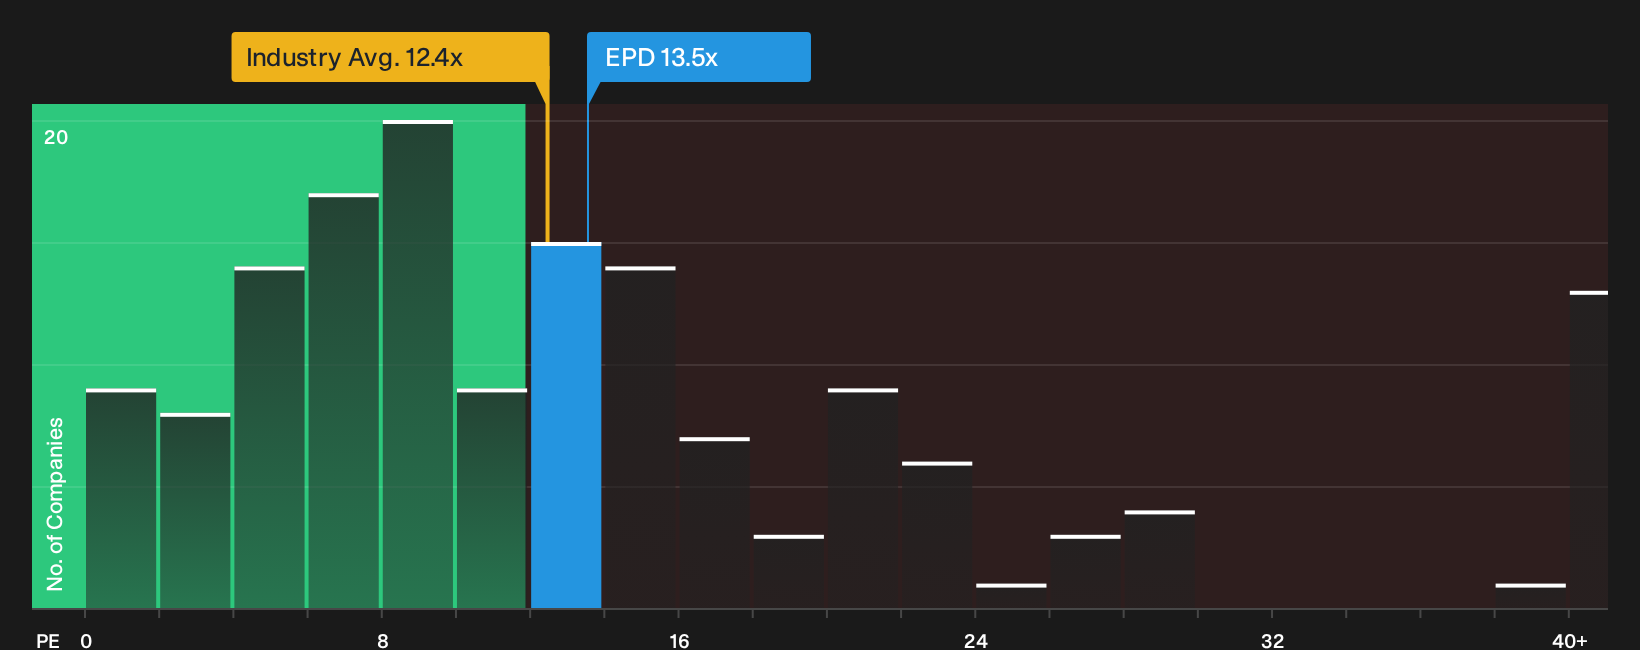
The P/E ratio fits Enterprise Products Partners because earnings are a key anchor for a fee-based cash generator. The partnership currently trades on about 13.5x earnings, which is slightly above the broader oil and gas sector average of roughly 12.4x. That puts the stock on a richer earnings tag than many midstream and energy peers that share similar commodity and regulatory exposures.
A more tailored fair P/E that blends Enterprise Products Partners' profitability profile, size and risk points to a higher level than where the units change hands today, so the current 13.5x screens as undervalued against that yardstick. The broader peer group averages around 23.7x on earnings, which frames the present multiple as a discount to comparable businesses and leaves room for investors to decide whether the quality of Enterprise Products Partners' earnings stream justifies that gap. Explore the numbers behind Enterprise Products Partners's P/E valuation.
The Enterprise Products Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion leaves off for Enterprise Products Partners. They spell out which paths for future growth, profitability and earnings would need to play out for the units to look meaningfully cheaper or more expensive than they appear right now. Each scenario links its number to a clear view on how Enterprise Products Partners' revenue trajectory, margins and risk profile might evolve, so you can revisit those assumptions as fresh information comes through.
One of the top community narratives on Enterprise Products Partners: 6% undervalued
"The main thing that has to go right is that higher growth capex in the Permian and related NGL infrastructure converts into sustained, high-utilization volumes..."
Discover why this Narrative puts Enterprise Products Partners at 6% undervalued.
One more angle on Enterprise Products Partners that could shift how you see it
Everything so far has focused on what Enterprise Products Partners looks like today, but there is a separate set of expectations a few years out that can either reinforce or challenge your view. Explore where analysts expect Enterprise Products Partners to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com