
Could Licensing Deal Alter The Investment Case For Astellas Pharma Stock?
- Astellas Pharma entered an exclusive option and license agreement with Audax Biosciences for DAX-044, an AVIKINE immuno-oncology candidate for solid tumors, with up to US$1.34 billion in potential value including US$285 million in upfront and option payments and further milestones plus royalties.
- The deal adds an external immuno-oncology asset to Astellas Pharma's pipeline while leaving early clinical costs with Audax until Phase 1 readouts start to emerge.
- The focus now is on how Astellas Pharma's investment narrative evolves as it commits up to US$1.34 billion to secure DAX-044 rights.
Scan how Astellas Pharma’s latest oncology move compares with other potential breakout healthcare bets by reviewing the hand-picked 10 healthcare AI stocks list.
Astellas Pharma Investment Narrative Recap
For Astellas Pharma, the big picture investors need to understand is that management aims to replace XTANDI concentration with a broader mix of oncology, ophthalmology and women’s health products while holding margins together. In the near term, the key swing factor remains how quickly newer brands scale as U.S. pricing pressure and XTANDI’s patent expiry start to bite.
The DAX-044 option does not shift that near-term catalyst. It sits earlier in the pipeline, with Phase 1 only expected to start in 2027. The main risk still centers on revenue and earnings declining faster than cost savings and new launches can offset.
The DAX-044 agreement with Audax is the most relevant recent development. It fits the plan to lean into oncology R&D while using business development to add external science rather than relying only on internal projects such as setidegrasib or ASP2138. Investors are effectively judging Astellas Pharma on execution depth across multiple cancer programs.
Because Audax funds DAX-044 through Phase 1, Astellas Pharma keeps early cash demands contained while committing up to US$1.34 billion over time, excluding royalties. That structure matters for the wider capital allocation plan, which targets ¥2.0 trillion into R&D and ¥850 billion into deals through FY2030, all while XTANDI revenue faces pricing cuts and eventual generic competition.
Astellas Pharma's current analyst narrative points to revenues of ¥1,953.3b and earnings of ¥263.7b by 2029, based on a forecast 4.9% yearly decline in revenue and a move from earnings today of ¥364.9b to that 2029 consensus. This represents an earnings decrease of ¥101.2b over the period.
Uncover why Astellas Pharma's fair value indicates that Astellas Pharma is roughly in line with its current price.
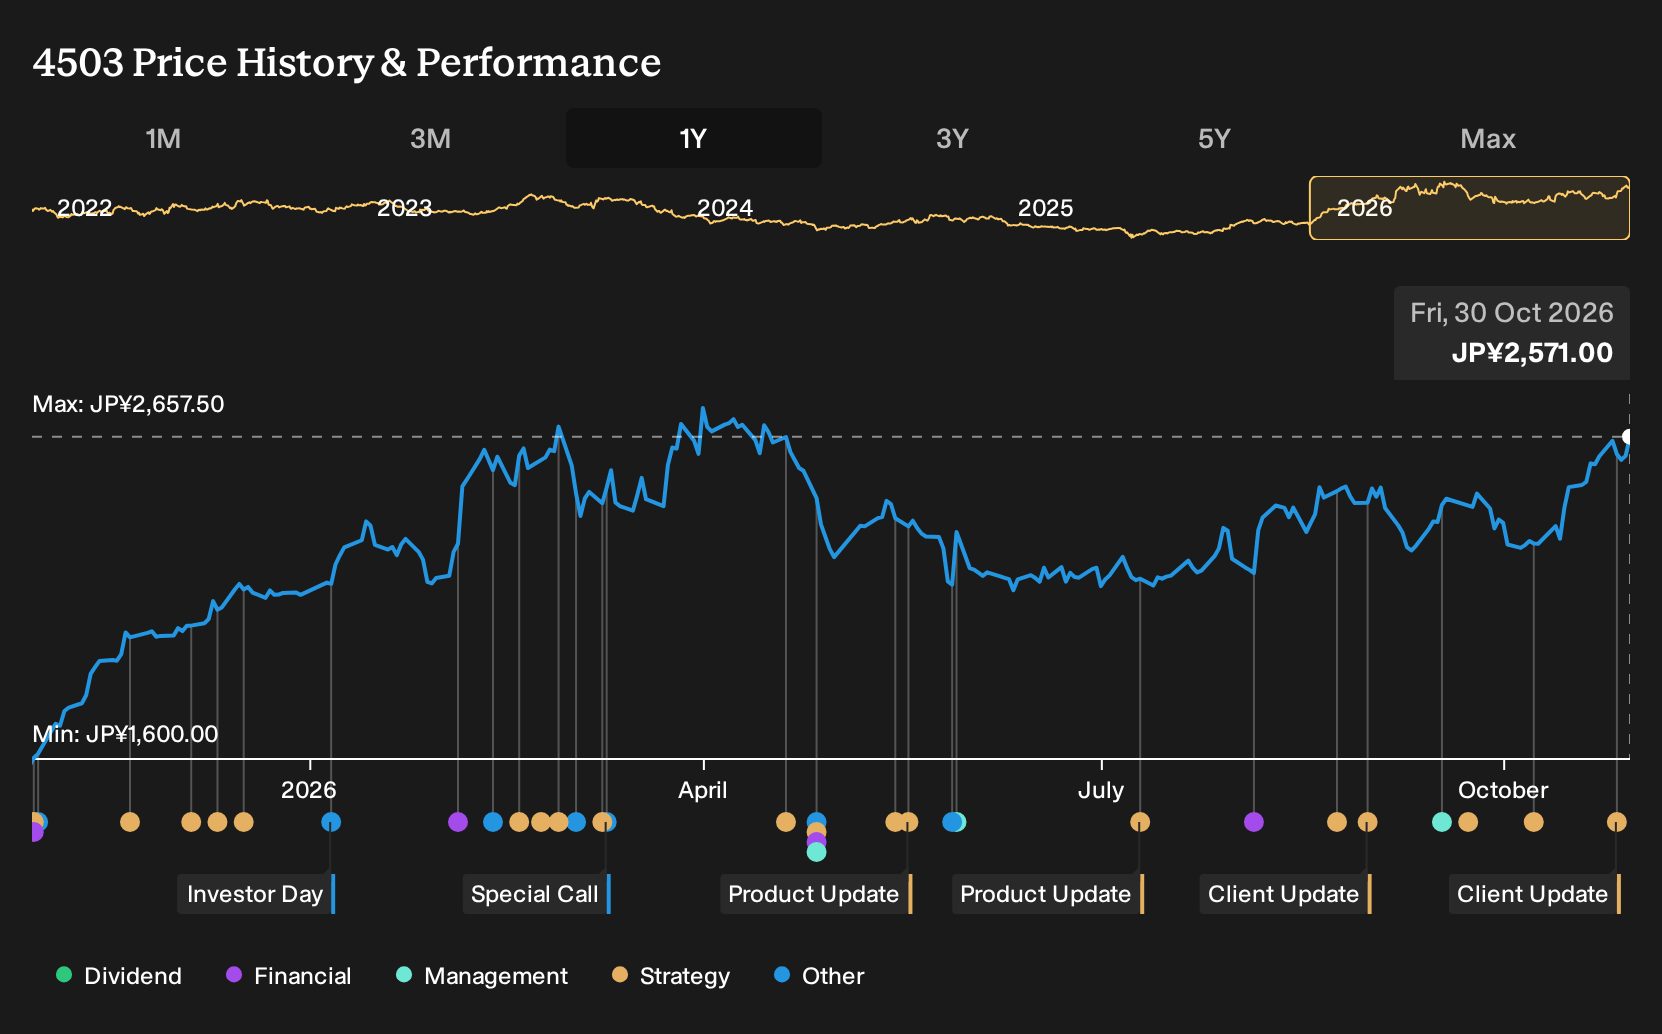
Exploring Other Perspectives
One alternate view focuses less on DAX-044 and more on a sharper XTANDI cliff for Astellas Pharma. The most bearish analysts were pencilling in revenues of ¥1,719.7b and earnings of ¥187.2b by 2029, far below consensus. That is a tougher story, and it might shift again once this new deal is fully digested.
Explore 2 other Astellas Pharma fair value estimates, including one that suggests it could be worth just ¥2,529.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Astellas Pharma research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astellas Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astellas Pharma's overall financial health at a glance.
Looking For More Astellas Pharma Style Investment Ideas?
If Astellas Pharma has you thinking more broadly about where to put fresh capital to work, it can help to line it up against a wider field of opportunities that share traits you care about most. The Simply Wall St Screener lets you filter for that, whether you care more about quality, resilience, or income.
- If capital preservation is your top priority, start with stocks that screen as relatively resilient by checking out 24 resilient stocks with low risk scores.
- If you want income potential on your radar, scan for companies that currently offer stronger yields through the 28 dividend fortresses.
- If quality at a reasonable entry point is the goal, broaden your watchlist with the 71 high quality undiscovered gems that pass fundamental filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com