
Learn Why The Bull Case For Coherent (COHR) Could Change Following Capacity Expansion
- Coherent has recently drawn fresh analyst attention as its expanded indium phosphide production capacity and PhotonLink product expectations reshape views on the business outlook and earnings potential.
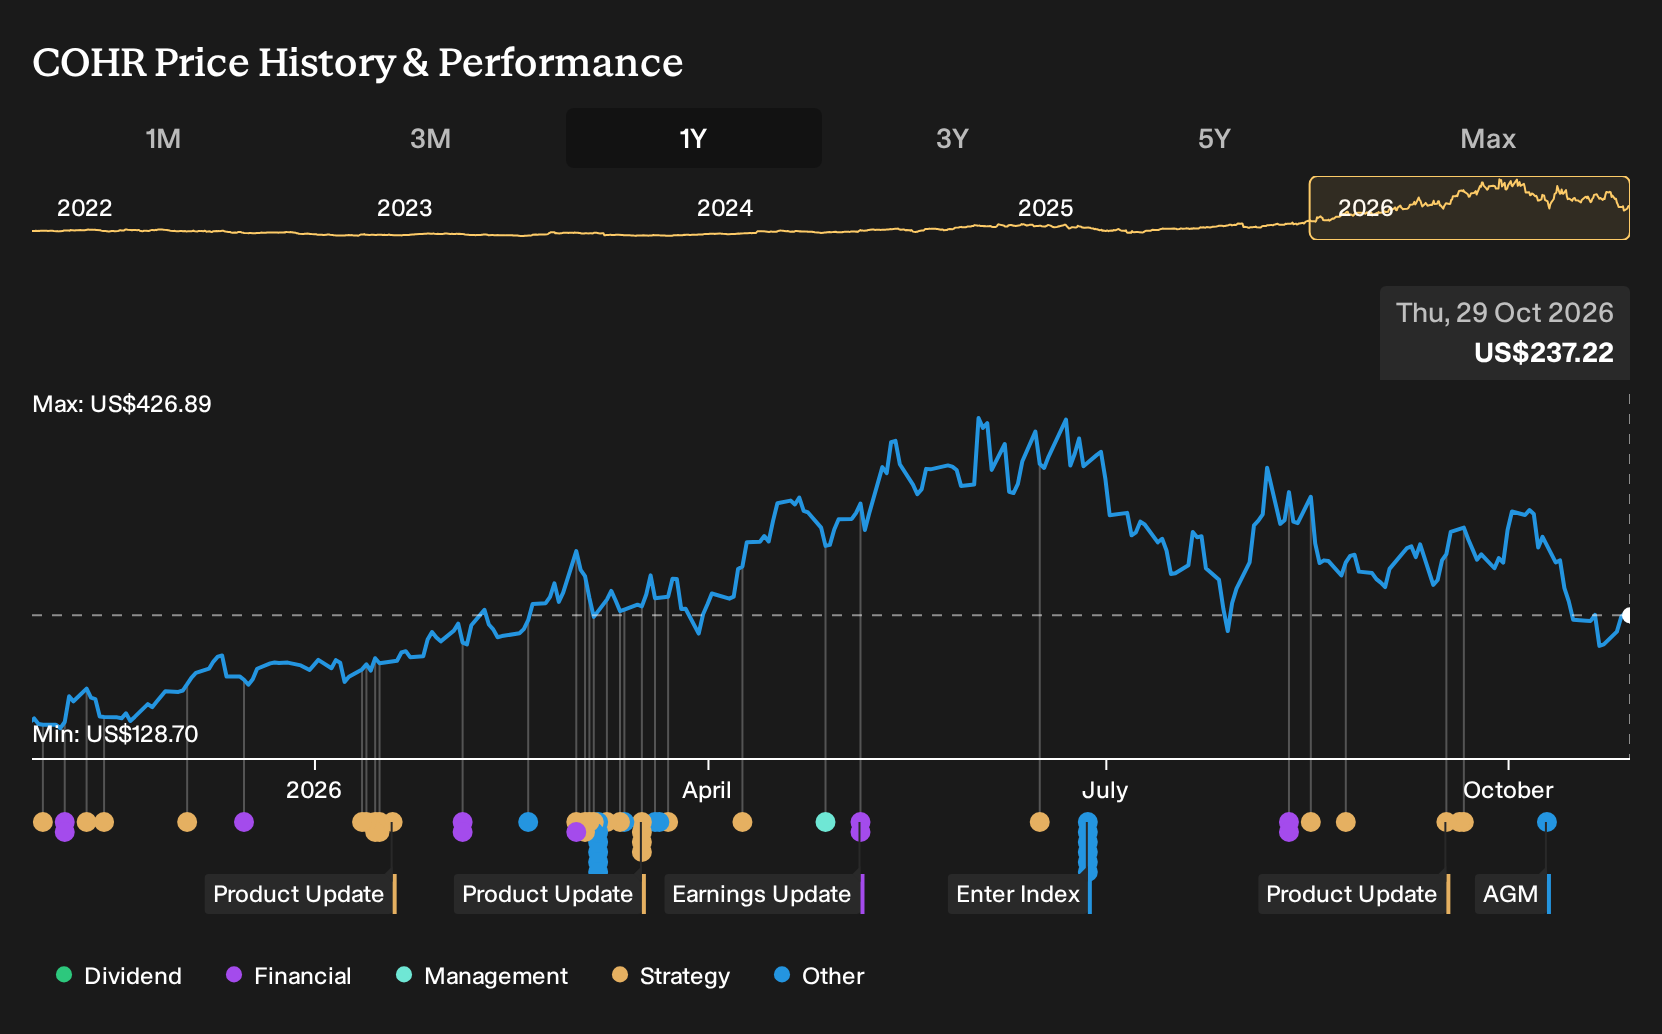
- The roughly 7x share price gain over three years has put Coherent's premium P/E multiple under the microscope and is focusing discussion on whether margins, scale, and photonics demand can support that valuation over time.
- We will now assess how Coherent's expanded indium phosphide capacity affects the existing investment narrative and where it could shift expectations.
Scan other photonics and AI infrastructure players that analysts are watching alongside Coherent with the curated 54 AI infrastructure stocks list.
Coherent Investment Narrative Recap
To own Coherent, you need to believe its heavy leaning into AI datacenter optics and indium phosphide manufacturing can translate into durable demand and healthier margins. The recent talk of Marvell pursuing Lumentum underlines how important optical capacity has become for AI infrastructure, but it does not directly alter Coherent's near term execution goals.
The key short term swing factor remains how smoothly Coherent ramps its expanded indium phosphide line and PhotonLink products without eroding pricing in a competitive transceiver market. The biggest risk is still a combination of capital intensity and customer concentration, where any pause in hyperscaler or large electronics orders could quickly expose fixed costs.
In this context, the most relevant recent development is Coherent's push into 6 inch indium phosphide production in Texas. That buildout sits in the slipstream of AI capex and underpins the premium multiple investors currently pay, because it aims to cut unit costs and support high speed optics at scale for 800G and 1.6T applications.
This capacity move ties directly into the main catalysts investors focus on. Stronger AI datacenter demand could help absorb new output and support gross margin improvement, while any industry price war or slower order flow would make the same investment feel heavier on the balance sheet and increase scrutiny on execution quality.
Coherent Analyst Assumptions At A Glance
Coherent's narrative projects US$19.3b revenue and US$3.5b earnings by 2029. Analysts are factoring in 39.4% yearly revenue growth and an earnings increase of about US$2.7b from current earnings of US$769.9m to reach that forecast.
Uncover why Coherent's fair value indicates a 71% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Coherent centers on PhotonLink turning the Marvell and Lumentum deal into a tailwind rather than fresh competition. The most optimistic analysts were already modeling about US$24.3b of revenue and US$4.3b of earnings by 2029. You can see how views might stretch even further, or pull back, as this news settles in.
Explore 4 other Coherent fair value estimates, including one that suggests as much as 192% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coherent research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coherent?
If the Coherent story has sharpened your thinking and you want to scan a wider opportunity set, the Simply Wall St Screener can help you quickly filter companies that fit the kind of portfolio you want to build.
- If capital preservation matters to you, focus on resilient businesses with steadier profiles using our 30 resilient stocks with low risk scores.
- If balance sheet strength is your priority, narrow your search to companies with robust finances through this list of solid balance sheet and fundamentals (23 results).
- If you are hunting for underfollowed opportunities, widen your watchlist with a 18 high quality undiscovered gems that could complement a position in Coherent.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com