
How Bearish Earnings Forecasts At EchoStar (ECHO) Have Changed Its Investment Story
- EchoStar recently presented at the 14th Annual Denver CIO Executive Leadership Summit, where Head of Agentic AI Platform Operations Sharath Venkatarao outlined the company’s approach to agentic AI in enterprise settings.
- The focus on EchoStar’s agentic AI platform operations highlights how the business is investing in operational tooling and automation rather than headline consumer AI features, which speaks directly to cost efficiency and execution quality.
- We will now look at how EchoStar’s investment narrative could be influenced by this agentic AI focus and bearish earnings expectations.
Compare EchoStar's agentic AI pitch with other potential beneficiaries of this shift by scanning our hand-picked 54 AI infrastructure stocks that could be building the plumbing behind enterprise AI adoption.
What Is EchoStar's Investment Narrative?
To own EchoStar, you need to believe that a capital heavy mix of pay TV, wireless and broadband can generate better earnings even if top line trends stay soft. The agentic AI push that Sharath Venkatarao outlined is really about execution, not sizzle. If it works, it could reduce operating friction and support margins at a time when analysts expect both revenue and earnings for the September 2026 quarter to decline year on year.
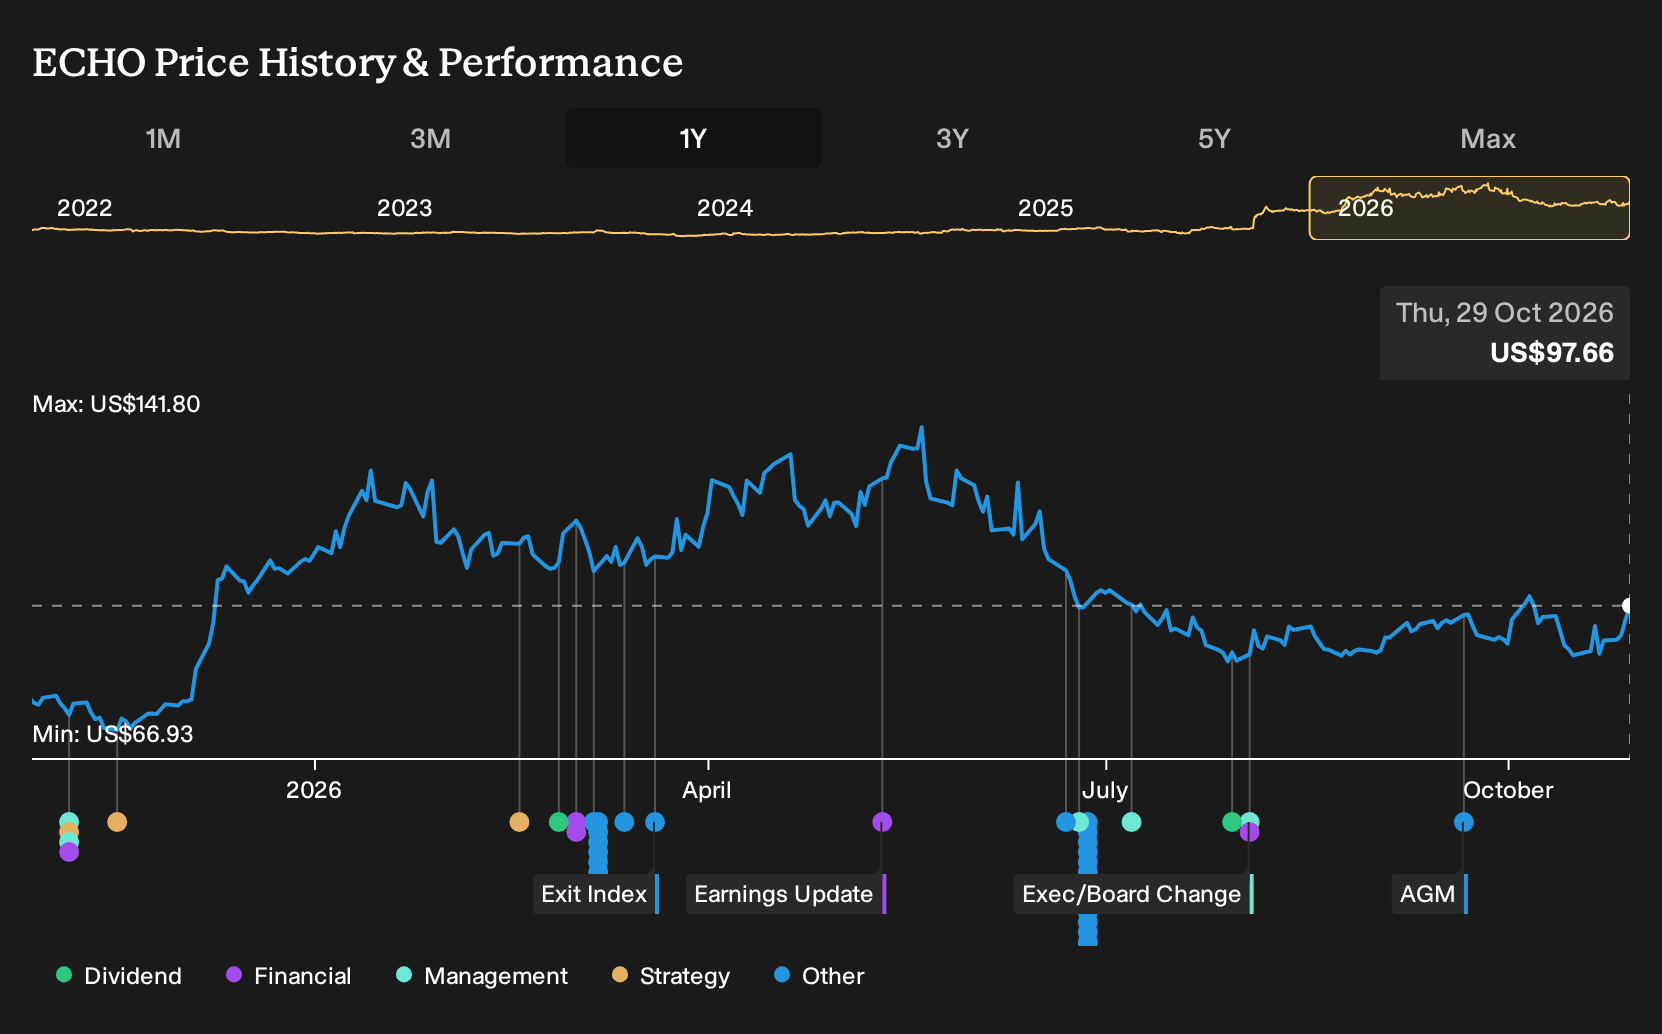
In the short term, the real swing factors are whether EchoStar can manage that expected earnings dip, handle high network and satellite spending, and still fund its AI and 5G efforts with less than one year of cash runway flagged. Recent bearish sentiment on the upcoming print raises the bar for management to show cost control and clear payoffs from these AI tools, especially with the stock already up strongly over 1 year but still described as expensive on several valuation metrics.
Yet there is a deeper issue in the background that could reshape this whole EchoStar thesis once you look at ...
There's only one way to know the right time to buy, sell or hold EchoStar. Head to Simply Wall St's company report for the latest analysis of EchoStar's Fair Value.
Exploring Other Perspectives
For EchoStar, the key alternate risk is that heavy legacy liabilities crowd out the agentic AI story. The most bearish analysts were modeling revenue to slide about 8% a year and still saw losses persisting, with scenarios that ranged from roughly US$1.2b in earnings to a loss of about US$469.3 million by 2029. Those views were set before this Denver AI presentation, so you should expect opinions to evolve as new information becomes available.
Explore 5 other EchoStar fair value estimates, including one that suggests as much as 56% downside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your EchoStar research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for EchoStar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EchoStar's overall financial health at a glance.
Looking For More Ideas Beyond EchoStar?
If the EchoStar story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit very different risk and income profiles.
- For investors who care most about income resilience, consider using our screener focused on robust payers and scan a curated set of 7 dividend fortresses that combine higher yields with staying power.
- If capital preservation ranks higher on your list, filter for companies that score well on stability and review a 30 resilient stocks with low risk scores that may offer smoother rides through choppy markets.
- When you want quality at a reasonable price, start with financially healthy businesses trading below their assessed worth and sort through a 30 high quality undervalued stocks that could merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com