
US Market's Hidden Treasures Featuring 3 Undiscovered Gems
Over the last 7 days, the United States market has remained flat, yet it has seen a notable 10% increase over the past year, with earnings expected to grow by 17% annually. In this environment, identifying stocks with strong potential often involves uncovering lesser-known companies that possess solid fundamentals and promising growth prospects.
Top 10 Undiscovered Gems With Strong Fundamentals In The United States
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ardmore Shipping | 4.77% | 6.85% | 20.85% | ★★★★★★ |
| Perma-Pipe International Holdings | 31.47% | 11.47% | 32.99% | ★★★★★★ |
| ADMA Biologics | 48.16% | 37.59% | 68.92% | ★★★★★★ |
| TOYO | 36.72% | 208.58% | 54.90% | ★★★★★☆ |
| Coeur Mining | 6.74% | 27.43% | 73.74% | ★★★★★☆ |
| Kingstone Companies | 2.94% | 9.01% | 64.05% | ★★★★☆☆ |
| Diebold Nixdorf | 100.55% | 0.59% | 20.73% | ★★★★☆☆ |
| Meridian | 77.88% | -7.73% | -15.61% | ★★★★☆☆ |
| GDEV | NA | -1.59% | 54.97% | ★★★☆☆☆ |
| F&G Annuities & Life | 48.57% | 13.75% | -26.95% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
Power Solutions International (PSIX)
Simply Wall St Value Rating: ★★★★★★
Overview: Power Solutions International, Inc. designs, engineers, manufactures, markets, and sells engines and power systems globally with a market cap of $1.12 billion.
Operations: PSIX generates revenue primarily from its Engineered Integrated Electrical Power Generation Systems, amounting to $676.19 million.
Power Solutions International (PSI) is navigating a transformative phase, marked by a strategic push towards the data center power market. Despite recent volatility and net profit margins dipping to 10% from last year's 18.6%, PSI's debt situation has improved with positive shareholder equity after five years of negative figures. The company recently secured a US$220 million revolving credit agreement, enhancing its financial flexibility for growth initiatives. Although earnings fell by 38.8% compared to industry averages, PSI's EBIT covers interest payments comfortably at 13.4x, suggesting solid operational efficiency amidst evolving market demands and opportunities in AI-driven infrastructure needs.
- Take a closer look at Power Solutions International's potential here in our health report.
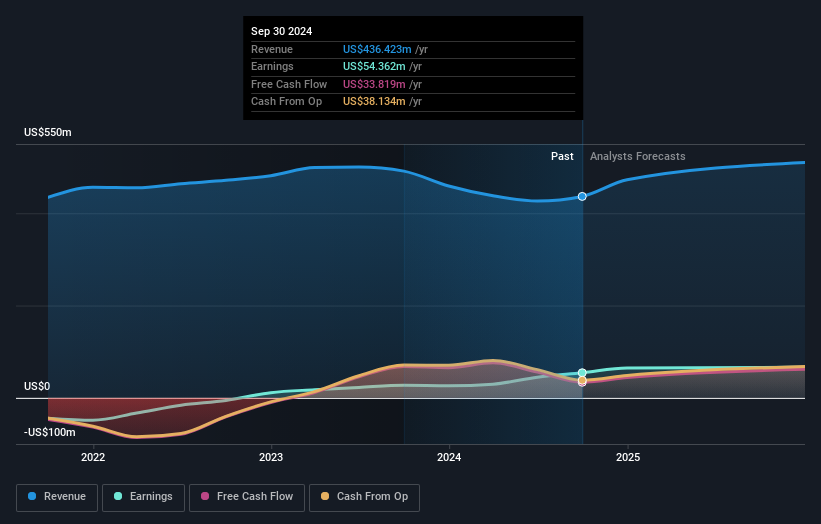
Learn about Power Solutions International's historical performance.
Kaspi.kz (KSPI)
Simply Wall St Value Rating: ★★★★★☆
Overview: Joint Stock Company Kaspi.kz, along with its subsidiaries, offers payments, marketplace, and fintech solutions to consumers and merchants in Kazakhstan, Azerbaijan, and Ukraine with a market cap of approximately $17.99 billion.
Operations: Kaspi.kz generates revenue primarily from its fintech, payments, and marketplace segments, with the marketplace contributing KZT 2.15 trillion and fintech adding KZT 1.71 trillion. The company experiences a net profit margin trend worth noting for its significance in financial analysis.
Kaspi.kz, a dynamic player in the fintech space, is navigating significant growth opportunities and challenges. Despite experiencing a -1.9% earnings dip last year against the Consumer Finance industry's 15.2% average growth, it trades at 49.3% below estimated fair value, offering potential upside for investors. The company's debt-to-equity ratio improved from 54.8% to 22.2% over five years, highlighting better financial health while maintaining high-quality earnings and positive free cash flow of KZT 1,057 billion as of December 2023. However, interest coverage remains low at 2.3x EBIT versus debt repayments, suggesting room for improvement in managing financial obligations effectively amidst expansion efforts in Türkiye's fintech landscape and AI integration within its super app ecosystem.

Ardmore Shipping (ASC)
Simply Wall St Value Rating: ★★★★★★
Overview: Ardmore Shipping Corporation operates in the global seaborne transportation sector, focusing on petroleum products and chemicals, with a market capitalization of $849.29 million.
Operations: The company's revenue primarily comes from the transportation of refined petroleum products and chemicals, amounting to $368.29 million.
Ardmore Shipping, a nimble player in the shipping sector, is capitalizing on tight tanker supply and increased longer-haul product trades. Its fleet efficiently transports petroleum products worldwide, with recent earnings bolstered by high Time Charter Equivalent levels. Ardmore's debt to equity ratio has impressively decreased from 43% to 4.8% over five years, indicating solid financial management. The company trades at a significant discount of 92.3% below estimated fair value and boasts high-quality earnings with interest payments well covered by EBIT at 15.1x coverage, suggesting robust operational health despite potential market risks impacting future margins and revenue growth.

Seize The Opportunity
- Click here to access our complete index of 21 US Undiscovered Gems With Strong Fundamentals.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com