
Western Midstream Partners (WES) Stock May Be A Bargain After Texas Water Pilot
Western Midstream Partners has delivered a strong share price run in recent years, and that kind of track record naturally pushes investors to ask whether the current tag is still backed up by its earnings power. With fresh attention on how the partnership earns money and what it might earn next, the focus turns to whether the present valuation is supported by the underlying profit stream.
- Over the past 5 years, Western Midstream Partners has returned 220.8%, which puts real pressure on the question of whether current buyers are paying a price that its earnings can justify.
- The produced water treatment pilot launched in Texas in 2026 may support long term revenue quality by influencing how efficiently the partnership can turn midstream volumes into cash earnings.
- The analysts covering Western Midstream Partners have run their own numbers. See what analysts think Western Midstream Partners's shares could be worth.
The stock's next move may depend on whether Western Midstream Partners' current price looks aligned with what its earnings suggest it should be worth.
If you are weighing whether Western Midstream Partners' earnings justify its current tag, it can help to compare that question across 30 high quality undervalued stocks.
Does Western Midstream Partners Look Undervalued on Earnings?
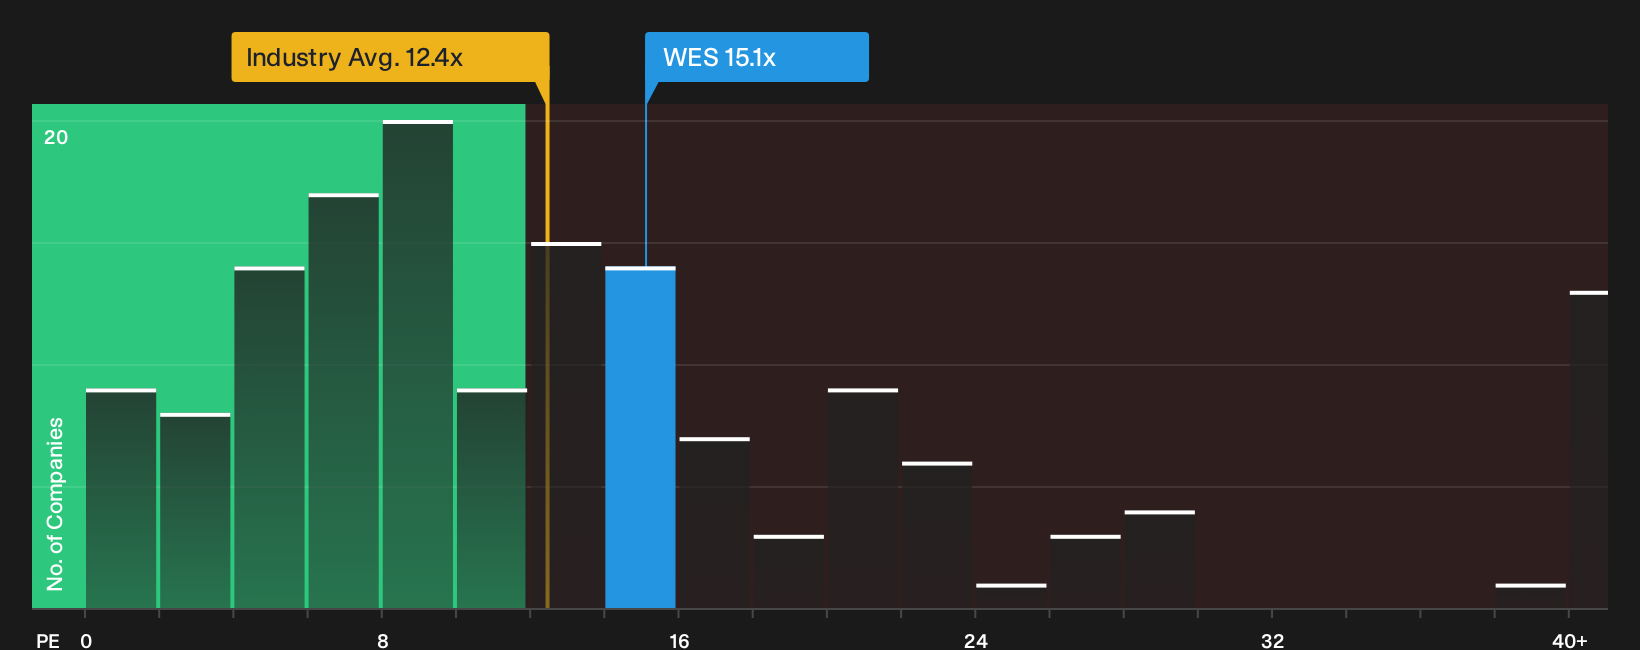
The P/E ratio fits Western Midstream Partners well because earnings quality sits at the center of how investors usually price mature midstream assets. On this yardstick, the units trade at about 15.1x earnings, below both the wider Oil and Gas sector on roughly 12.4x and the closer peer group on about 18.6x. Because the fair multiple that folds in Western Midstream Partners' own growth profile, margins and risk sits above the current figure, this gap points to a valuation that screens as undervalued on earnings.
Because Western Midstream Partners is investing in produced water treatment pilots in Texas, including the reclaimed freshwater project launched in 2026, some investors may be focusing more on long term cash flow resilience than headline profit today. Even with that backdrop, the present 15.1x P/E leaves units trading below the tailored fair multiple that the model suggests would be consistent with the partnership's economics. This frames the current tag as a discount on this metric. Explore the numbers behind Western Midstream Partners's P/E valuation.
The Western Midstream Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Western Midstream Partners valuation puzzle leaves off, turning the current P/E discussion into a clear set of future conditions for growth, margins and earnings that would need to hold for the units to be worth materially more or less than today. Instead of a single output from a ratio or model, Narratives lay out the future path that figure relies on so you can watch how real world results line up against it on the Community page.
One of the top community narratives on Western Midstream Partners: 8% undervalued
"The main factor that has to go right is continued execution on integrating Brazos, building Pathfinder and North Loving II on budget…"
Discover why this Narrative puts Western Midstream Partners at 8% undervalued.
For Western Midstream Partners, who is steering the ship matters as much as the price
Before making a call on Western Midstream Partners, it helps to understand who sets the priorities, how their rewards are structured, and whether that aligns with unitholders. See who runs Western Midstream Partners and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com