
How Earnings Outlook At Copa Holdings (CPA) Has Changed Its Investment Story
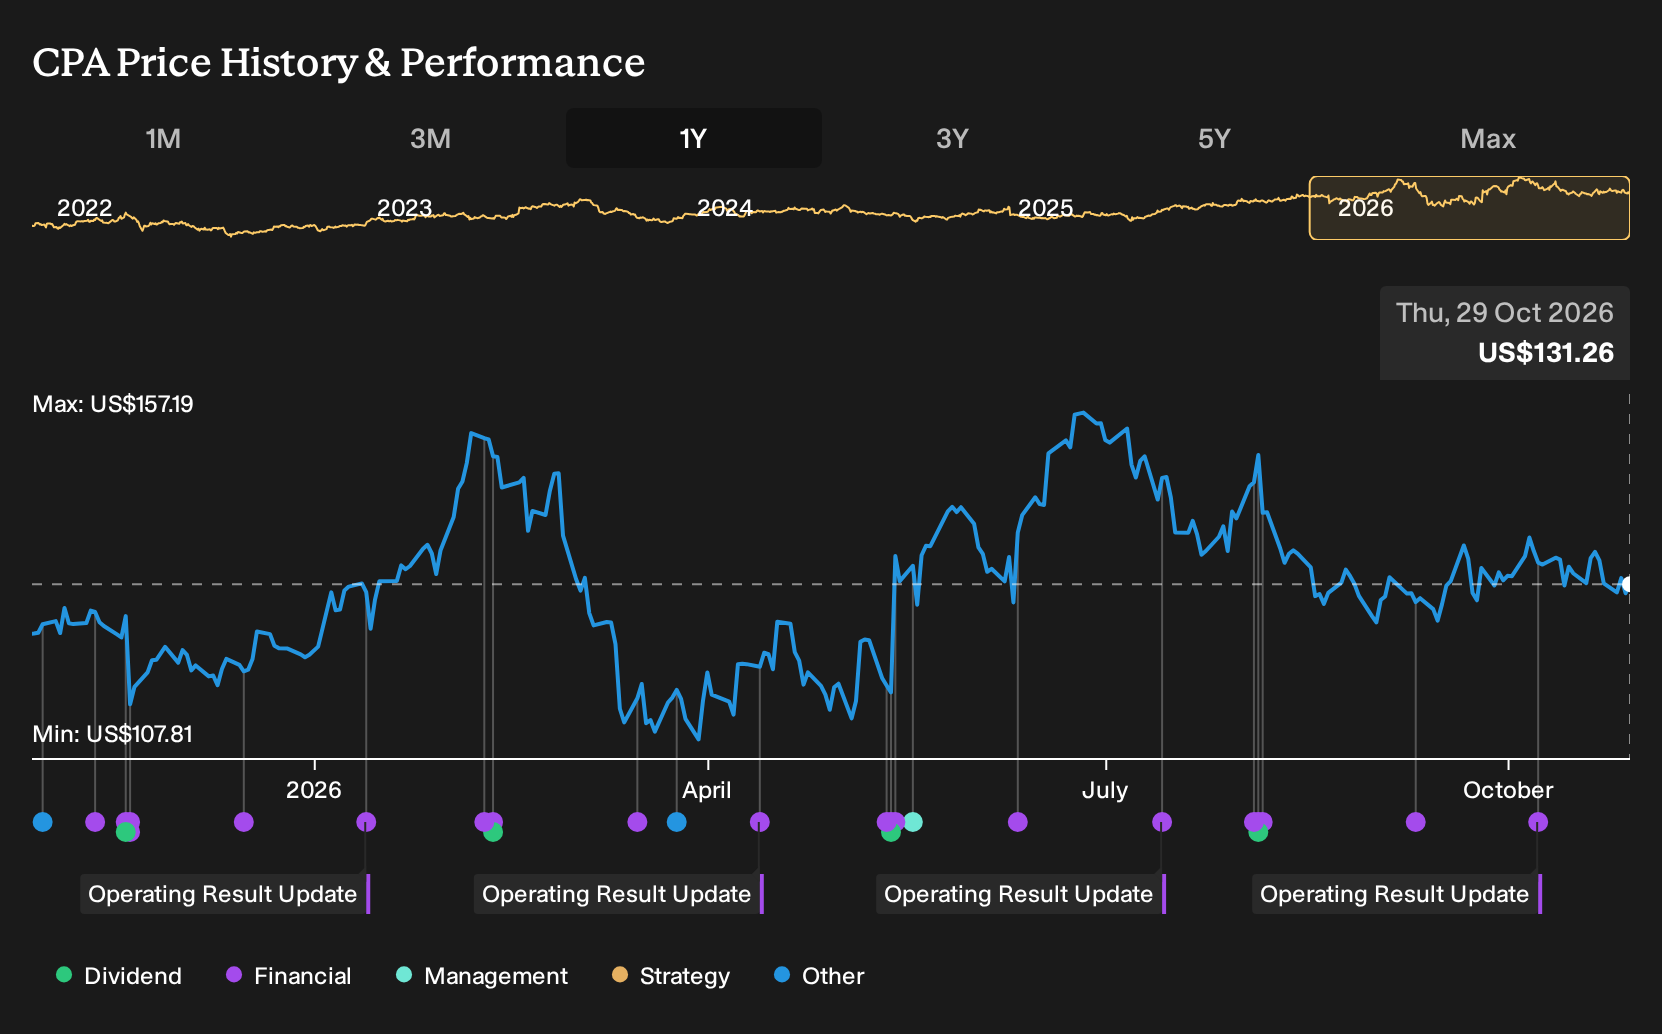
- Copa Holdings is caught between an earnings outlook that points to lower earnings per share on rising revenue and a P/E ratio that sits below airline peers, despite ongoing hub expansion and capacity growth plans at the Hub of the Americas.
- The combination of a lower industry relative P/E, a perception of about 26% undervaluation, and an upcoming earnings release with revised expectations is drawing attention to how Copa Holdings balances cost control, fuel exposure, and fleet investments against its growth ambitions.
- We will now examine how Copa Holdings' perceived undervaluation on earnings, together with its evolving earnings outlook, shapes the broader investment narrative.
Compare Copa Holdings' current valuation reset with a curated list of other potential value ideas in our 30 high quality undervalued stocks screener.
Copa Holdings Investment Narrative Recap
Copa Holdings appeals to shareholders who think its Hub of the Americas growth plan and low ex fuel cost structure can keep earnings power resilient, even as unit economics move around. The key near term catalyst is execution on capacity expansion and load factors through the hub. The latest update that earnings per share are expected to decline while revenue rises does not, on its own, alter that bigger thesis.
The more immediate risk is margin pressure if jet fuel prices stay volatile and fares or yields do not offset that, especially since Copa Holdings does not hedge fuel. In addition, a long dated Boeing 737 MAX fleet plan combined with higher capacity targets results in less flexibility if demand or pricing soften at the same time as aircraft related fixed costs and capital spending stay high.
The most relevant near term development is the scheduled earnings release on 18 November 2026, where the market already expects earnings per share to be lower year on year while revenue is projected higher. That mix will focus attention on how Copa Holdings is managing non fuel costs, pricing on key routes, and the early payoffs from capacity growth at the Panama hub.
A Zacks Rank of #4 (Sell) reflects recent downward earnings revisions and adds another data point to how expectations have reset into the print, but it is ultimately the operational detail that matters for catalysts. Investors will likely be watching for commentary on fuel exposure, the pace of adding new destinations and banks at the Hub of the Americas, and whether management adjusts any part of its medium term capacity or margin framework in response to current trading conditions.
Copa Holdings Earnings And Valuation Setup
Copa Holdings' narrative projects US$5.5b revenue and US$1.1b earnings by 2029. This assumes 11.0% yearly revenue growth and an earnings increase of about US$473.4m from US$626.6m today.
Uncover why Copa Holdings' fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Copa Holdings through a very different lens, treating the capacity ramp itself as the key catalyst. Before this latest update, the bullish camp was pencilling in about US$5.9b of revenue and US$1.3b of earnings by 2029. Those forecasts may shift, so use them as reference points while you weigh fresh information.
Explore 4 other Copa Holdings fair value estimates, including one that suggests potential upside of as much as 155% from the current price.
Form Your Own Verdict
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Copa Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Copa Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Copa Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Copa Holdings?
If you want to stress test your thesis on Copa Holdings and broaden your watchlist, the Simply Wall St Screener can help you compare it with other companies that fit very different profiles.
- For investors who care most about balance sheet strength and durability, check out a list of solid balance sheet and fundamentals (23 results) as a starting universe for further research.
- If your focus is on resilience and smoother ride potential, scan a 30 resilient stocks with low risk scores that may better match your risk tolerance.
- For those hunting for underfollowed businesses with sturdy fundamentals, use a 18 high quality undiscovered gems to surface ideas that rarely show up on headline lists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com