
WisdomTree (WT) Stock May Be Overvalued After Its 256% Run
WisdomTree has been on a strong multi year run, and with the share price recently closing at US$21.55, the live question is how firmly that move is grounded in the earnings the business is producing today. After such a stretch, the issue for anyone looking at the stock now is whether the current P/E really lines up with what the underlying profit stream can support.
- Over the past 3 years, WisdomTree has delivered a very large share price gain of about 2.6x, which puts extra weight on whether its earnings now justify such a rerating.
- The planned rollout of capital efficient, co branded model portfolios on the Quorus platform and the move into U.S. farmland investments through Ceres Partners may support different earnings drivers in future, from fee mix and margins to the timing and volatility of cash flows.
- There is a second opinion on WisdomTree worth weighing. See what analysts think WisdomTree's shares could be worth.
For investors, the debate is whether WisdomTree's current valuation against its earnings is still grounded in what the business is actually producing, or whether expectations have moved ahead of the profit profile.
If you are evaluating whether WisdomTree’s earnings justify its recent run, it can be useful to compare this question with other companies screened as 30 high quality undervalued stocks
Does WisdomTree Look Pricey on Earnings?
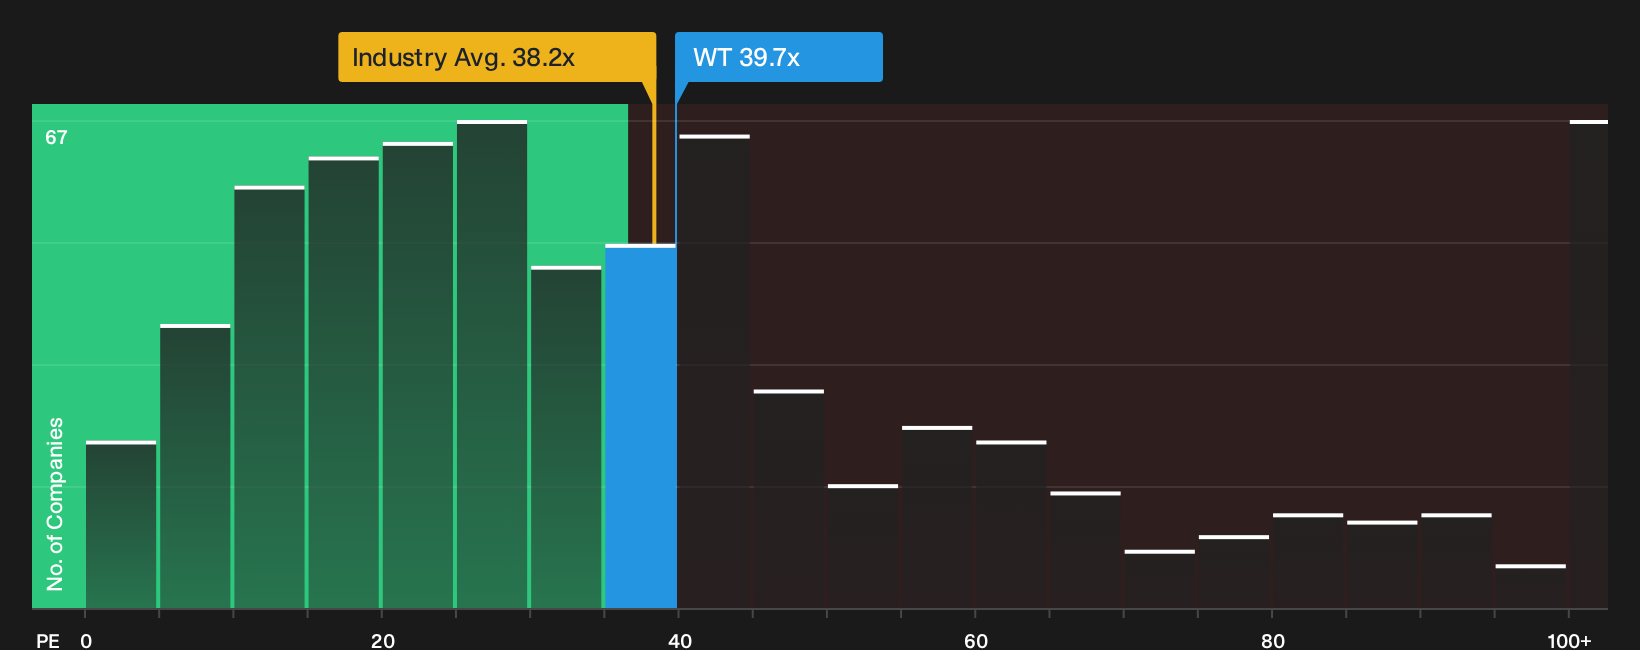
The P/E ratio is a clean way to judge what you pay today for each dollar of WisdomTree earnings. At roughly 39.7x, the stock trades above both the peer group average of about 15.6x and close to the broader capital markets industry level of around 38.2x, which already reflects higher expectations for this type of business.
On this framework, the tailored fair P/E that blends WisdomTree specific factors screens lower than the current multiple, which points to the shares looking overvalued on earnings alone. Because the recent Ceres Partners farmland acquisition and the planned Quorus model portfolio rollout introduce new fee streams and risk angles, you need to judge whether those developments justify paying this kind of premium now or whether expectations have already run ahead of what current profits show. Explore the numbers behind WisdomTree's P/E valuation.
The WisdomTree Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the WisdomTree valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the stock to look meaningfully richer or cheaper than it does today. They also frame each scenario as a thesis about how the business could develop that you can track over time rather than a one off snapshot. They live on Simply Wall St's Community page.
One of the top community narratives on WisdomTree: 18% undervalued
"The acquisition of Ceres Partners positions WisdomTree to continue building out private market and alternative asset exposures in areas such as U.S. farmland…"
Discover why this Narrative puts WisdomTree at 18% undervalued.
For WisdomTree, the share price is only one piece of the puzzle
Before you decide what to do with WisdomTree, it is worth asking who is steering the business, how those leaders are rewarded, and whether their incentives align with shareholders. See who runs WisdomTree and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com