
Can Indivior Pharmaceuticals (INDV) Keep Trading At A Discount After Record Results?
Indivior Pharmaceuticals has delivered a powerful share price run over the past few years, and the pending merger with Supernus now adds another layer to the story. With the stock near US$35.25 and the business about to fold into a new corporate structure, the live question is whether that price still lines up with what its earnings can support.
- Over the past 5 years, Indivior Pharmaceuticals has returned about 161%, which puts real pressure on the numbers to show that earnings progress can support such a step up in market value.
- Record recent financial results and rising SUBLOCADE revenue signal that investors may be factoring in stronger long term profitability and cash generation, which feeds directly into any earnings based valuation work.
- The analysts covering Indivior Pharmaceuticals have run their own numbers. See what analysts think Indivior Pharmaceuticals's shares could be worth.
The issue now is whether the current share price is justified by what Indivior Pharmaceuticals is earning today and what those earnings suggest about the business over time.
If you want to stress test this same earnings based question beyond Indivior Pharmaceuticals, line it up against a wider group of 30 high quality undervalued stocks.
Is Indivior Pharmaceuticals Still Cheap on Earnings?
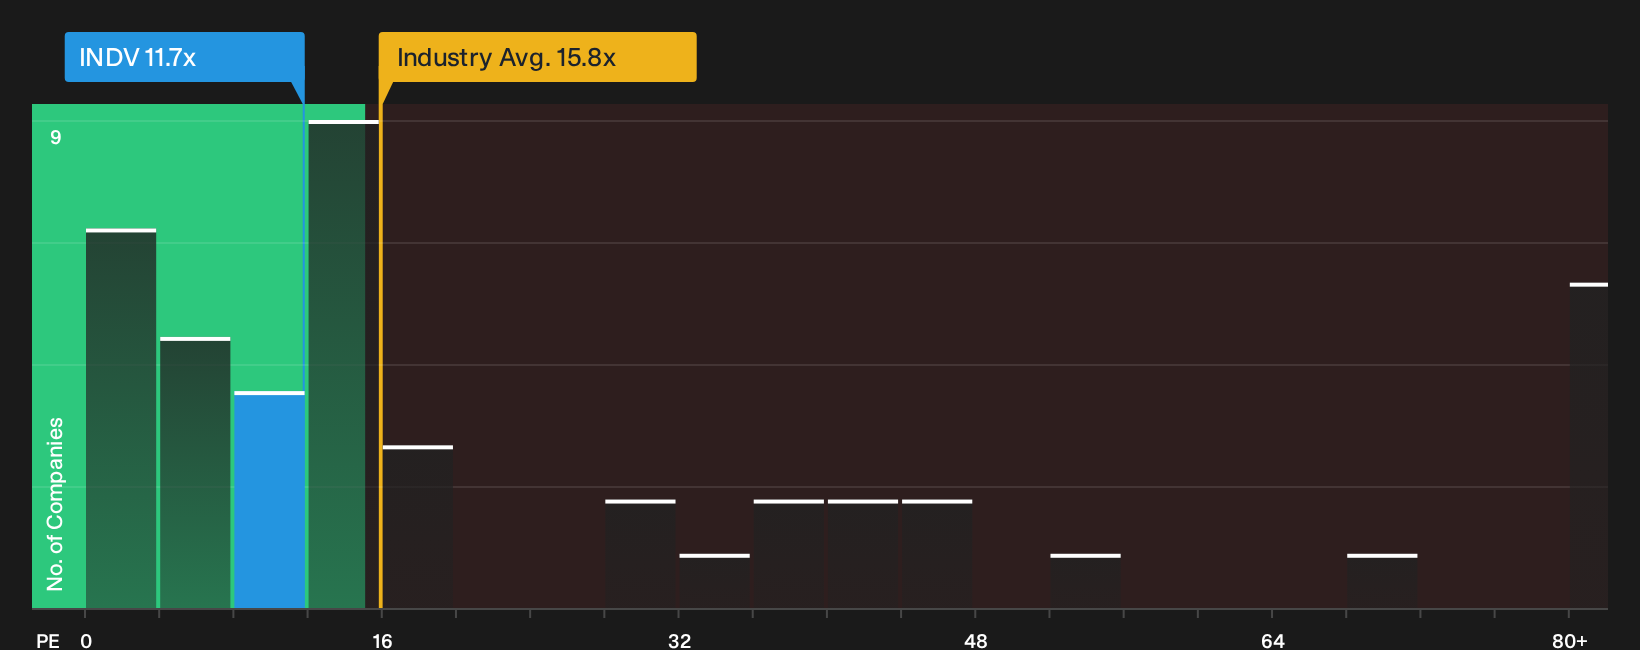
The P/E ratio fits Indivior Pharmaceuticals because the story here is still very much about earnings power rather than dividends. On this basis, the stock trades on about 11.7x, which is below the broader pharmaceuticals sector average of roughly 15.8x and also below peer companies nearer 27.5x. That gap indicates the market is pricing Indivior’s current earnings at a lower level than many similar businesses.
Record third quarter 2026 results and the pending Supernus merger have raised expectations around the combined group. However, the multiple still suggests a discount relative to what the valuation model highlights as a more tailored fair P/E level. For an investor weighing Indivior Pharmaceuticals, the key question is whether that lower P/E reflects lingering concern around execution and integration or whether it points to a stock that screens as undervalued on earnings. Explore the numbers behind Indivior Pharmaceuticals's P/E valuation.
The Indivior Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Indivior Pharmaceuticals pick up where this valuation puzzle leaves off and explain which paths for future growth, margins and earnings would need to hold for the share price to end up meaningfully higher or lower than it is today, based on scenarios laid out on the Community page. Each Narrative links a fair value estimate to a specific mix of possible catalysts and risks, allowing you to track over time which version of Indivior Pharmaceuticals' story appears to be gaining traction.
One of the top community narratives on Indivior Pharmaceuticals: 33% undervalued
The merger of Indivior Pharmaceuticals with Supernus is set to create a larger CNS platform with about US$2.2b of pro forma net revenue and US$888 million of adjusted EBITDA...
Discover why this Narrative puts Indivior Pharmaceuticals at 33% undervalued.
One more piece of the Indivior Pharmaceuticals puzzle investors should not skip
Market multiples tell you what Indivior Pharmaceuticals is worth today, but the next layer is what professional analysts think its earnings profile looks like a few years from now. Explore where analysts expect Indivior Pharmaceuticals to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com