
How Investors Are Reacting To Stepan (SCL) Earnings Beat
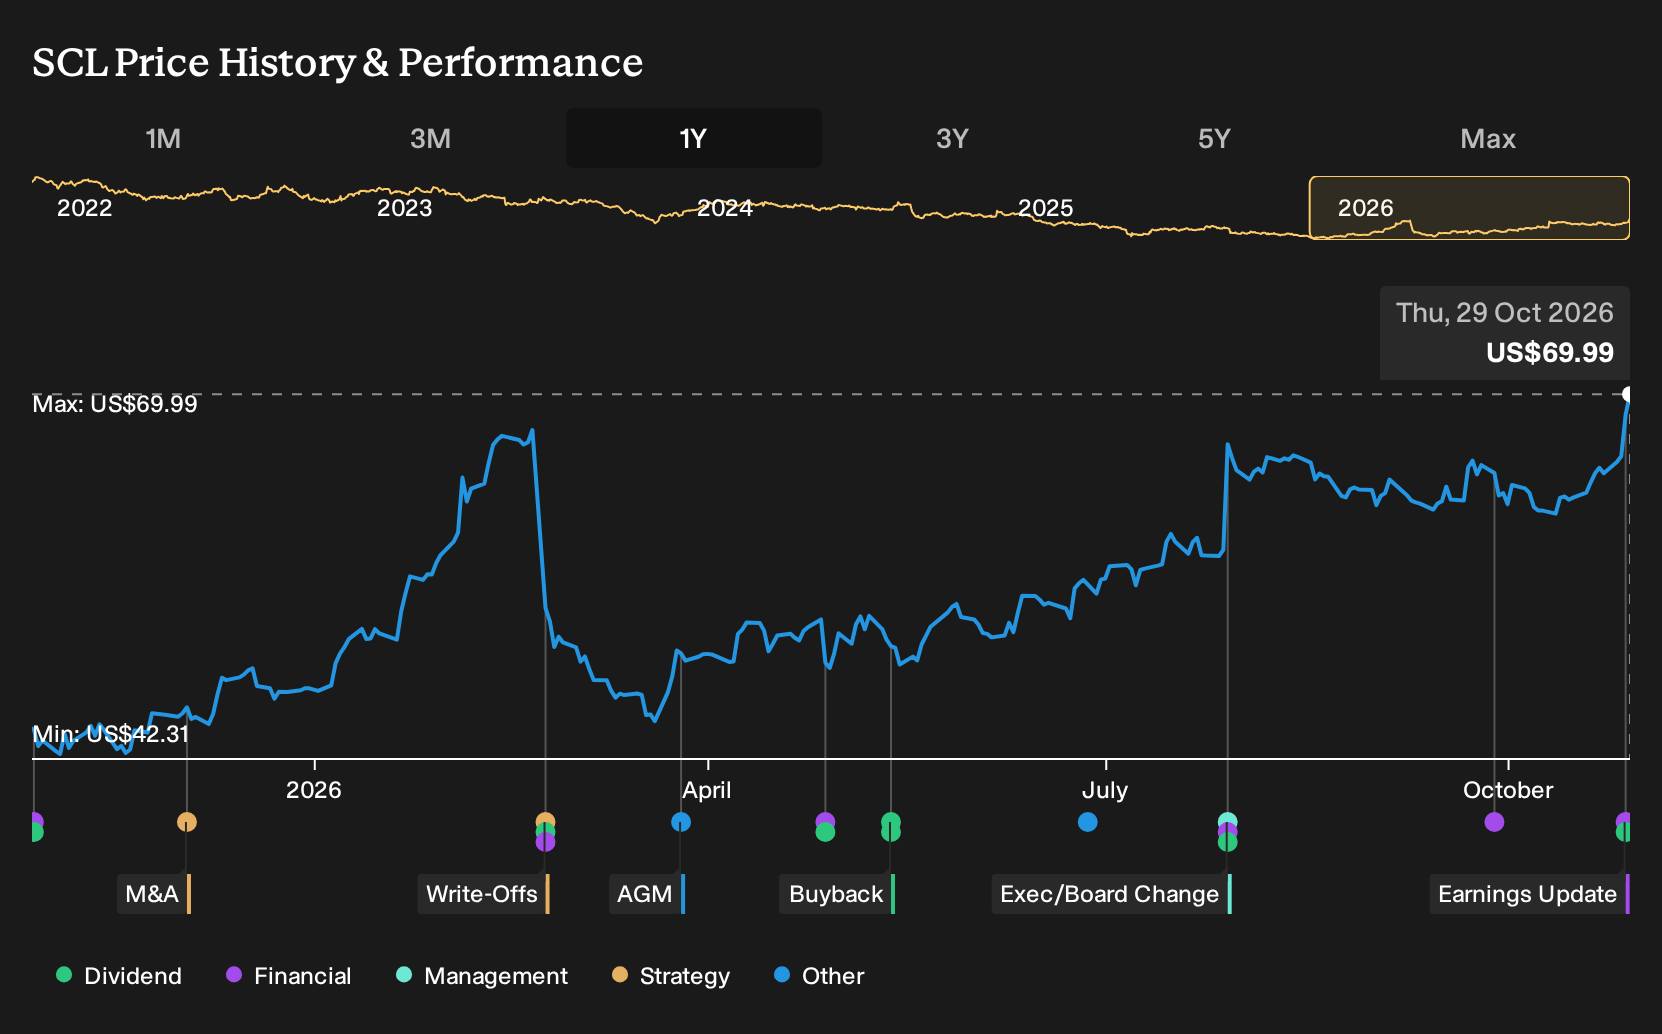
- Stepan reported third quarter 2026 sales of US$692.15 million and net income of US$17.81 million, and raised its quarterly dividend to US$0.405 per share, payable on December 15, 2026, marking the 59th consecutive annual increase.
- The stronger quarterly profit alongside a higher cash payout suggests Stepan is balancing cost savings progress, like Project Catalyst, with ongoing cash returns to shareholders.
- We will look at how Stepan's improved third quarter earnings and dividend increase reshape the existing investment narrative investors have followed.
Compare Stepan's steady dividend story with other companies that pair income with resilience by scanning our hand picked 7 dividend fortresses today.
Stepan Investment Narrative Recap
To own Stepan, you need to be comfortable with a chemicals producer that is still in the middle of a cost reset and mix shift while carrying a loss over the first nine months of 2026. The recent quarter showed higher sales and net income, which helps the story. However, the key short term catalyst is still execution on Project Catalyst and the Pasadena ramp feeding margin recovery.
The biggest current risk is that input cost volatility or weak construction and industrial demand blunt that margin rebuild just as Stepan leans on higher value surfactants and polymers. The latest results do not remove that risk. They simply give you fresher evidence on how the cost work and volume recovery are tracking.
The most relevant fresh data point is Stepan’s third quarter earnings release. Sales reached US$692.15 million with net income of US$17.81 million, and earnings per share from continuing operations came in at US$0.78. For a business that reported a small net loss of US$0.682 million over the first nine months, that quarterly profit print matters for confidence in the reset story.
It also ties directly into the main catalysts analysts have focused on, including Project Catalyst savings and better use of the Pasadena alkoxylation facility. Higher quarterly profit gives Stepan more flexibility to keep funding closures, asset moves and efficiency work while still supporting capex and interest costs. This is particularly important given the company’s higher debt level and dividend coverage questions flagged in the risk checks.
What The Stepan Analyst Forecasts Assume
Stepan's consensus blueprint is clear on the long term destination. Analysts are working off a profile where revenue reaches US$2.8b and earnings climb to US$305.5 million by 2029, supported by higher margins and steadier use of assets like Pasadena.
Those projections rest on revenue expanding by 5.2% a year over the next three years and profit margins moving from a small loss position of about 0.1% today to 10.8% in three years. Earnings are expected to shift from a loss of US$2.7 million today to US$305.5 million by 2029, which is an increase of roughly US$308 million in absolute terms rather than a marginal tweak around the edges.
Stepan's narrative projects US$2.8b revenue and US$305.5 million earnings by 2029. This implies 5.2% yearly revenue growth and an earnings increase of about US$308 million from current earnings of a US$2.7 million loss.
On that 2029 earnings figure, analysts frame a P/E of 8.1x as the anchor multiple. This sits below the reported 22.4x for the wider US Chemicals industry in the same snapshot. The gap between that future 8.1x and the current P/E, which is based on loss making earnings today, highlights how much of the Stepan reset story is about getting back to a cleaner earnings base rather than stretching the valuation multiple.
Share count assumptions stay restrained, with forecasts pointing to roughly 0.5% annual growth in shares on issue over the next three years. That matters if you care about per share progress, because meaningful earnings growth with only modest dilution can leave more of that improvement landing in each share you own.
Put together, these inputs underpin the consensus fair value work, which targets earnings of US$305.5 million on US$2.8b of sales in 2029. Analysts then discount those numbers back to today using a rate of about 8.1%, which is close to the 8.08% discount rate cited in the Simply Wall St report, to judge whether the current US$62.74 share price lines up with their US$85.0 target or not.
Uncover why Stepan's fair value indicates a 21% potential upside to its current price, a gap that could narrow quickly once confidence in Stepan’s reset builds.
Exploring Other Perspectives
Community sentiment around Stepan is split. Two fair value estimates from the Simply Wall St Community span roughly US$85 to about US$159, which is a wide band for the same stock. You are weighing that spread against real world factors such as Project Catalyst progress, the Pasadena ramp up and ongoing input cost swings. Explore those contrasting views before deciding where you stand.
Explore another Stepan fair value estimate, including one that suggests it could be worth just $85.00!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Stepan research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Stepan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stepan's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stepan?
If Stepan has sharpened your focus on quality and risk, use that same lens across the wider market. The Simply Wall St Screener can help you quickly sort through thousands of listings so you spend time weighing a curated short list rather than starting from scratch each time.
- If capital preservation sits high on your priority list, start with a basket of companies that score well on resilience and balance sheet strength via the 30 resilient stocks with low risk scores.
- When you want to pair financial quality with valuations that still look reasonable, filter for companies combining healthy fundamentals with valuations the market has not fully rewarded yet using the 30 high quality undervalued stocks.
- For investors who like finding future candidates before they hit every headline, hunt through a focused group of under the radar stocks with strong foundations by running the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com