
Blackbaud (BLKB) Stock Could Be Reasonable After A 37% Five Year Fall
Blackbaud has had a choppy ride, with the share price down 36.9% over the past 5 years, so the real question today is whether the current valuation still lines up with what its earnings can support. Recent product launches and AI-focused initiatives have put fresh attention on the business, which puts the spotlight squarely on the earnings power behind the stock.
- The share price decline of 36.9% over 5 years raises the issue of whether the market has adjusted too far or not far enough for Blackbaud's earnings profile.
- The push into AI tools and the broader Platform for Good offering may support different expectations for profitability and cash generation compared with the past.
- There is a second opinion on Blackbaud worth weighing. See what analysts think Blackbaud's shares could be worth.
The stock's next move may depend on whether Blackbaud's current price is adequately supported by the earnings it is generating today.
If you want to test the same earnings question you are asking of Blackbaud across a wider field, line it up against 38 profitable AI stocks that aren't just burning cash.
Does Blackbaud Look Undervalued on Earnings?
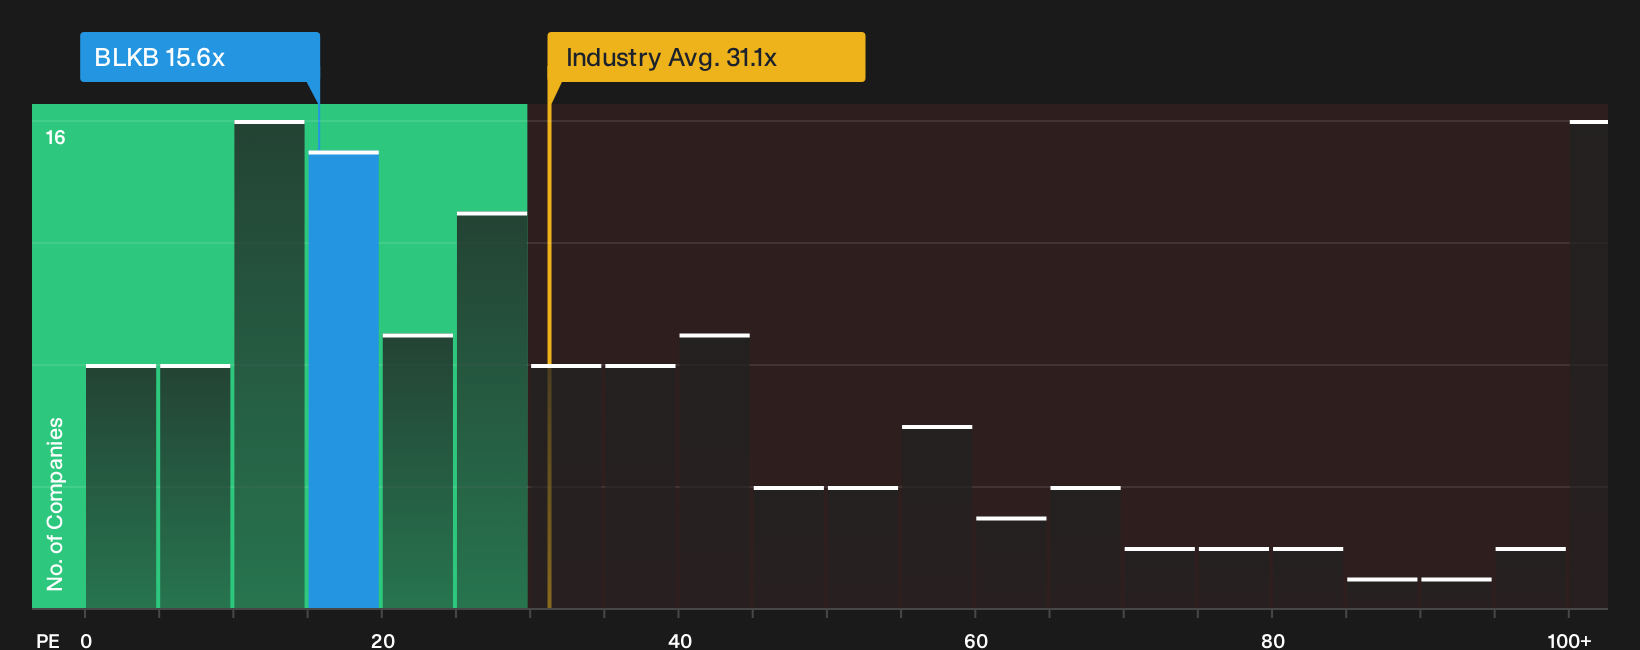
The P/E ratio aligns closely with Blackbaud because the story investors are weighing focuses on earnings power rather than assets. Blackbaud trades on a P/E of 15.6x, which is well below the broader software sector on 31.1x and also under the peer group around 40.1x. Within this framework, the Fair Ratio model, which incorporates the firm’s growth profile, profitability and risk, indicates a higher P/E than where the shares trade today, so the stock screens as undervalued on an earnings basis.
Because management has been emphasizing AI products such as Lantern and the wider Platform for Good, and has reaffirmed guidance for 2026, the current discount to typical software valuations suggests investors remain cautious about the durability of that earnings stream. For anyone assessing Blackbaud, the key question is whether the quality and consistency of future profits justify the gap that the P/E screen is highlighting today. Explore the numbers behind Blackbaud's P/E valuation.
The Blackbaud Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion on Blackbaud leaves off by spelling out what kind of growth, margins and earnings profile would need to hold for the stock to look meaningfully cheaper or more expensive than it appears today on the Community page. Each narrative ties a fair value estimate to a specific set of potential catalysts and risks in Blackbaud's story, so you can track over time which version seems closer to reality.
The Simply Wall St community is broadly constructive on Blackbaud, although one camp sees more upside in the story than the other.
Bull case: 9% undervalued
"Blackbaud's large proprietary data moat across philanthropic behavior, benchmark data and specialized datasets that are not available to public LLMs supports differentiated AI outcomes for customers..."
Discover why this Narrative puts Blackbaud at 9% undervalued.
Bear case: roughly fairly valued
"The narrative leans heavily on a resilient social impact sector and on transaction based revenue from donations and tuition..."
Explore why this Narrative puts Blackbaud at roughly fairly valued.
One more Blackbaud check before you move on
Price ratios tell you what the market is paying for Blackbaud today, yet the analyst view on where earnings and cash flows might sit a few years out offers a different reference point worth lining up next. Explore where analysts expect Blackbaud to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com