
Missed Out On Boozt's Run? Here's What Holders Saw
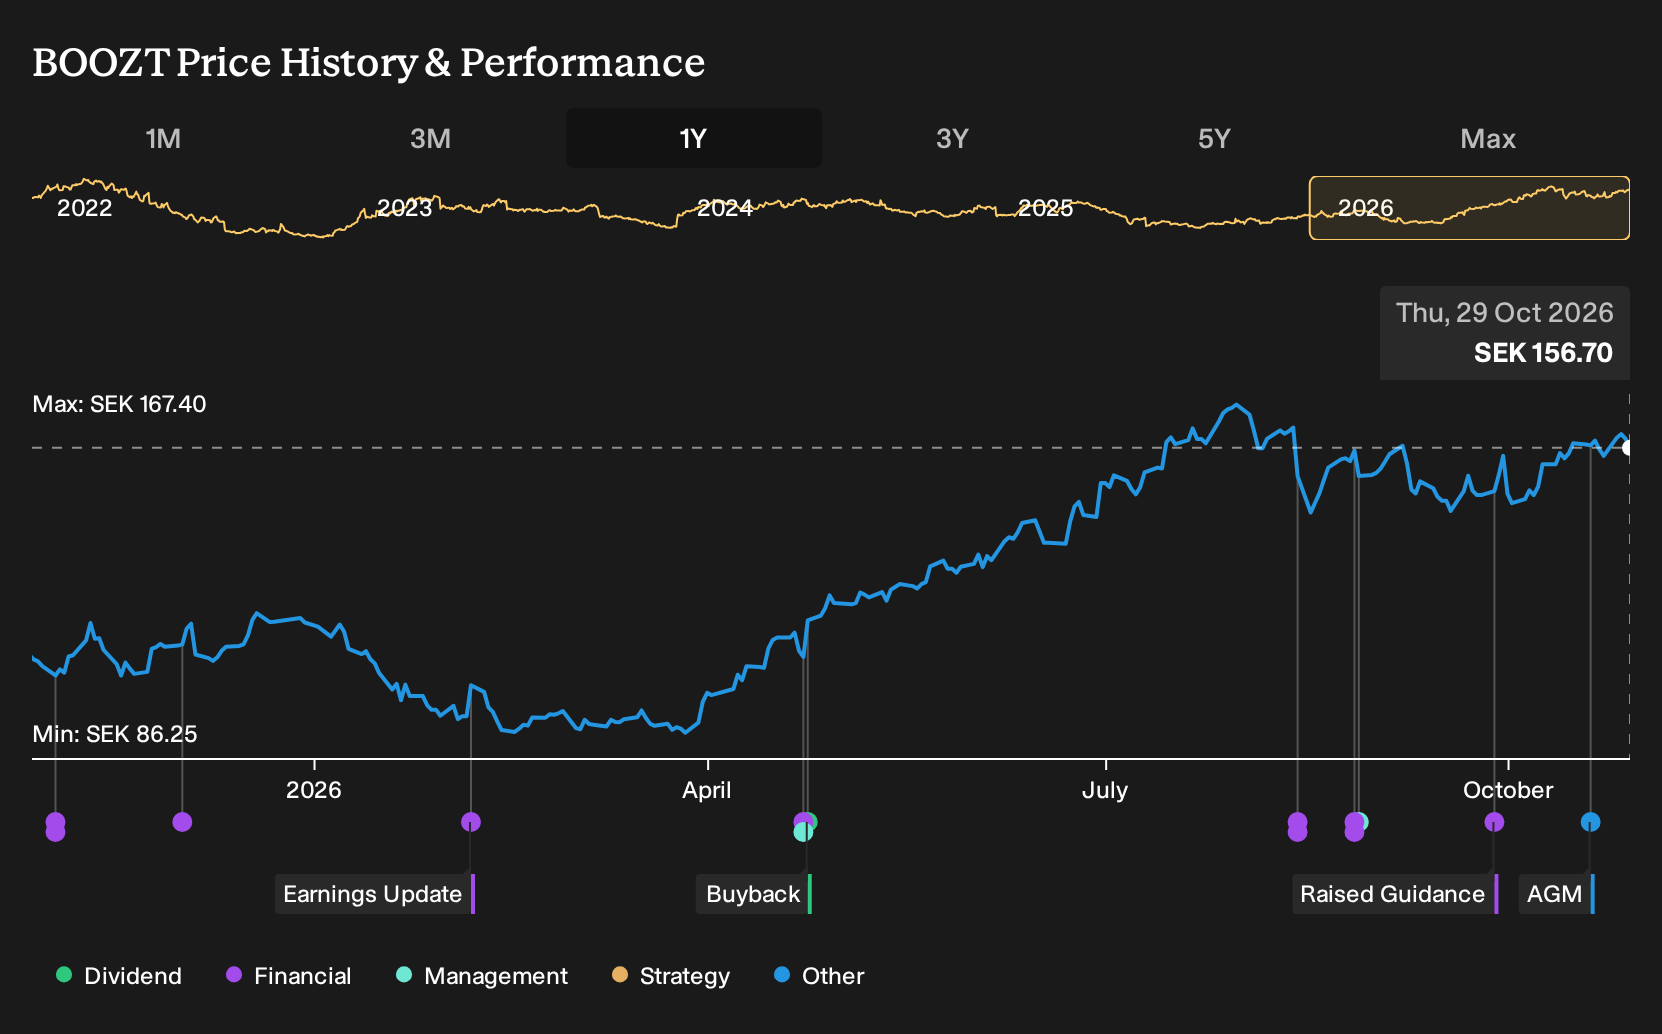
If you had backed Boozt when analysts were split between a bullish SEK110 view and a more cautious SEK93.08 estimate, the outcome looks very different today. Holding Boozt over the past year would have returned 50.8%, including dividends. That kind of move forces a question. If you were deciding on 29 October 2025, how would you have weighed premium Nordic fashion ambitions against the concern that deeper discounting and weaker margins might linger longer than hoped?
The easy part of this move is behind Boozt. Zero in on 198 high quality undervalued stocks for companies trading below our estimates.
The Two Boozt Stories Investors Had To Hold In Their Heads
The shares cost SEK104 at the start of the period, and anyone looking at Boozt then had to choose which story felt more convincing.
The bullish view anchored on a Fair Value of SEK110, a price those assumptions implied if they played out, built around revenue growth of 7.8% a year and profit margins reaching 4.9% within roughly three years.
The more cautious narrative pointed to a Fair Value of SEK93.08, with analysts accepting revenue growth of 7.3% but expecting profit margins to drift down to 4.2% as discounting and clearance activity stayed heavy.
What The Results Changed In The Boozt Debate
The Q2 2026 numbers gave Boozt investors an awkward mix. Revenue moved from SEK1,823m in Q2 2025 to SEK2,061m in Q2 2026, which leaned toward the optimistic growth story. Net income slipped from SEK76m to SEK70m and net margin went from 4.2% to 3.4%. That weaker profitability kept the cautious case alive.
The lesson is simple. When you weigh a Boozt style debate, test any margin upgrade story directly against reported net margin, not just headline sales momentum.
What Boozt’s Share Price Now Asks You To Believe
Boozt trades at SEK157 today after a 50.8% gain over the past year. The selected Narrative’s Fair Value sits above the current price, which reflects its own assumptions rather than a proven truth.
That Narrative leans on efficiency gains, broader categories and logistics improvements. It argues today’s price still does not fully credit durable market share gains from this model.
"Strengthening of logistics, automation, and AI adoption drives improved efficiency, customer experience, and operational margins against a backdrop of normalizing demand and online retail growth. Diversified product offerings, exclusive brands, and a consolidated market favor Boozt's competitive positioning, supporting higher profits and the potential for market share gains."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 48% below our estimate - uses modular building methods and digital tools to target higher-margin projects.
- Company 2 - 33% below our estimate - uses a dense retail network and nutrition launches to strengthen its dairy franchise.
- Company 3 - 39% below our estimate - develops AI driven peripherals and collaboration devices aligned with hybrid-office technology budgets.
That is three of the list. See the full list of 204 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com