
Hawaiian Electric Industries (HE) Could Be 6% Undervalued As Wildfire Risk Eases
Hawaiian Electric Industries (HE) has drawn attention after recent price moves left the stock down over the past month and past 3 months, even as investors reassess its US$1.4b market value.
Across longer periods the picture has been much tougher for Hawaiian Electric Industries shareholders. The share price return is down 33.8% over 3 months and the year-to-date share price return is down 32.3%, while the 1 year total shareholder return has fallen 26.2% and the 5 year total shareholder return is down 77.4%. This suggests that recent weakness reflects an ongoing reassessment of risk rather than a short term wobble.
Broaden your watchlist beyond Hawaiian Electric Industries by scanning a curated set of utilities and infrastructure players with resilient balance sheets using the list of solid balance sheet and fundamentals (23 results).
Hawaiian Electric Industries still runs a critical utility franchise in Hawaii, yet the share price reset has been steep. Is the current US$1.4b valuation a fair reflection of that franchise, or an overcorrection?
Most Popular Narrative: 6% Undervalued
The most followed narrative puts Hawaiian Electric Industries' fair value at $9.06, slightly above the recent $8.55 close, which implies modest undervaluation while still recognising the legal and balance sheet overhangs that shaped that estimate.
Recent Hawaii legislation enabling wildfire liability caps, state funding for settlements, and securitization of wildfire safety investments significantly reduces legal and financial risk exposure while supporting large-scale infrastructure upgrades, which is likely to stabilize earnings and improve net margins.
Progress in implementing enhanced wildfire safety measures, supported by dedicated funding mechanisms, reduces future risk of catastrophic losses, strengthens public trust and regulatory goodwill, and may result in more favorable treatment of capital expenditures in rate base calculations, which could positively impact future regulated earnings and revenue stability.
See why 16 investors see Hawaiian Electric Industries as 6% undervalued.
Result: Fair Value of $9.06 (UNDERVALUED)
Still, wildfire litigation costs and the high spending required for grid resilience could absorb much of Hawaiian Electric Industries' cash and strain its balance sheet.
Find out about the key risks to this Hawaiian Electric Industries narrative.
Another View: Hawaiian Electric Industries Through A Cash Flow Lens
The earlier narrative leans on analyst targets and earnings multiples to argue Hawaiian Electric Industries looks about 6% undervalued at $9.06 per share. A different tool, the SWS DCF model, paints a far harsher picture, putting future cash flow value at just $2.88 and flagging the stock as overvalued on that basis.
Those two signals could not be further apart. One framework says Hawaiian Electric Industries trades on a low P/E and screens as good value against peers, while the cash flow view suggests the current price builds in more optimism than the model is comfortable with. Which yardstick do you trust when earnings look cheap but modeled cash generation points the other way?
Look into how the SWS DCF model arrives at its fair value.
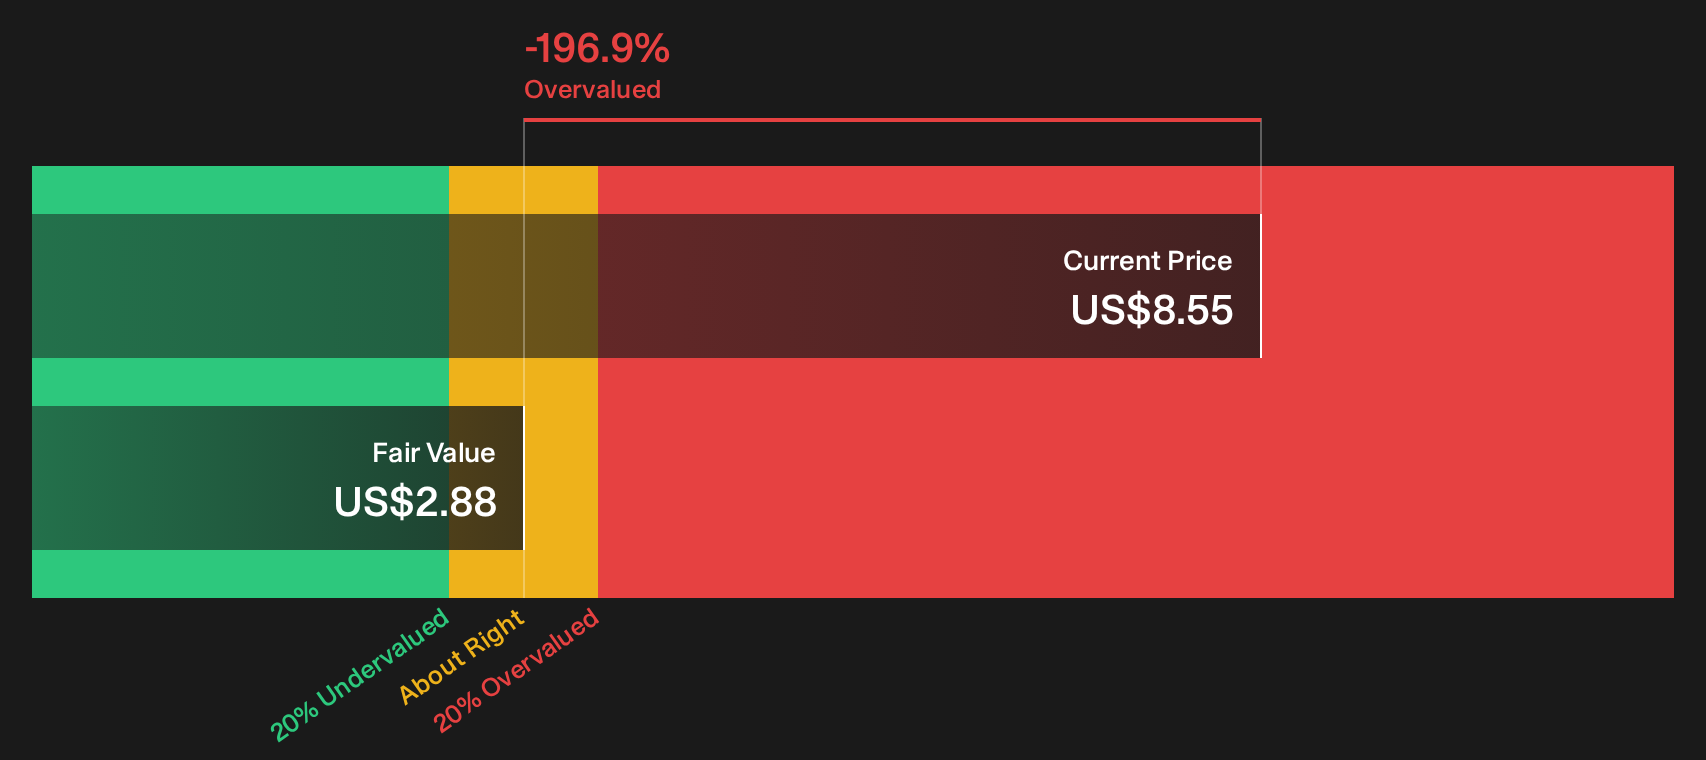
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawaiian Electric Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Hawaiian Electric Industries is split, and that is exactly why the data matters most right now. Move quickly, review the numbers, and weigh both the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hawaiian Electric Industries?
If Hawaiian Electric Industries has your attention, do not stop here. Broaden your opportunity set and pressure test your thesis against fresh ideas across the market.
- Target potential mispricings by scanning a curated pool of resilient businesses that screen as compelling on valuation with the 30 high quality undervalued stocks.
- Prioritise stability and capital strength by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (23 results).
- Spot under-the-radar opportunities by focusing on quality enterprises that the crowd has largely missed through the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com