
CMS Energy (CMS) Earnings Test Fair Value As Grid Spending Story Holds
CMS Energy (CMS) just put fresh numbers on the table, with third quarter earnings showing a sharp earnings per share drop while management kept adjusted EPS targets intact and highlighted ongoing Michigan infrastructure and clean energy spending.
Recent trading has turned more supportive, with a 30 day share price return of 9.57% after a weaker patch that left the year to date share price still down 1.28% and the 1 year total shareholder return lower by 2.07%.
Compare CMS Energy's earnings reset and grid investment story with other regulated utilities by scanning our hand picked 43 power grid technology and infrastructure stocks built around companies shaping tomorrow's electricity infrastructure.
The rebound in CMS Energy after weaker earnings puts the focus squarely on price. Does the recent 30 day surge still leave enough upside in the risk reward for new buyers?
Most Popular Narrative: 7% Undervalued
CMS Energy last closed at $69.52, compared with a most-followed fair value estimate of $74.69 that points to a modest undervaluation using a 7.24% discount rate.
The exit from nonutility renewable development and the redeployment of roughly $1.7b of planned capital into Michigan rate-base projects is expected to concentrate CMS Energy earnings on regulated assets that typically carry defined returns. This structure could support more predictable EPS and cash flow.
See why 4 investors see CMS Energy as 7% undervalued.
Result: Fair Value of $74.69 (UNDERVALUED)
Still, CMS Energy's story can unravel if Michigan regulators take a tougher line on cost recovery, or if severe storms keep driving higher and less predictable operating expenses.
Find out about the key risks to this CMS Energy narrative.
Another View: CMS Energy Through The P/E Lens
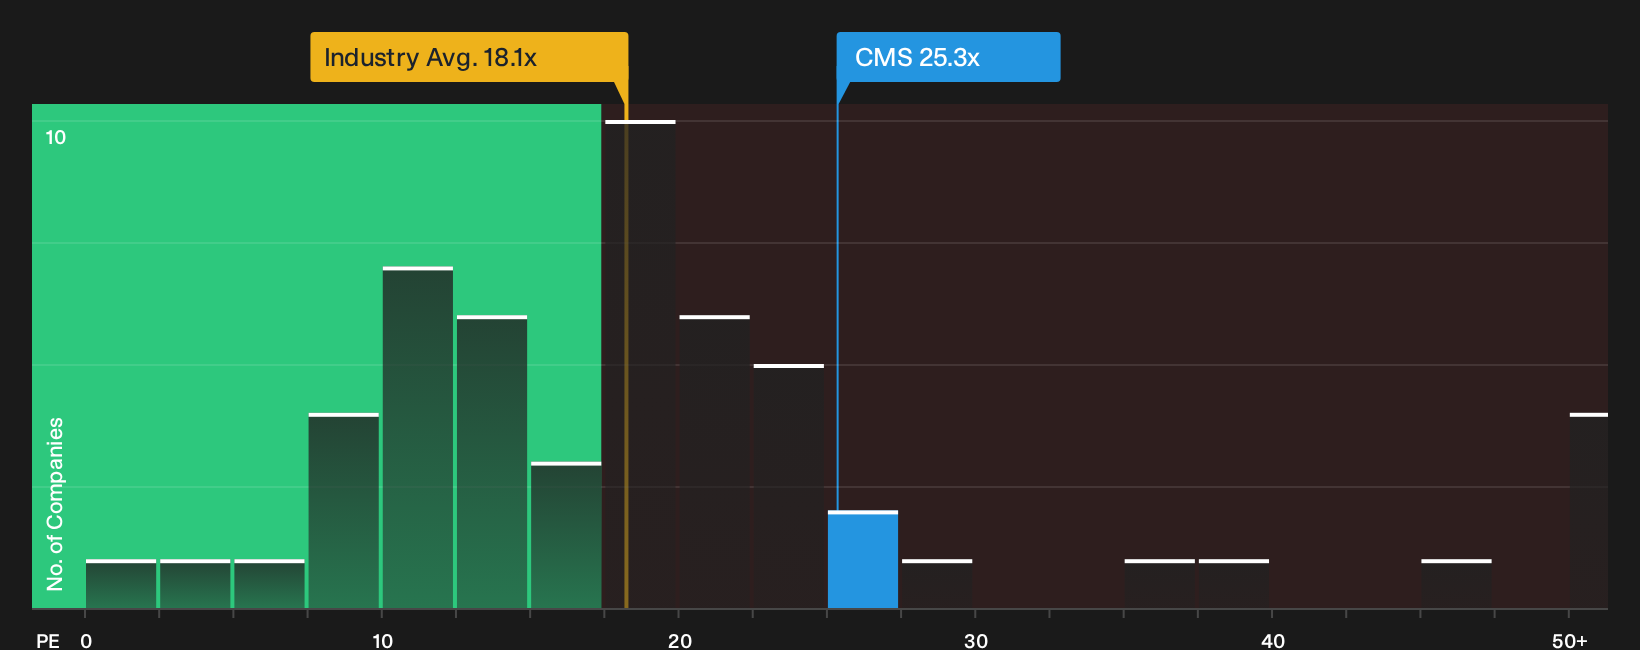
On price tags, CMS Energy tells a different story. The stock trades on a P/E of 25.3x, compared with about 22x for peers and 18x for the broader Integrated Utilities group, while the fair ratio sits nearer 21.6x. That gap points to higher valuation risk if sentiment cools.
For a closer look at how this pricing stacks up against earnings power and peers, take a moment to work through our valuation breakdown, then weigh whether the premium feels justified for your own timeframe and risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can pull investors in different directions, so act promptly on the numbers and weigh the 2 key rewards and 3 important warning signs carefully.
Looking for more CMS Energy style investment ideas?
If CMS Energy has sharpened your focus on price, risk, and quality, do not stop here. Broader research can reveal opportunities that fit your exact goals.
- Target durable quality by scanning a list of solid balance sheet and fundamentals (23 results) that filters for companies with sturdier finances backing their future plans.
- Hunt for mispriced potential through a 18 high quality undiscovered gems that spotlights under-the-radar businesses with strong fundamentals.
- Dial back downside risk by checking a 30 resilient stocks with low risk scores built around resilient stocks that score well on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com