
Are Stronger Earnings Altering The Investment Case For Alma Media Oyj (HLSE:ALMA)?
- Alma Media Oyj reported third quarter 2026 sales of €84.2 million and net income of €20.5 million, with basic EPS from continuing operations at €0.25.
- Over the first nine months of 2026, Alma Media Oyj reported net income of €54.6 million on €255.2 million of sales.
- We will now look at how Alma Media Oyj's nine month net income trend could influence the existing investment narrative.
Alma Media Oyj Investment Narrative Recap
To own Alma Media Oyj you need to believe the digital classifieds and media platform can keep converting its audience reach into solid earnings, even while Finnish housing and mobility markets stay soft. The latest quarter showed higher sales and net income compared with last year, which supports that basic earnings engine rather than changing the story.
For the near term, the key swing factor is still how well Alma Media Oyj can push higher value digital products and AI driven services while managing overlapping ICT and cloud costs. The biggest operational risk remains pressure on Marketplaces if weak transaction volumes in property and mobility persist and start to squeeze pricing or volumes.
The fresh nine month 2026 earnings release is the clearest relevant update. Sales of €255.2 million and net income of €54.6 million for the period indicate Alma Media Oyj is running with a higher profit base than a year ago, with basic EPS from continuing operations at €0.66 versus €0.52.
That uplift in profitability gives management more room to keep funding AI, automation and platform integration, which are central to the medium term catalyst list. It also partly offsets the risk that slower housing transactions, a flat used car market and any renewed advertising softness could limit what Alma Media Oyj can charge for its Finnish classifieds and media inventory.
Alma Media Oyj's current analyst playbook points to revenues of €373.0 million and earnings of €85.9 million by 2029, based on a projected 3.6% yearly revenue growth rate and an earnings increase of €22.7 million from €63.2 million today.
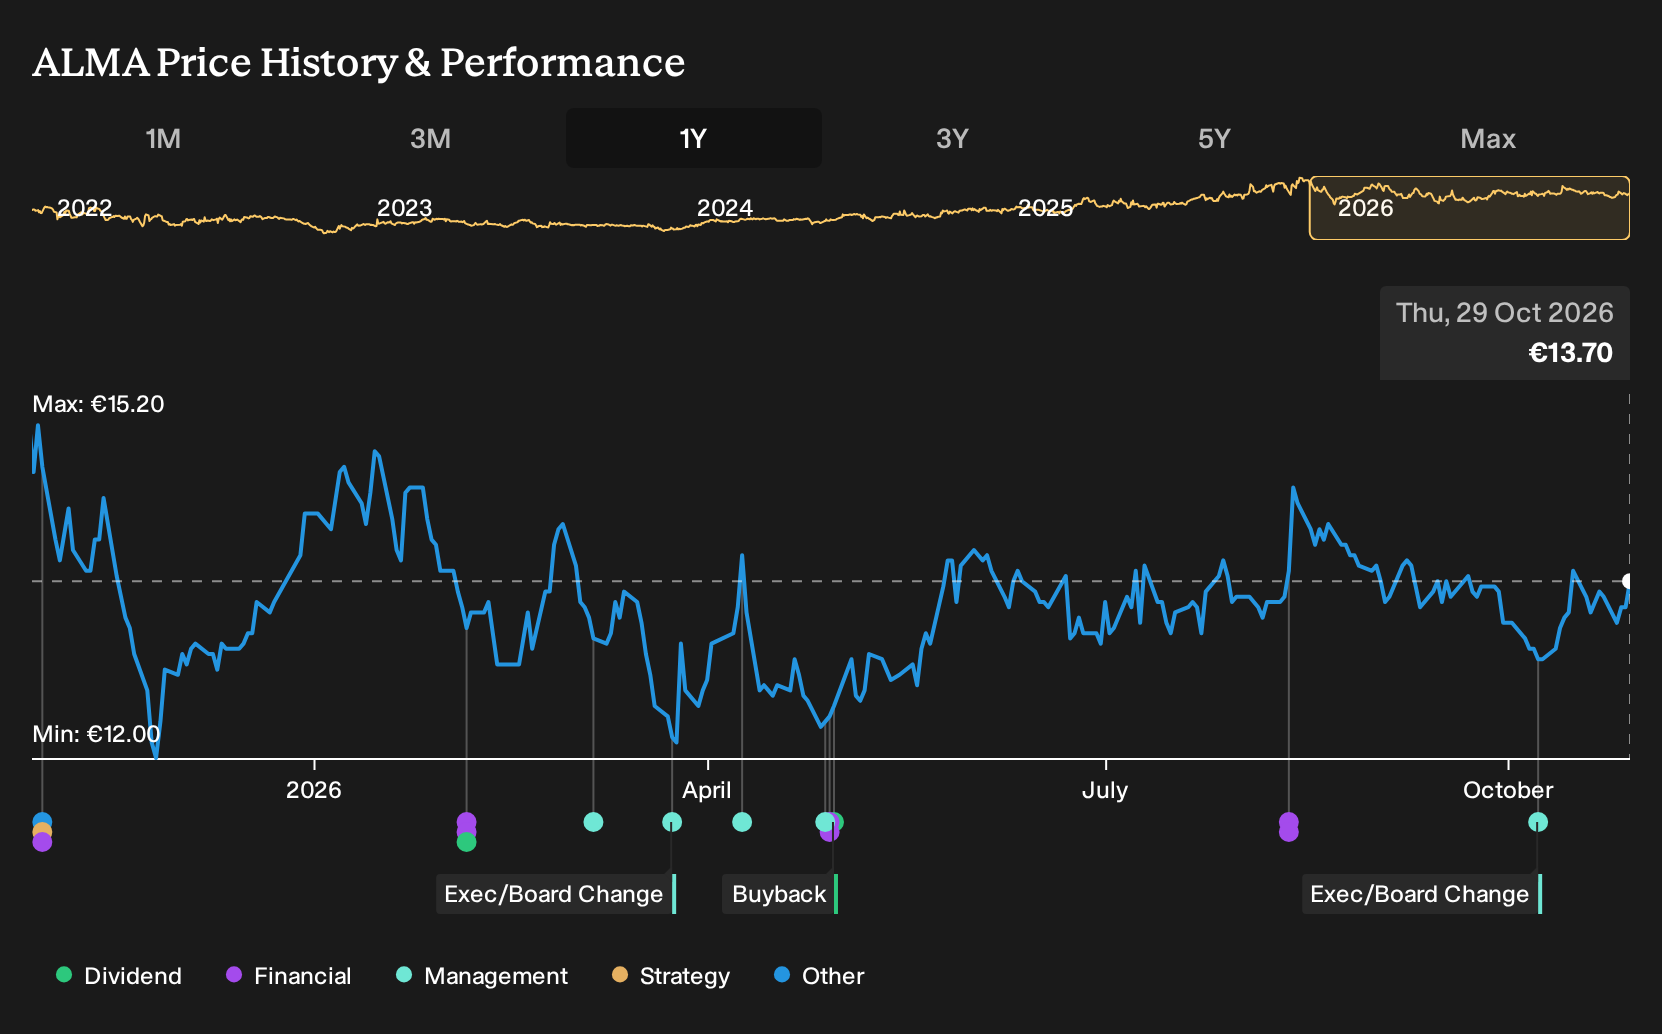
Uncover why Alma Media Oyj's fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between €15.73 and €15.93, so you see almost no spread in those pre earnings views. That narrow band can still clash with risks around weak Finnish housing and mobility demand, which could affect how Alma Media Oyj converts recent earnings into future resilience. Investor opinions can differ widely, so explore several community viewpoints before leaning on any single narrative.
Explore another Alma Media Oyj fair value estimate, including one that suggests it could be worth just €15.73.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alma Media Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alma Media Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alma Media Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alma Media Oyj?
Once you have formed a view on Alma Media Oyj, it often pays to widen the opportunity set and line it up against other stocks with clear financial stories using the Simply Wall St Screener.
- If you want potential value on your side, compare Alma Media Oyj with a curated pool of companies trading on appealing metrics through the 196 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you, check how Alma Media Oyj stacks up against 227 resilient stocks with low risk scores that score well on Simply Wall St's risk framework.
- If you care about balance sheet strength and fundamentals, set Alma Media Oyj beside a list of solid balance sheet and fundamentals (205 results) to see which businesses look more robust on core financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com