
Abercrombie & Fitch (ANF) Beat Expectations, Does The Stock Look Fully Valued?
Abercrombie & Fitch (ANF) just posted quarterly results that topped expectations, with strong same store sales, firm gross margins, and ongoing share repurchases drawing fresh attention to the retailer’s earnings power and balance sheet.
Abercrombie & Fitch’s recent beats on earnings and margins slot into a strong run, with the share price up 24.09% over 30 days and delivering a 129.53% total shareholder return over one year, pointing to momentum that investors clearly have not ignored.
Scan how Abercrombie & Fitch’s momentum compares with other retailers showing strong earnings quality and balance sheets by reviewing the hand picked list of solid balance sheet and fundamentals (23 results)
After a run like this, Abercrombie & Fitch now presents a simple choice in direction. Do you pay up for momentum today, or wait and hope the next pullback lines up with the current valuation math?
Most Popular Narrative: 1% Overvalued
Abercrombie & Fitch closed at $165.77, which sits slightly above the most followed fair value estimate of $163.55 that uses an 8.59% discount rate. The current price roughly matches the long term narrative but with a small premium attached.
The key requirement is that Abercrombie & Fitch converts current channel expansion, tariff mitigation efforts and technology upgrades into durable operating margins once temporary tariff refunds roll off.
The updated view emphasizes ongoing sourcing changes, pricing actions and IEEPA refunds that are currently supporting gross margin and operating margin despite structural tariff costs.
See why 91 investors see Abercrombie & Fitch as 1% overvalued.
Result: Fair Value of $163.55 (OVERVALUED)
Still, this narrative can crack if tariff refunds fade faster than expected, or if weaker regions like EMEA and APAC continue to drag on Abercrombie & Fitch’s consistency.
Find out about the key risks to this Abercrombie & Fitch narrative.
Another View: Abercrombie & Fitch Through The P/E Lens
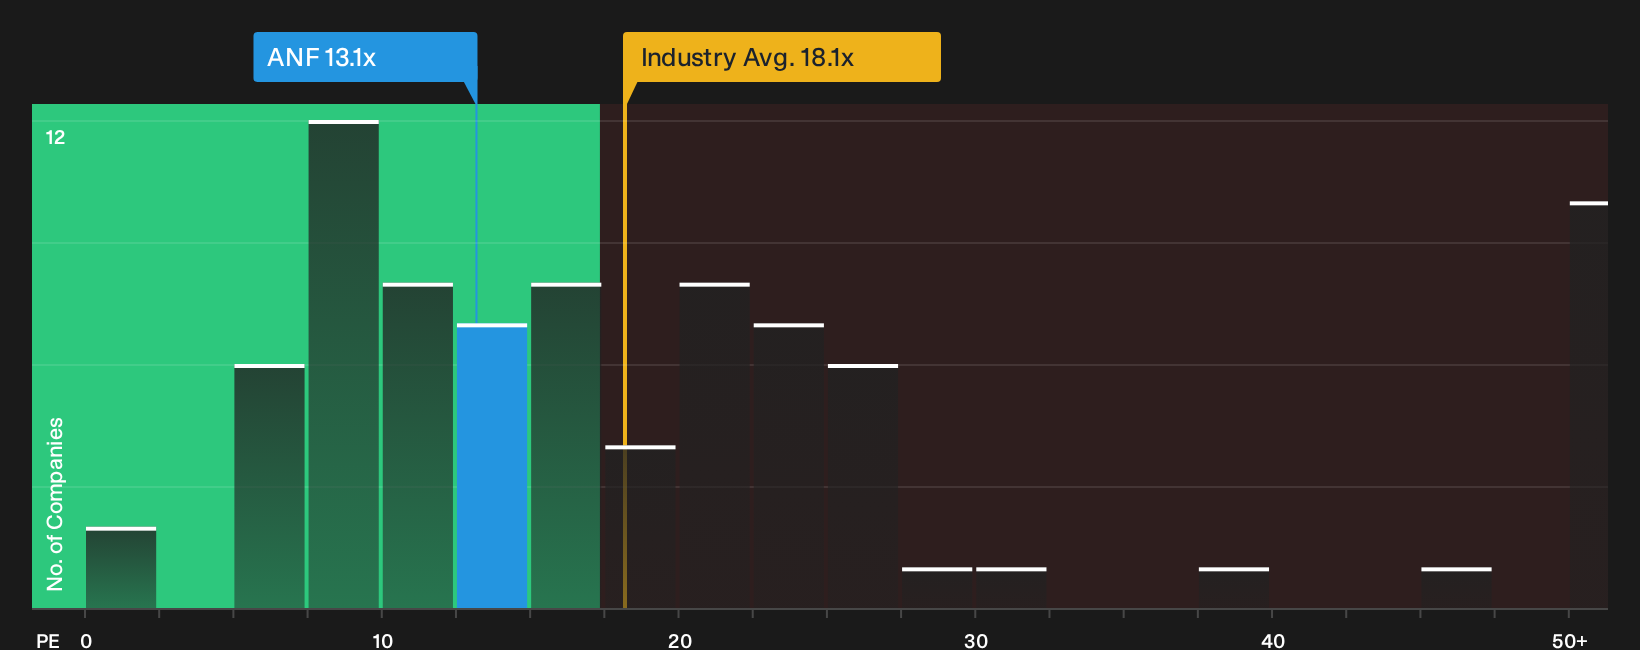
Fair value math based on future earnings calls Abercrombie & Fitch slightly overvalued at $163.55, yet the share price around $165.77 still lines up with a different story. On a 13.1x P/E, the stock trades below the 13.7x fair ratio, below the 14.2x peer average and below the 17x US Specialty Retail industry. That kind of discount can either flag a margin of safety or hint that the market is pricing in earnings risk. Which side do you think it is on?
To stress test that question against hard numbers, review how this valuation compares across peers and the fair ratio in our detailed multiple breakdown, then see what the numbers say in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear message? With both risks and rewards on the table for Abercrombie & Fitch, move quickly, review the details, and weigh the balance across the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Abercrombie & Fitch?
If Abercrombie & Fitch has sharpened your focus on quality and valuation, use that momentum and line up your next potential opportunity before the market moves.
- Target resilient compounding potential by scanning a 30 resilient stocks with low risk scores that keeps downside in check while you focus on long term wealth building.
- Hunt for mispriced quality and review a curated 30 high quality undervalued stocks that match strong fundamentals with prices that have not fully reflected them yet.
- Build a cash flow engine and search among a select group of 7 dividend fortresses that aim to combine robust payouts with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com